


Brink's (BCO) Leans On Higher Margin Growth, Is The Valuation Gap Compelling?
Brink's (BCO) has drawn fresh attention after recent trading left the shares at US$111.98, with returns mixed across short and longer periods as investors reassess this global cash management specialist.
Recent trading has tilted in Brink's favour, with a 1-day share price return of 2.46% and a 90-day share price return of 11.37%. However, the year-to-date share price return is down 3.85%, while the 5-year total shareholder return of 64.84% points to stronger longer term compounding.
Scan how Brink's compares with other security and cash management players by reviewing a curated set of list of solid balance sheet and fundamentals (23 results).
Bulls interpret Brink's recent uptick as confirmation of a solid cash management franchise, while bears highlight the weaker year-to-date and 1-year returns. Which case aligns better with what the current valuation suggests?
Most Popular Narrative: 26.8% Undervalued
Brink's last traded at $111.98, while the most widely followed valuation storyline pegs fair value closer to $153. That gap turns on how investors view its shift from traditional cash handling to higher margin services.
Rapid expansion and strong momentum in AMS (ATM Managed Services) and DRS (Digital Retail Solutions) are unlocking a significantly larger and higher-margin addressable market, with double-digit organic growth expected to accelerate in the back half of the year and into the mid-term supporting higher future revenue and net margins.
Read the complete narrative. Read the complete narrative.
If the headline is a discount to fair value, the fine print is the growth mix behind it. The narrative leans heavily on richer-margin services, expanding international exposure, and a future profit profile that looks very different to today. Curious which revenue streams and margin assumptions sit at the center of that $153 fair value call.
Result: Fair Value of $153 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Brink's story can break if cash usage weakens faster than expected or if rising digital rivals and compliance costs reduce margins.
Find out about the key risks to this Brink's narrative.
Another View on Brink's Valuation
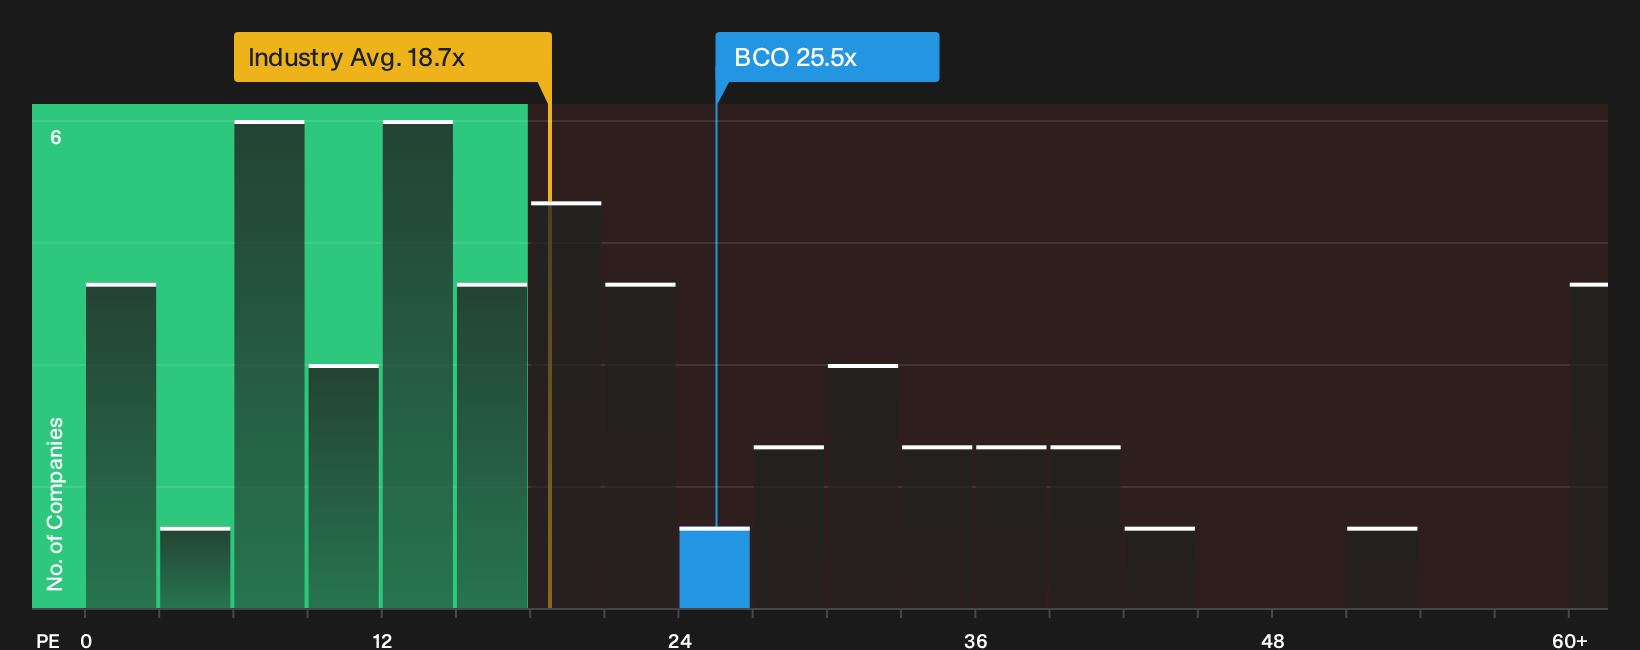
The first story around Brink's leans on a model fair value of $153, yet the plain P/E math paints a different picture. The stock trades on a P/E of 25.5x versus 17.9x for the wider US Commercial Services group and a fair ratio of 50.1x. That mix suggests investors are already paying more than the sector today while still sitting well below the fair ratio that the market could move towards. Is that a cushion, or a value trap if earnings do not keep up?
For a closer look at how the current pricing stacks up against peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If Brink's story so far feels split between promise and concern, now is the moment to test the numbers yourself and decide where you stand. To weigh both the potential upside and the key watchpoints side by side, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Brink's?
Brink's might be on your radar, but your next strong idea could come from a very different corner of the market if you cast the net wider.
- Target resilient balance sheets and steady fundamentals by reviewing a curated list of solid balance sheet and fundamentals (23 results) before conditions shift again.
- Hunt for potential mispricing by scanning a focused 32 high quality undervalued stocks that filters for quality first rather than just a low headline multiple.
- Prioritise cash returns to shareholders with a tailored 6 dividend fortresses that zeroes in on higher yields backed by underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com