


Is Axogen (AXGN) A Bargain Following Its US$208.7m Equity Raise?
Axogen’s fresh capital raise and M&A call set the stage
Axogen (AXGN) has just completed a follow on equity offering of 4,910,000 shares at about US$42.50 each, raising roughly US$208.7m, alongside an M&A call with BioCircuit Technologies.
Axogen’s latest equity raise comes after a powerful run, with the share price up 36% year to date and the 1 year total shareholder return at about 157%. This is despite the stock having fallen around 13% over the past month, as short term momentum has cooled while investors reassess growth prospects and funding risks.
Scan beyond Axogen and spot other under the radar healthcare players raising capital or preparing for their next phase of growth with our curated 15 high quality undiscovered gems
After a sharp run over the past year, a fresh equity issue at about US$42.50 resets the entry point for Axogen. Does it make more sense to step in here, or to wait for a cheaper tag before beginning valuation work?
Most Popular Narrative: 20.8% Undervalued
Axogen’s most followed valuation story points to a fair value of $53.22 against a last close of $42.16, which frames the fresh equity raise in a very different light.
Broad-based adoption of Axogen's nerve care algorithm across multiple markets (extremities, oral maxillofacial, breast) and exceptional momentum in activating high-potential accounts signal that the addressable market for nerve repair is still substantially underpenetrated, suggesting a long runway for sustained double-digit revenue growth as awareness and adoption rise.
Read the complete narrative. Read the complete narrative.
Want to see what is baked into that $53.22 figure? The narrative focuses on faster top line expansion, margin repair, and a future earnings profile that is described as anything but ordinary.
Result: Fair Value of $53.22 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Axogen story hinges on a successful Avance BLA outcome, as well as sustained demand for a largely single product driven portfolio, which could both be tested.
Find out about the key risks to this Axogen narrative.
Another View on Axogen’s valuation
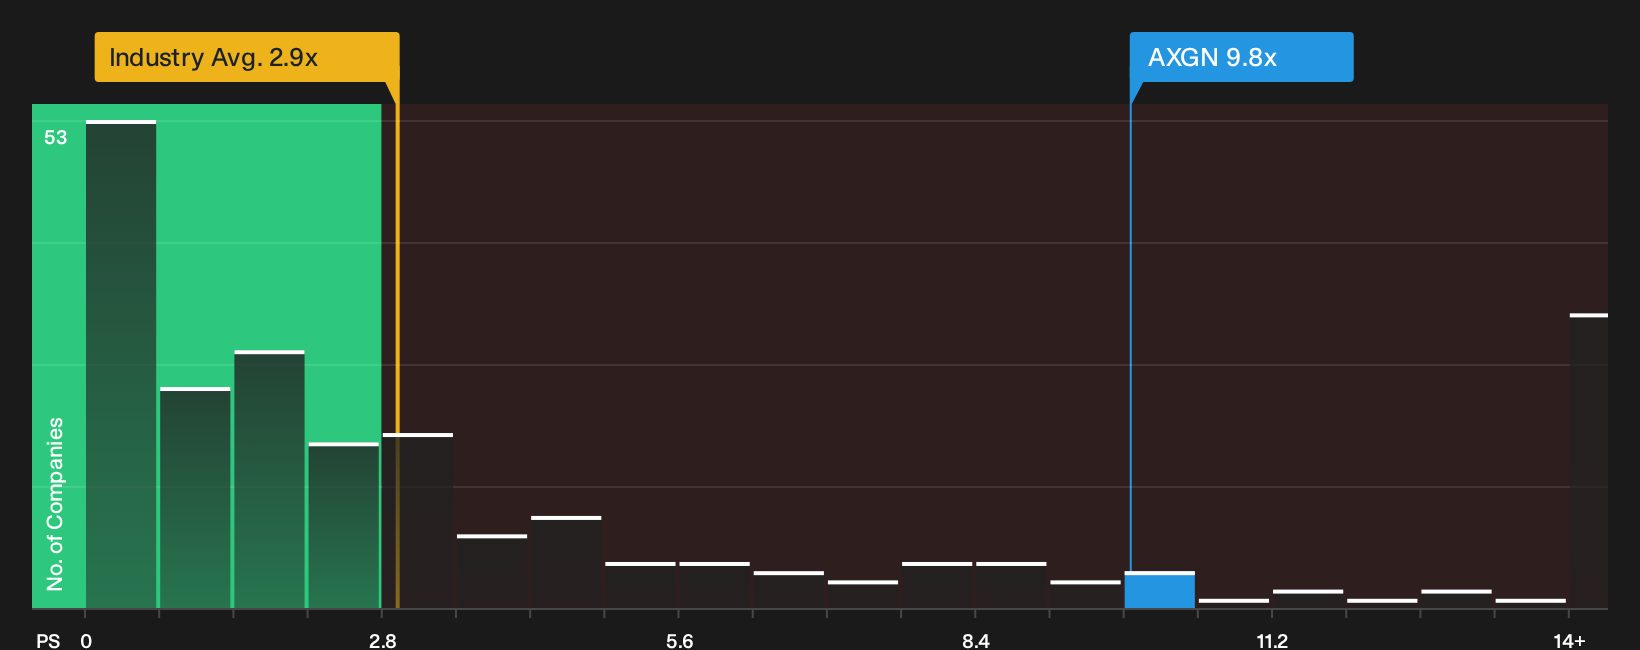
That first story leans heavily on Axogen trading below a fair value estimate of $53.22, or $49.29 on future cash flow value. Yet the share price also reflects a rich P/S ratio of 9.8x versus 2.9x for the US Medical Equipment sector and a 5.4x fair ratio, which points to meaningful valuation risk if sentiment cools.
Investors weighing this gap between discounted cash flow support and premium sales multiples may want to pressure test which set of assumptions feels more realistic for their own thesis before committing fresh capital. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Axogen can feel uncomfortable, so consider acting promptly, review the numbers yourself, and weigh both sides of the story with 3 key rewards and 1 important warning sign
Ready for more ideas beyond Axogen?
If Axogen has sharpened your thinking on valuation and growth, do not stop here. Fresh ideas often come from comparing very different businesses side by side.
Use the Simply Wall Street Screener to widen your opportunity set and avoid getting locked into a single story.
- Target income resilience by scanning companies that combine higher yields with balance sheet strength using our 6 dividend fortresses.
- Hunt for quality at a discount by filtering for businesses with strong fundamentals that still trade below estimated worth through the 32 high quality undervalued stocks.
- Reduce portfolio stress by focusing on companies with sturdier finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com