


Undiscovered Gems in Asia to Explore This September 2026
As global markets navigate the complexities of rising oil prices and inflation concerns, investors are increasingly looking to Asia for opportunities that might be overlooked in the current landscape. In this environment, a good stock is often characterized by its resilience to geopolitical tensions and ability to capitalize on regional economic growth, making it an attractive prospect for those seeking undiscovered gems.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Xinxiang Chemical Fiber | 70.11% | -0.33% | -29.16% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Dmall | 59.68% | 15.24% | 23.16% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Nice Information & Telecommunication (KOSDAQ:A036800)
Simply Wall St Value Rating: ★★★★★☆
Overview: Nice Information & Telecommunication, Inc. operates in the information and telecommunication sector, focusing on services such as payment gateway solutions and value-added network services, with a market cap of approximately ₩339.83 billion.
Operations: Nice Information & Telecommunication generates revenue primarily from its PG Division (₩554.07 million), VAN Division (₩568.40 million), and POS Division (₩70.24 million). The VAN Division contributes the most, closely followed by the PG Division, with a small adjustment and removal of ₩20.29 million impacting overall figures.
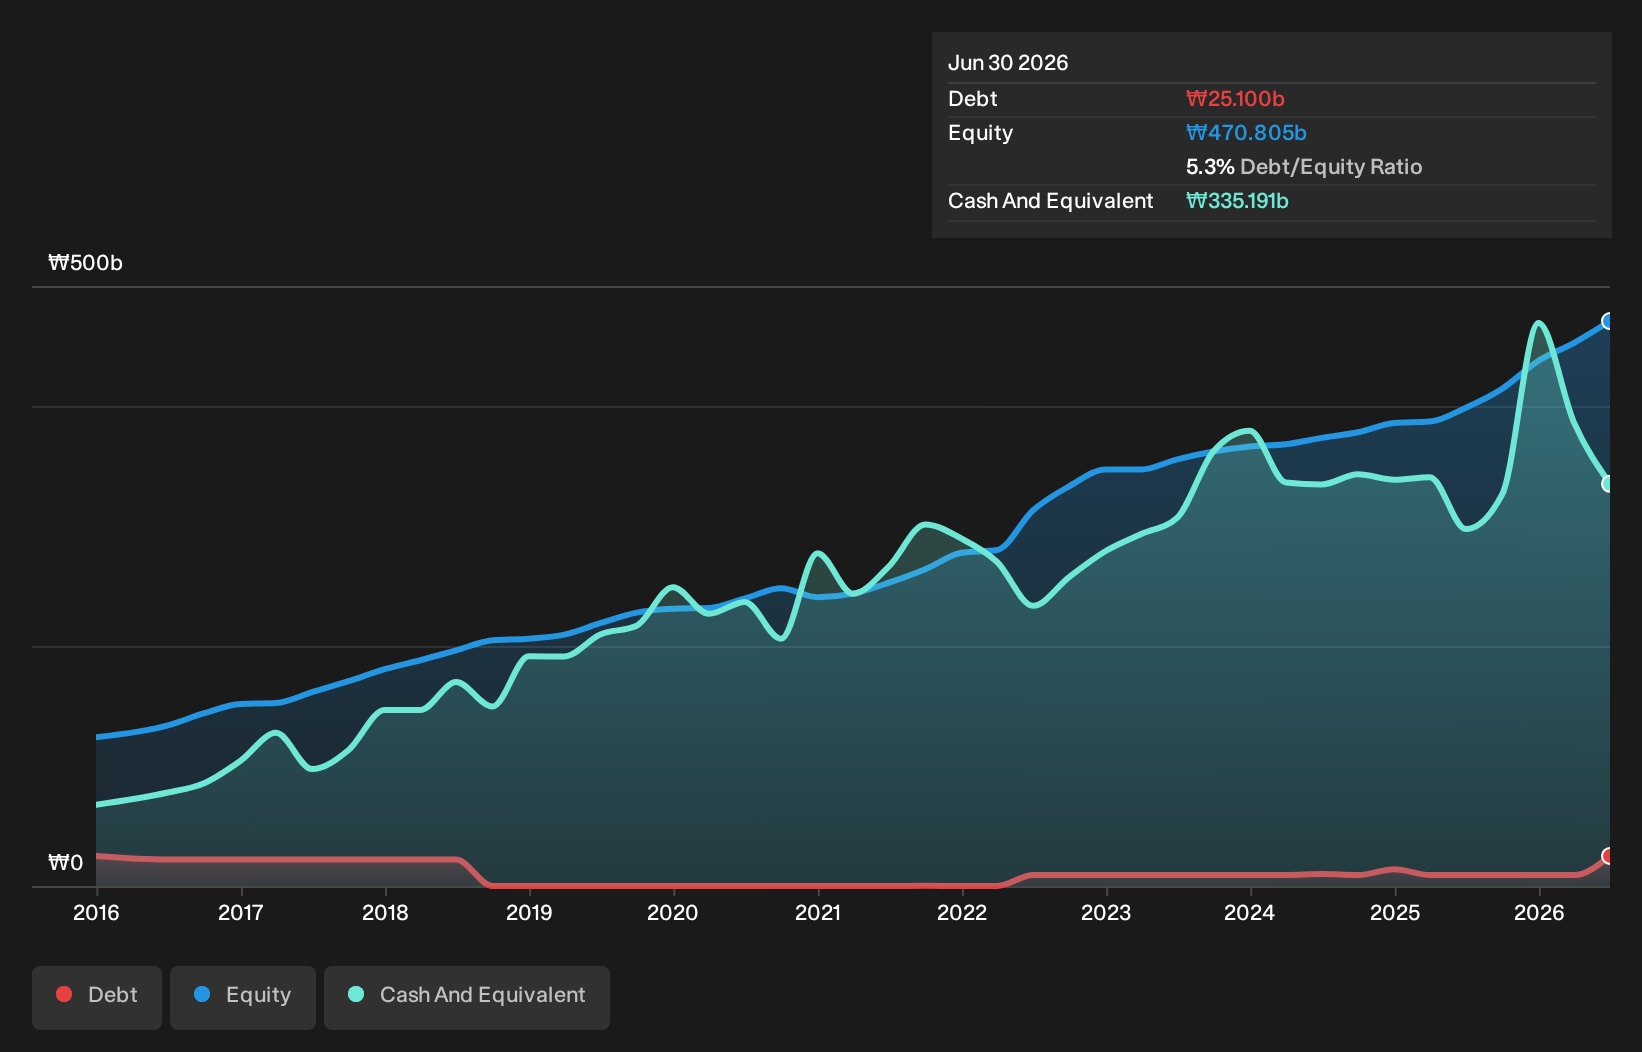
Nice Information & Telecommunication, a smaller player in the industry, has shown impressive financial health with earnings growth of 62.1% over the past year, outpacing the Diversified Financial sector's 43.3%. The company is trading at a significant discount of 36.4% below its estimated fair value and boasts high-quality earnings. Despite an increase in debt to equity from 0% to 5.3% over five years, it holds more cash than total debt, indicating solid financial footing. Recent results highlighted net income of KRW 18,757 million for Q2 and basic EPS rising to KRW 83.8 from KRW 46.6 last year.
P.S.P. Specialties (SET:PSP)
Simply Wall St Value Rating: ★★★★★☆
Overview: P.S.P. Specialties Public Company Limited, along with its subsidiaries, is engaged in the manufacturing and sale of lubricant and grease oils in Thailand, with a market capitalization of THB10.99 billion.
Operations: P.S.P. Specialties generates revenue primarily from its Sales Segment, which accounts for THB13.34 billion, while the Services Segment contributes THB678 million.
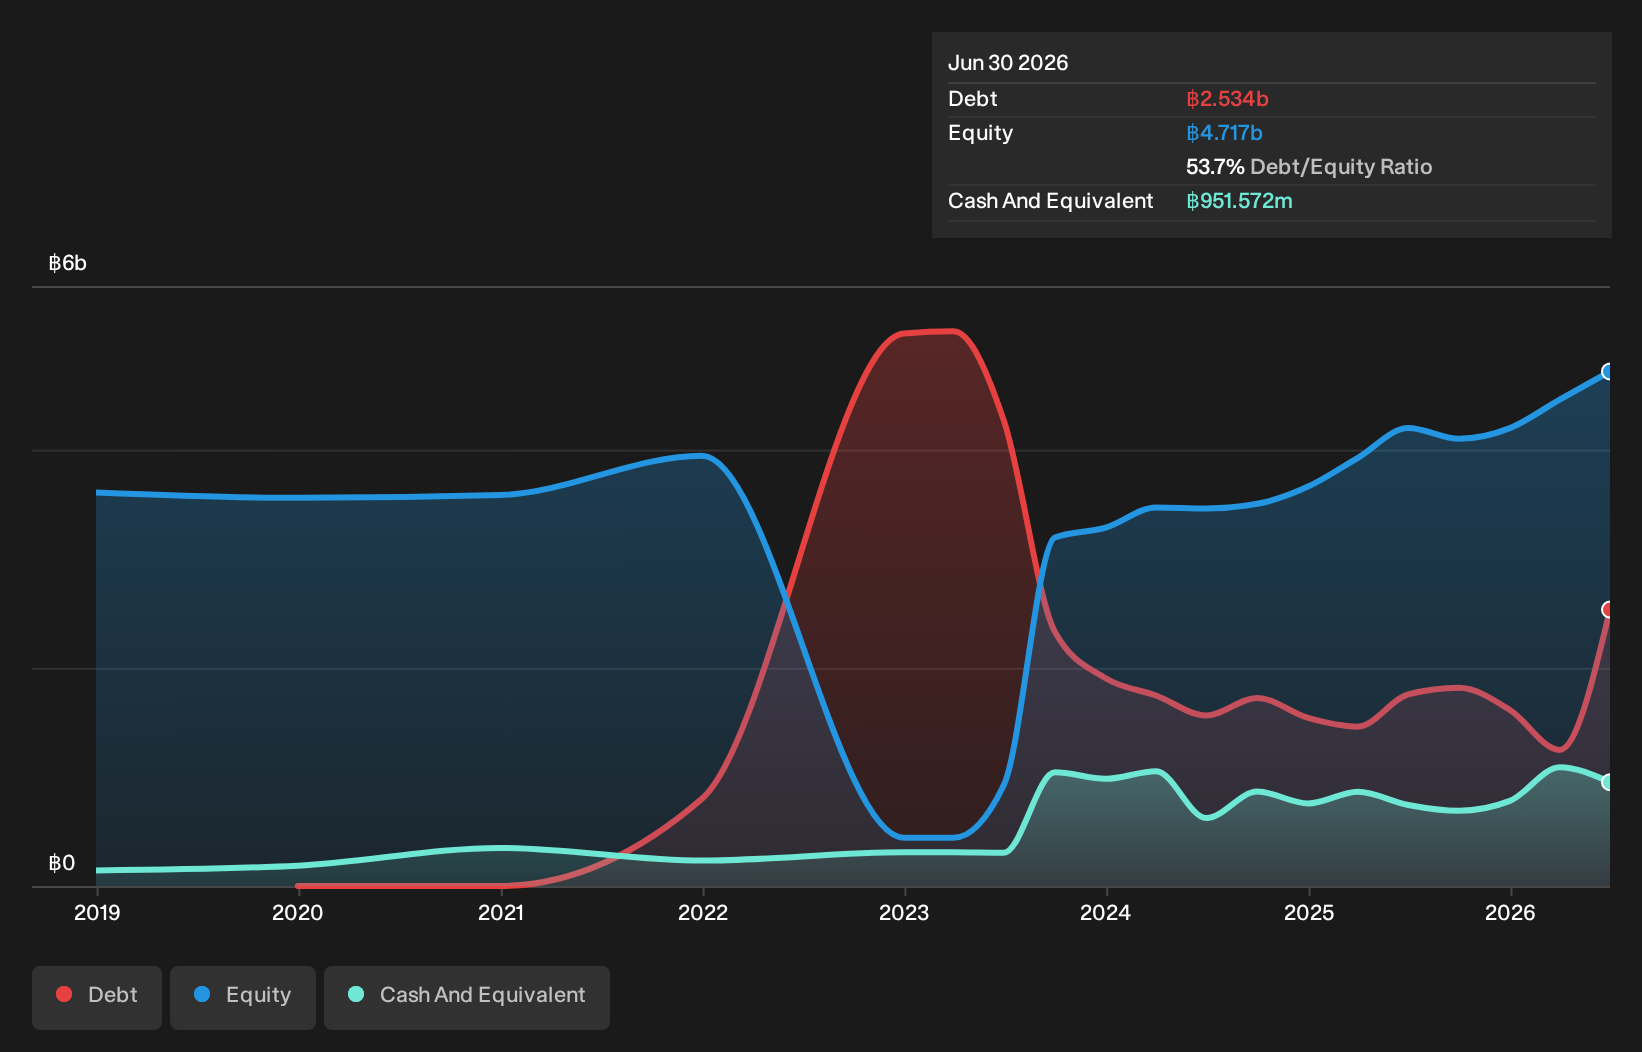
P.S.P. Specialties, a promising player in the chemicals sector, has shown robust performance with earnings growth of 38.8% over the past year, outpacing the industry average of 31.6%. The company's net debt to equity ratio stands at a satisfactory 33.5%, indicating prudent financial management, while its interest payments are comfortably covered by EBIT at 20 times over. Despite recent volatility in share price, P.S.P.'s stock trades at an attractive value—47.1% below estimated fair value—suggesting potential upside for investors seeking undervalued opportunities in Asia's dynamic market landscape.
- Unlock comprehensive insights into our analysis of P.S.P. Specialties stock in this health report.
Explore historical data to track P.S.P. Specialties' performance over time in our Past section.
Shin Nippon Air Technologies (TSE:1952)
Simply Wall St Value Rating: ★★★★★★
Overview: Shin Nippon Air Technologies Co., Ltd. offers engineering systems for air, water, heat, and other areas of air conditioning, electrical, and sanitary facilities both in Japan and internationally with a market cap of approximately ¥142.79 billion.
Operations: The company generates revenue primarily from facility construction work, amounting to ¥159.77 billion.
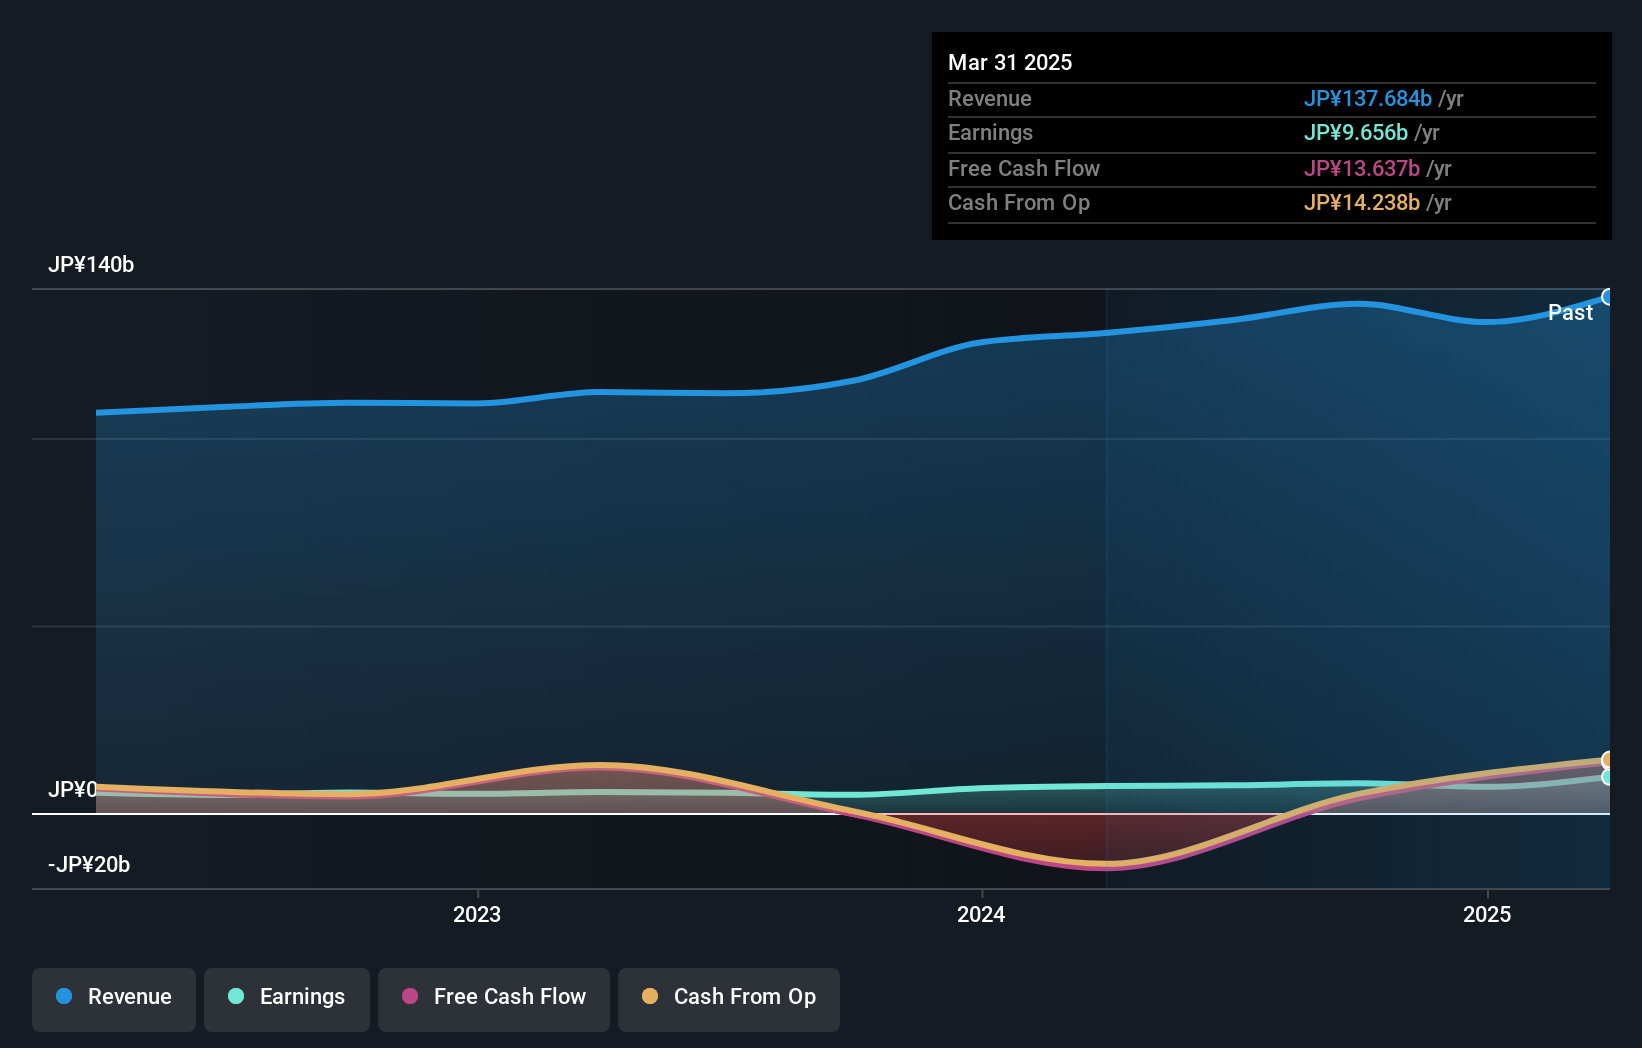
Shin Nippon Air Technologies, a promising player in the building industry, has shown impressive growth with earnings climbing 26.4% over the past year, outpacing its sector's 17.5%. The company reported net income of ¥2.74 billion for Q1 2026, up from ¥1.58 billion a year earlier, reflecting robust performance despite market volatility. Its debt to equity ratio improved significantly from 7.5% to 3% over five years, indicating prudent financial management. Recent dividend guidance suggests an increase to ¥60 per share for mid-year but a decrease for year-end compared to last year's payout of ¥70 per share.
- Take a closer look at Shin Nippon Air Technologies' potential here in our health report.
Learn about Shin Nippon Air Technologies' historical performance.
Taking Advantage
- Investigate our full lineup of 121 Asian Undiscovered Gems With Strong Fundamentals right here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com