


Bright Horizons Family Solutions (BFAM) Joins Workday Wellness, Is The Stock Still Undervalued?
Workday Wellness partnership puts Bright Horizons in front of more employers
Bright Horizons Family Solutions (BFAM) was named a Workday Wellness partner on 31 August 2026, tying its family care and education benefits directly into employers’ existing Workday Human Capital Management systems.
This integration lets workers discover, enroll in, and use Bright Horizons programs inside the same platform they already use for pay, time off, and benefits. For investors, the interest sits in how this distribution channel could affect adoption of the firm’s childcare, back-up care, and education support offerings over time.
Bright Horizons Family Solutions shares trade at US$65.12 after a 1-day share price gain of 1.32%. However, the 7-day and 30-day share price returns declined 7.30% and 8.68% respectively, pointing to fading short-term momentum. This comes despite a modest 90-day rise of 2.05% and a much weaker 1-year total shareholder return that fell 42.54%.
Compare how Bright Horizons Family Solutions stacks up against other workforce support providers by scanning our curated list of solid balance sheet and fundamentals (23 results) that investors are watching after this Workday Wellness partnership news.
Bright Horizons Family Solutions now trades well below its recent 1-year level, even after the Workday Wellness catalyst. Is that enough to justify buying today, or does the risk profile argue for waiting on a cheaper entry point as the valuation picture comes into focus?
Most Popular Narrative: 28.5% Undervalued
The most followed narrative on Bright Horizons Family Solutions pegs fair value at $91.11, well above the recent $65.12 close, and ties that gap to specific growth, margin, and valuation assumptions that investors can test for themselves.
The expansion of employer-sponsored childcare and growing demand from large corporate clients such as McKesson and Centene point to a resilient pipeline for Bright Horizons, as employers increasingly view high-quality childcare as a critical employee benefit to attract and retain talent. This is likely to drive recurring B2B revenue growth and improve customer retention, positively impacting the company's top-line and earnings visibility.
Want to see what sits behind that confidence? The narrative ties together projected revenue gains, higher profit margins, and a lower future earnings multiple to justify that higher fair value. The exact mix of those three levers, and how they intersect with buybacks and index inclusion, is what really moves the model.
Result: Fair Value of $91.11 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Bright Horizons Family Solutions narrative frays quickly if enrollment stays subdued in underperforming centers or wage pressures squeeze margins faster than pricing can adjust.
Find out about the key risks to this Bright Horizons Family Solutions narrative.
Another View: Bright Horizons Family Solutions On Earnings Multiples
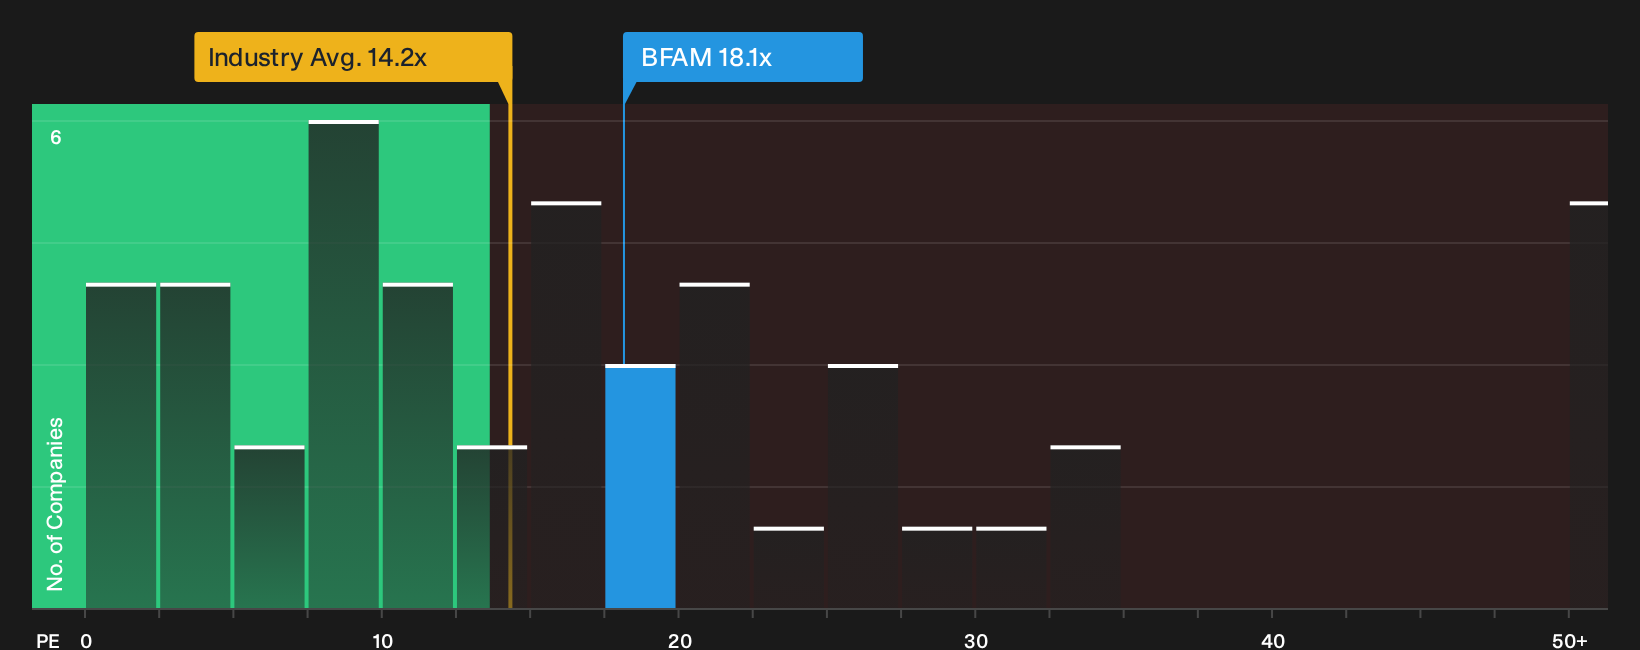
There is a catch. Bright Horizons Family Solutions trades on a P/E of 18.1x, which is higher than both the US Consumer Services industry on 14.2x and its peer group near 17.2x. The fair ratio sits at 23x, so the gap may represent a safety margin or indicate that the market remains cautious.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Bright Horizons Family Solutions often create urgency, so check the underlying data soon and weigh both sides through the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Bright Horizons Family Solutions?
If Bright Horizons Family Solutions has you thinking harder about where to put fresh capital, this is the moment to widen your watchlist before the next move.
- Spot potential mispricing early by scanning a curated pool of 32 high quality undervalued stocks that pair stronger fundamentals with what may be more modest expectations.
- Prioritise sleep-at-night holdings by checking a focused set of 11 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Get ahead of the crowd by reviewing a targeted collection of 15 high quality undiscovered gems that many portfolios may not hold yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com