


Will Earnings Guidance Change Tapestry Shares Narrative
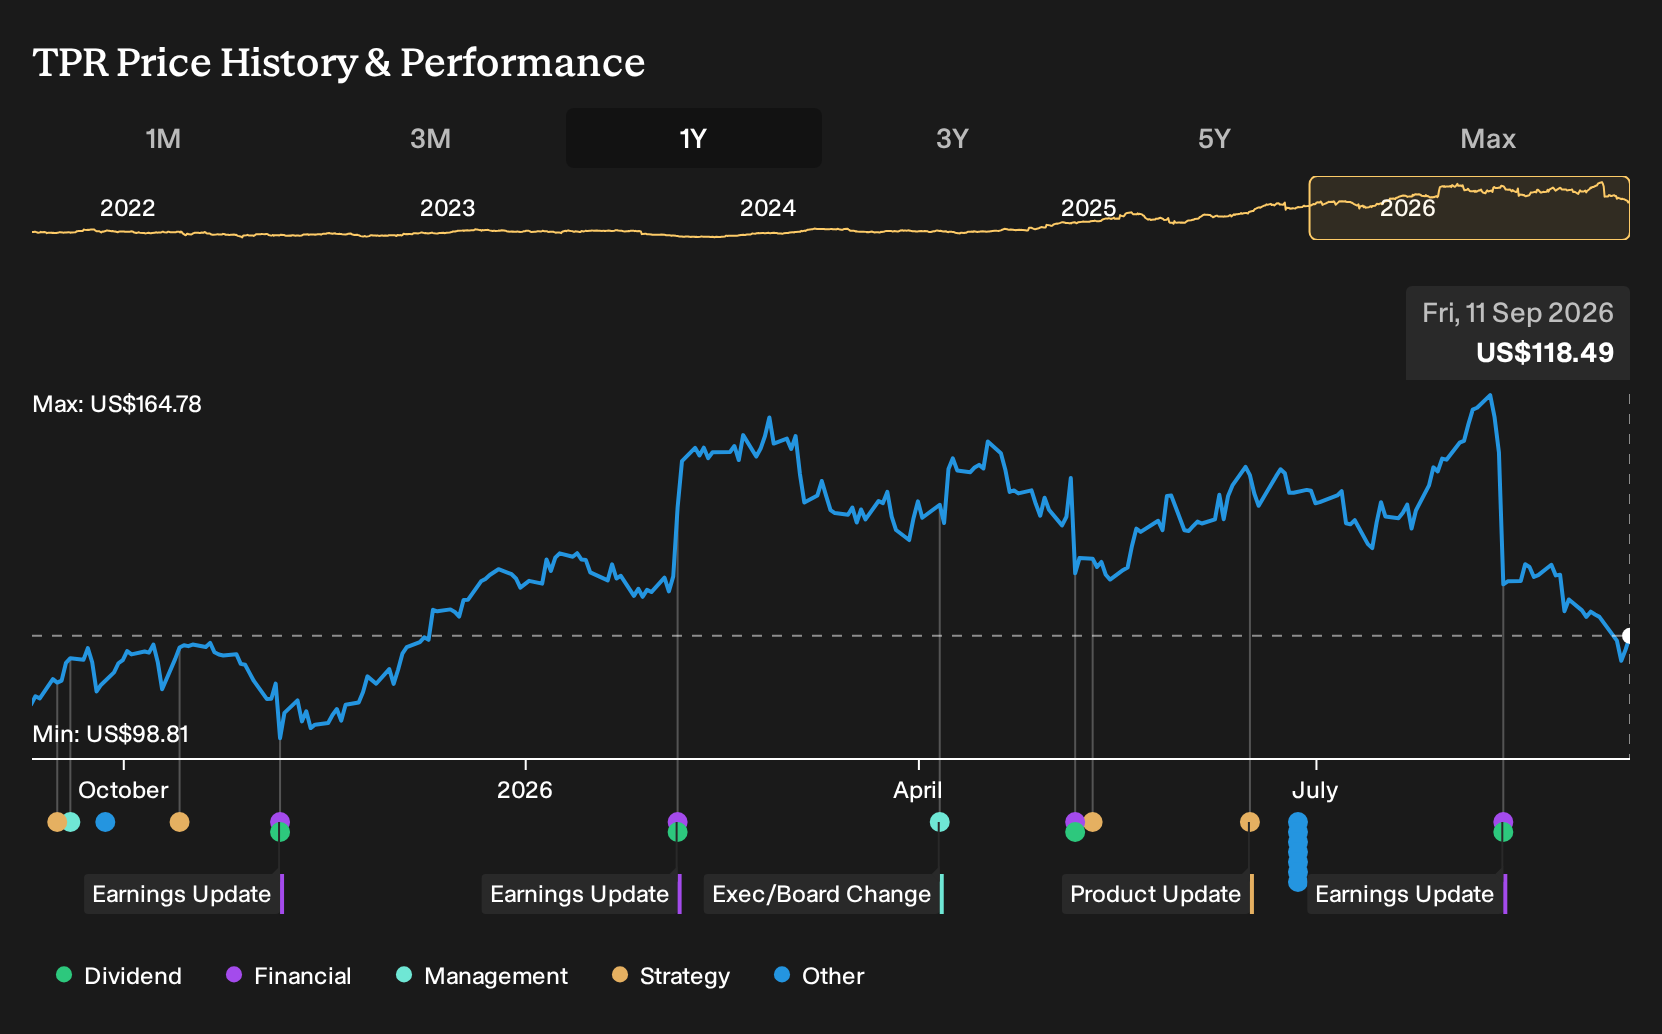
- Tapestry reported strong fiscal 2026 results driven by Coach, while management guided to mid single digit revenue growth for fiscal 2027 and projected a high single digit advance for Coach alongside a high single digit revenue decline at Kate Spade.
- The contrast between Coach’s momentum and Kate Spade’s expected contraction highlights how uneven brand performance may shape Tapestry’s portfolio mix and resource allocation decisions.
- Now the focus shifts to how Tapestry’s investment narrative incorporates strong Coach results alongside softer guidance for Kate Spade in fiscal 2027.
Compare how Tapestry’s mixed brand picture stacks up against other fashion groups by scanning our handpicked 32 high quality undervalued stocks that may be pricing in similar portfolio twists.
Tapestry Investment Narrative Recap
To own Tapestry, you need to believe Coach can keep carrying the group while Kate Spade stabilises. The latest quarter supports that idea on the Coach side, with strong fiscal 2026 results. Management is still talking about mid single digit revenue growth for fiscal 2027. The key near term catalyst remains execution on Coach product, pricing, and customer engagement, especially with younger shoppers.
The biggest short term risk sits with Kate Spade and tariffs. Management is already flagging a high single digit revenue decline for Kate Spade, on top of an earlier US$850m impairment that pointed to brand weakness and tariff sensitivity. If that drag widens, it could offset Coach’s strength and keep margins under pressure.
The most relevant recent update is the fiscal 2027 outlook that pairs high single digit growth at Coach with a high single digit decline at Kate Spade. That split gives you a clear roadmap for where management expects momentum to come from and where heavy lifting is still required. It also sharpens the focus on how much of group earnings rely on one label.
For catalysts, Coach’s growth, international expansion and digital investments sit on one side. On the other side is the risk that Kate Spade’s turnaround takes longer, tariffs keep biting and the prior impairment signals ongoing margin strain. Your call as an investor is whether Coach’s customer traction and Tapestry’s omnichannel push can offset that drag enough to support the broader story.
Tapestry’s current analyst narrative points to forecast revenue of US$9.1b and earnings of US$1.6b by 2029, which implies revenue growing at 5.0% per year and an earnings increase of about US$937m from US$662.8m today.
Uncover why Tapestry's fair value indicates a 41% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One optimistic thread in the alternate Tapestry story is how quickly bullish analysts think earnings could scale if Coach’s younger customers keep coming back. Before this latest drop, the most upbeat forecasts were already pointing to US$9.8b in revenue and US$2.1b in earnings by 2029. You now get to decide whether this news pushes those expectations higher, lower, or somewhere in between, and exploring several viewpoints can help you test your own view.
Explore 3 other Tapestry fair value estimates, including one that suggests as much as 62% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tapestry research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tapestry. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tapestry's overall financial health at a glance.
Looking For More Ideas Beyond Tapestry?
Once you have a handle on Tapestry, it can help to put the story in context by scanning other businesses with different risk and return profiles using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your portfolio, check out 6 dividend fortresses that focus on payout strength and yield resilience.
- For steadier sleep-at-night potential, review 11 resilient stocks with low risk scores that score well on balance sheet strength and risk factors.
- If you prefer to search off the beaten path, work through 15 high quality undiscovered gems that combine quality fundamentals with lower investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com