


CTS (CTS) Could Be 12% Undervalued As Its 2026 Rally Tests Fair Value
CTS (CTS) has drawn fresh attention after recent share moves, with the price up 2.8% on the day and still ahead 31.9% year to date. Investors are reassessing what that run implies.
The latest move leaves CTS with a 1-day share price return of 2.75% and a year to date share price gain of 31.93%, while total shareholder return over five years sits at 83.62%. This points to momentum that has cooled in recent months but remains firmly positive over a longer horizon.
Scan beyond CTS and size up other hand picked opportunities with 32 high quality undervalued stocks, which are moving on solid fundamentals and potential valuation support.
CTS has run hard this year, yet still trades below some valuation markers. Is most of the easy upside already priced in, or do the current numbers still leave meaningful room ahead?
Most Popular Narrative: 12.3% Undervalued
CTS closed at $57.85 against a narrative fair value of $66, which frames the recent share run as still leaving a valuation gap to interrogate.
The company's continued diversification into high-growth end markets such as medical (with particular momentum in therapeutic and portable ultrasound applications) and industrial (with new wins in EV charging, automation, and connectivity solutions) positions CTS to benefit from the accelerating adoption of smart, connected, and electrified technologies, supporting future revenue growth and an enhanced margin mix.
Want to see why this CTS story leans on expanding margins, gradual top line gains, and a richer earnings multiple tied to future mix shift? The fair value view rests on a specific blend of revenue growth, profit improvement, and capital allocation that is not obvious from the current share price chart.
Result: Fair Value of $66 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, if transportation demand stays soft or geopolitical and tariff pressures intensify, the bullish CTS margin and revenue story could quickly look more fragile.
Find out about the key risks to this CTS narrative.
Another View on CTS Valuation
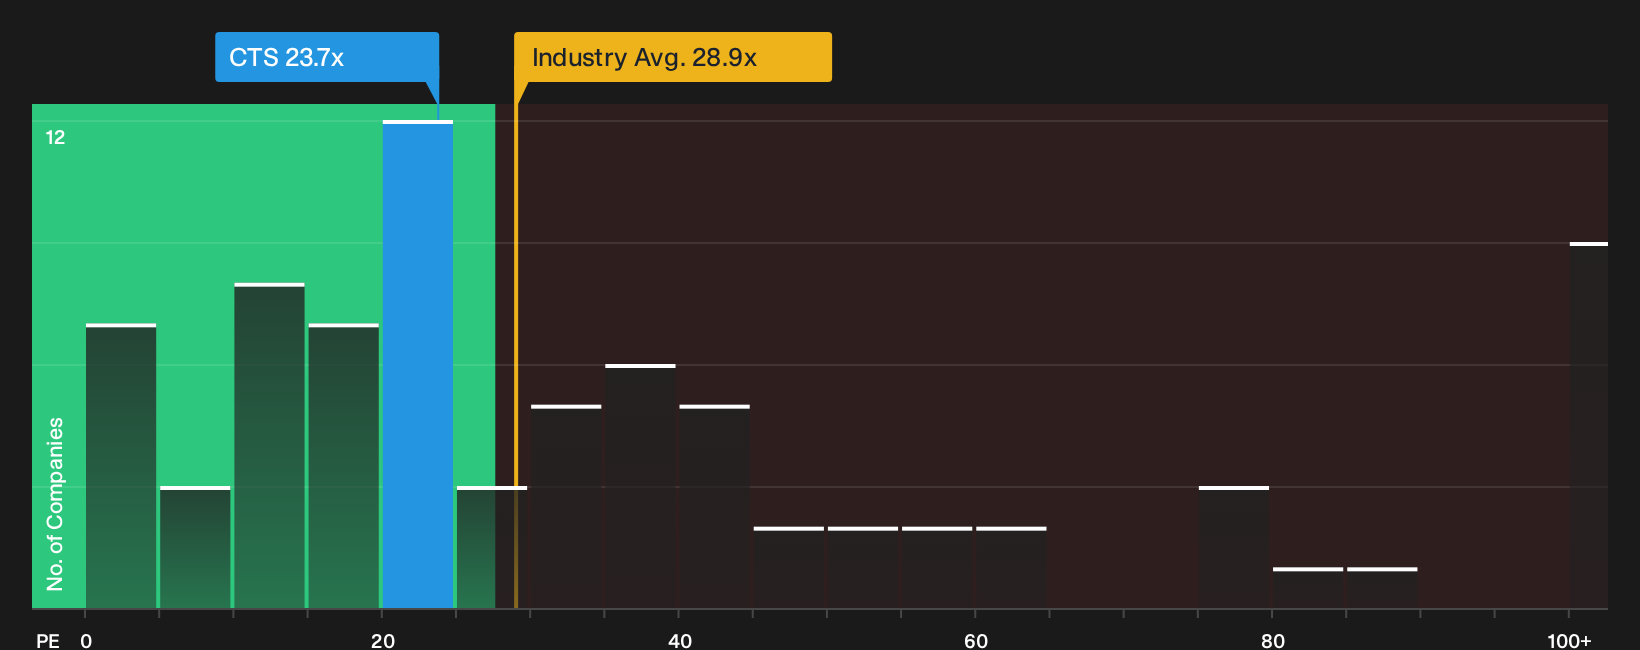
The first narrative leans on fair value of $66. A different lens uses the P/E ratio. CTS trades on 23.7x earnings versus a fair ratio of 22.4x, and peers on 58.8x with the broader US Electronic industry at 28.9x. That mix hints at some valuation risk, not just opportunity, if sentiment cools.
For a closer look at how this earnings multiple might shift over time and what similar companies are priced for, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the CTS setup feel optimistic or stretched to you right now? Take a moment to compare that initial reaction with the underlying data and form your own stance by checking its 4 key rewards
Looking for more CTS investment ideas?
If CTS has you thinking harder about where you put your next dollar, do not stop at a single ticker. Broader idea hunting can sharpen your edge.
- Target value opportunities that pair quality with attractive pricing by scanning the 32 high quality undervalued stocks before sentiment shifts away.
- Build a steadier income stream by reviewing companies in the 6 dividend fortresses that focus on sizeable yields and consistent cash returns.
- Strengthen your downside protection by checking the 11 resilient stocks with low risk scores that emphasise resilient balance sheets and calmer volatility profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com