


How Higher Earnings Estimates Will Impact ITT Stock Investors
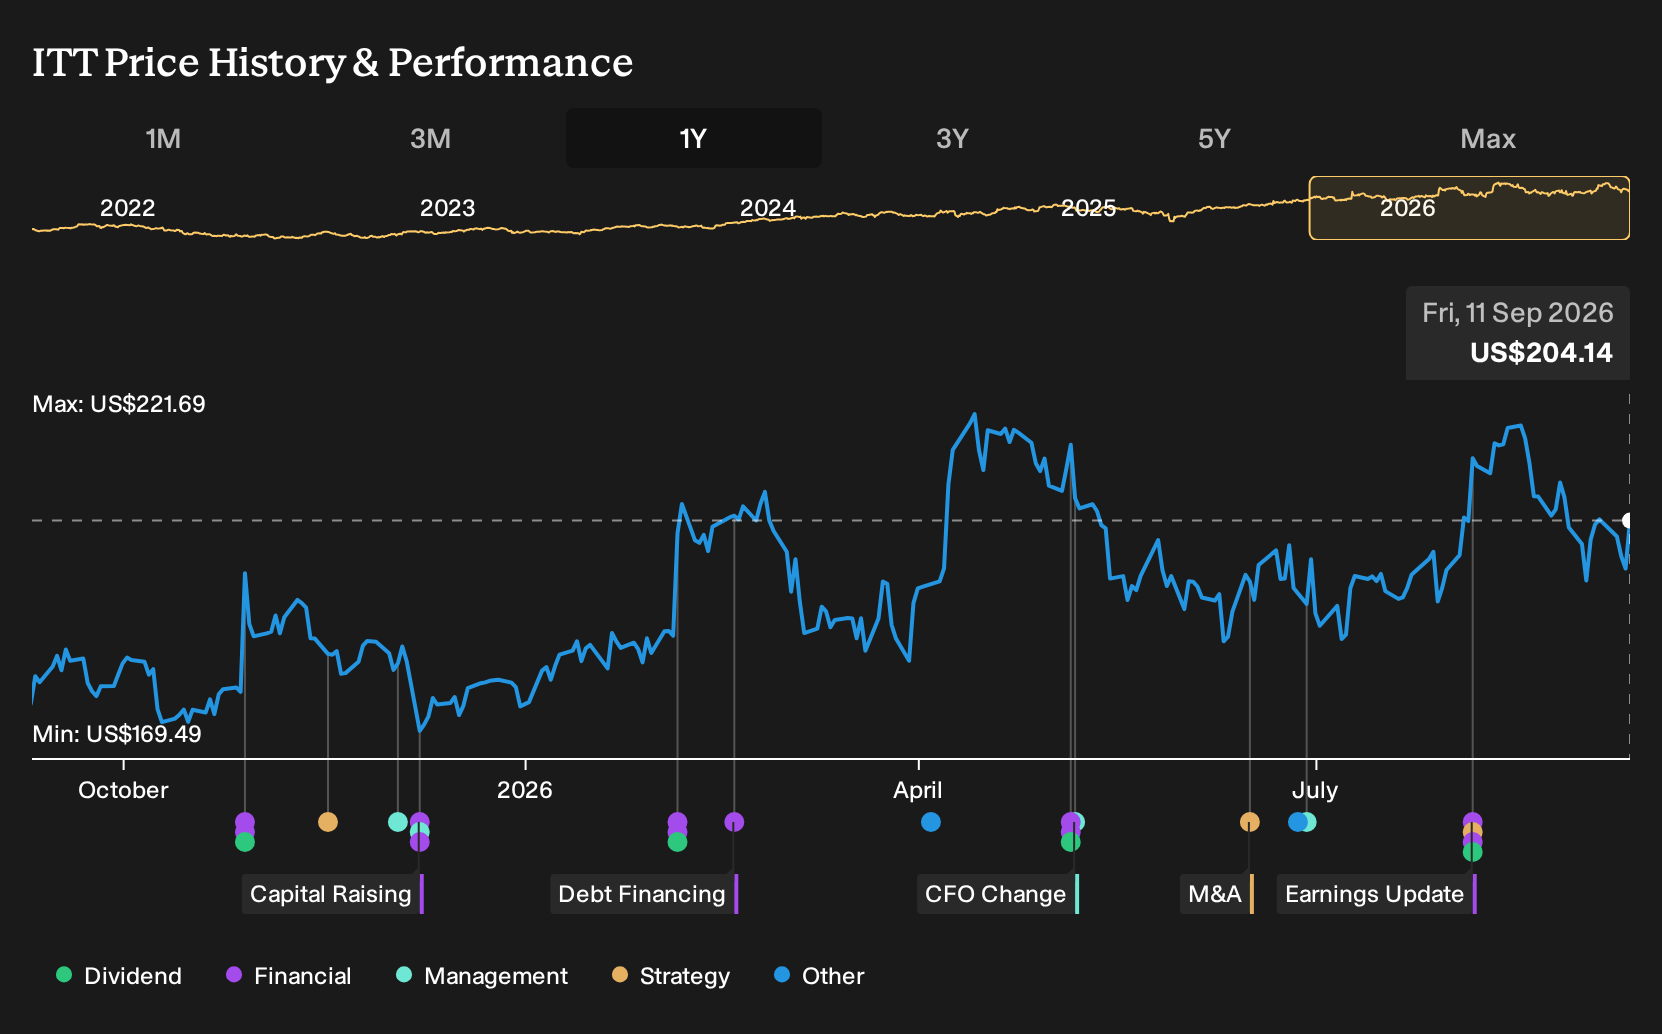
- ITT has seen its full year earnings estimate move 4.4% higher over the past quarter, alongside sector-beating performance relative to broader conglomerates.
- The combination of stronger projected earnings and clear sector outperformance suggests investors are focusing on ITT’s current demand and execution rather than short term sentiment swings.
- We will now see how ITT's investment narrative could be shaped by higher full year earnings estimates in the context of sector outperformance.
Scan how ITT’s recent sector-beating run compares with other potential outperformers by reviewing the hand picked 32 high quality undervalued stocks now shaping investor watchlists.
ITT Investment Narrative Recap
To own ITT, you need to be comfortable with an industrial business that leans on large projects in energy, water and transportation, along with a growing mix of acquired platforms. The key short term upside rests on converting its sizable backlog into revenue without slippage, while keeping pricing and cost discipline tight as input costs and mix move around.
The biggest swing factor right now is execution on project based work, which already carries known risks around delays or cancellations if conditions soften. Recent sector outperformance and higher full year earnings estimates reflect more confidence in current operations, but they do not remove exposure to margin pressure or supply chain disruptions.
Recent commentary around ITT has focused on the higher full year earnings outlook that analysts now model, with the consensus moving 4.4% higher over the past quarter. That upgrade connects directly to the same themes investors are watching in the near term: stronger order books in energy and industrial markets, and management’s ability to hold pricing while integrating newer acquisitions.
Even without a fresh company announcement tied to this move, the revised earnings view feeds into the existing catalyst list for ITT: backlog conversion, aftermarket expansion and acquisition performance at businesses like Svanehøj and kSARIA. The risk side of that equation is still present, especially the heavier tilt to project revenue and the possibility that margin gains prove harder to maintain if pricing power or volumes soften.
ITT's narrative projects US$6.5b revenue and US$898.9m earnings by 2029. This assumes 11.2% yearly revenue growth and an earnings increase of about US$477.3m from US$421.6m today.
Uncover why ITT's fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One significant factor that the most optimistic analysts focus on is the planned SPX FLOW acquisition. Before this earnings upgrade, that group was already modeling around US$6.8b of 2029 revenue and US$979.6m of earnings for ITT, compared with about US$6.5b and US$898.9m in the broader consensus. You can use this news to evaluate which acquisition scenario seems more realistic to you.
Explore another ITT fair value estimate, including one that suggests there could be as much as 23% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ITT research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ITT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ITT's overall financial health at a glance.
Looking for more investment ideas beyond ITT?
If ITT has sharpened your focus on quality and execution, you can use that same lens to scan a wider opportunity set with the Simply Wall St Screener and line up a few more companies for deeper research.
- For investors who want resilient balance sheets and steady fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results) that aims to keep financial risk in check.
- If capital preservation matters as much as upside potential to you, filter for companies with steadier profiles using our 11 resilient stocks with low risk scores tailored to lower risk scores.
- When you want to widen the search and potentially identify promising opportunities early, scan the 15 high quality undiscovered gems and see which under-the-radar stocks deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com