


How Earnings Upgrades Will Impact Allstate Stock Investors
- Allstate recently received an upgrade to a Zacks Rank #1 rating after analysts revised earnings forecasts upward, reflecting a more constructive view of its core insurance operations and profitability profile.
- The shift in earnings expectations highlights how Allstate's underlying business mix, cost discipline, and product performance are shaping analyst views on its long term earnings power.
- We will now look at how Allstate's investment narrative is influenced by this earnings focused upgrade and shifting analyst expectations.
Scan beyond Allstate and see how other insurers are being repriced on earnings momentum with a curated set of 32 high quality undervalued stocks.
Allstate Investment Narrative Recap
To own Allstate, you need to be comfortable with a property and casualty insurer that leans heavily on auto and homeowners lines while trying to push more digital, data driven products. The big near term swing factor is whether underwriting results and catastrophe losses stay within the ranges its current pricing and reinsurance can support.
The largest operational risk right now is still catastrophe volatility and regulatory rate friction, especially in states where approval cycles are slow. The Zacks Rank upgrade itself does not change those fundamentals. It mainly spotlights that recent earnings trends have been stronger than many expected, which could support sentiment around the existing business plan.
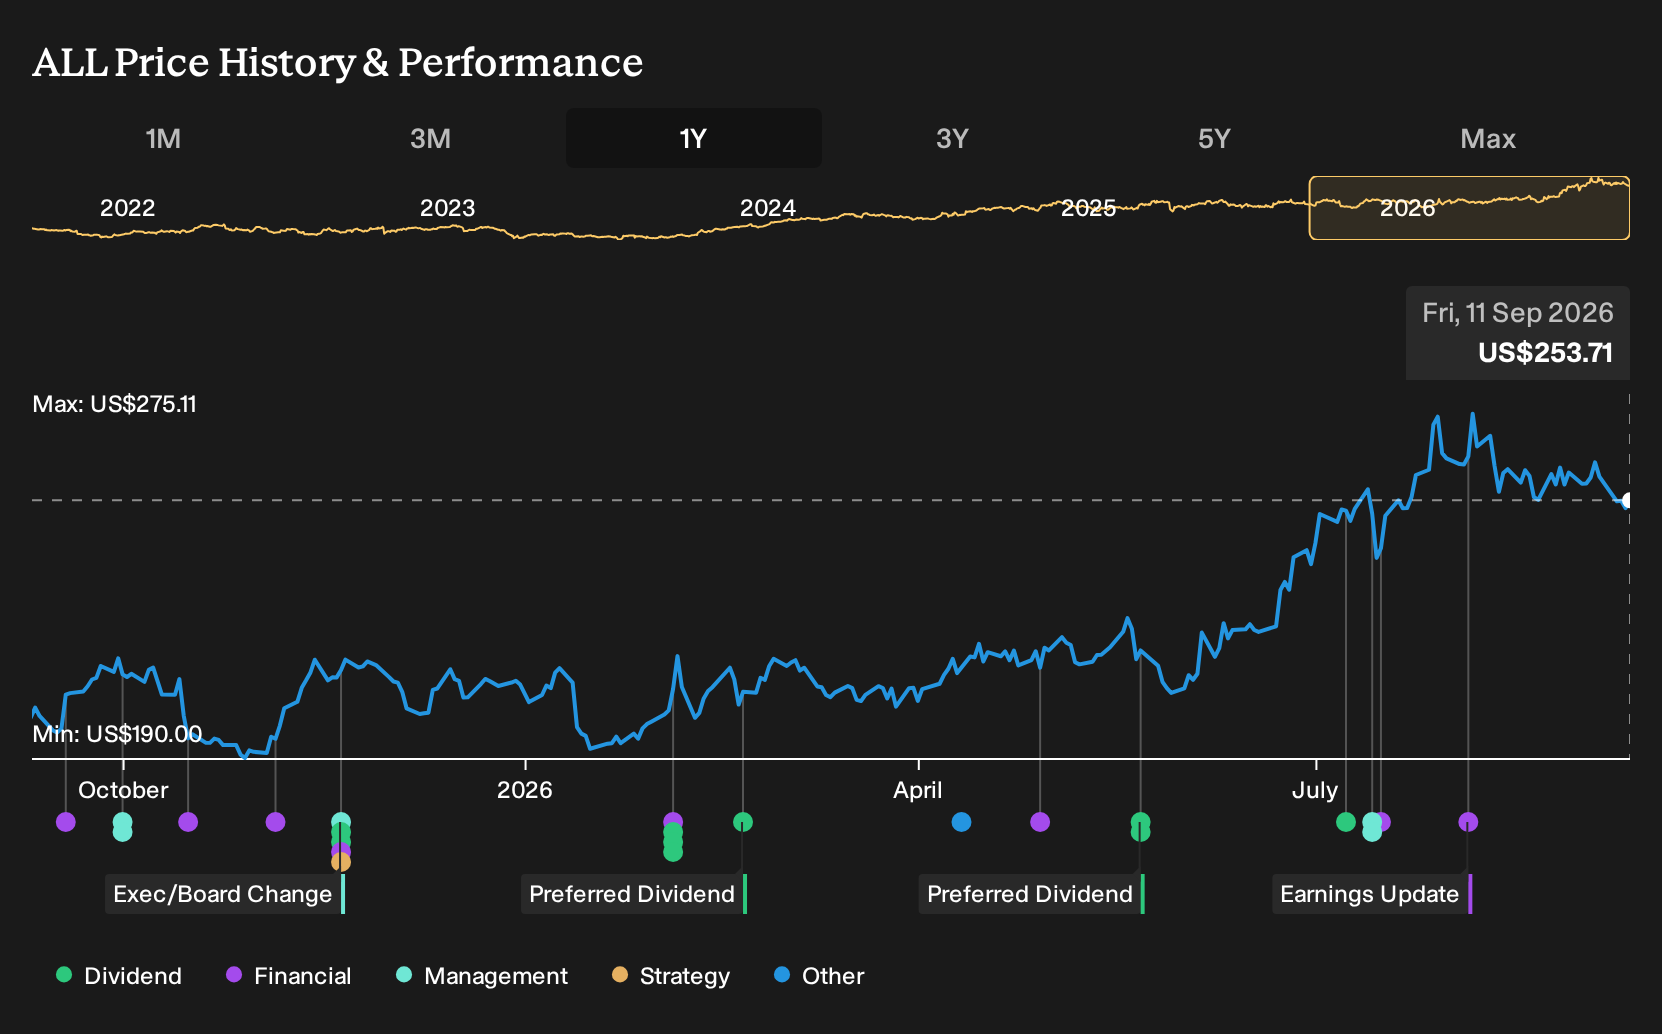
The most relevant recent development tied to this upgrade is the shift in earnings expectations that underpins the Zacks Rank move. Analysts have raised their forecasts, and Allstate now carries a Zacks Rank #1 rating. That directly relates to how the market is reassessing the durability of its current margin profile.
For you as a shareholder, the key consideration is how this improving outlook intersects with known risks. Earnings are still forecast to decline on average over the next few years, so execution on pricing, retention and catastrophe management remains critical. The rating change highlights Allstate’s recent profit rebound but does not remove the core operational challenges.
Allstate’s current analyst narrative points to revenues of $76.5b and earnings of $3.9b by 2029, based on 2.9% yearly revenue growth and an earnings decline of $9.3b from $13.2b today.
Uncover why Allstate's fair value indicates an 8% potential upside to its current price before this valuation gap closes.
Exploring Other Perspectives
For a different angle on Allstate, focus on catastrophe risk. The most optimistic analysts were already assuming around $81.4b of revenue and $5.0b of earnings by 2029 before this Zacks Rank news, which is far ahead of the $76.5b and $3.9b baseline. Those forecasts could shift as new information comes through, so treat this upgrade as a prompt to compare several narratives, rather than accept any single view as complete.
Explore 4 other Allstate fair value estimates, including one that suggests as much as 199% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Allstate research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Allstate. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allstate's overall financial health at a glance.
Looking for more Allstate style investment ideas?
If the Allstate story has you thinking about what else might be hiding in plain sight, a broader sweep across the market can help you pressure test your approach and uncover new opportunities that fit your risk and income preferences.
- For investors who want income with resilience, start with companies that look built to support payouts over time through a 6 dividend fortresses.
- If capital preservation ranks high on your list, filter for companies with steadier profiles using a 11 resilient stocks with low risk scores that keeps the focus on durability first.
- To cast a wider net for underfollowed opportunities with solid fundamentals, scan a 15 high quality undiscovered gems that surfaces smaller businesses many investors may have overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com