


Wonder Deal, $240M Cash, and 31% Short Interest. A Short Squeeze Could Be Brewing in Serve Robotics Stock.
Serve Robotics (SERV) shares have tumbled roughly 20% since the autonomous delivery company lowered its 2026 revenue guidance on Aug. 6. The cut came despite quarterly revenue surging 404% year-over-year (YOY). Serve Robotics also said it may not renew its foundational partnership with Uber (UBER) after it expires in early 2027. The development follows Serve's first decline in Uber Eats delivery volume in 17 consecutive quarters. However, Serve has $240 million in cash and is intentionally expanding into DoorDash (DASH), healthcare robotics, and advertising. The debate now is whether the reset reflects deeper trouble or a strategic effort to diversify beyond a weakening partnership.
Investors should also look closely at the short interest number when it comes to SERV stock. Serve Robotics has a short percentage of float of 31.3%. That's an extremely high number for any company but also brings with it an opportunity — namely, a potential short squeeze. For that to happen, though, there needs to be some retail interest in SERV stock.
So far, there has hardly been any newsworthy development to excite traders. On Aug. 17, the firm did sign a partnership with Wonder for autonomous delivery beginning in Chicago, Illinois, Los Angeles, California, and Alexandria, Virginia. While that is a positive development, it hardly generated much excitement. That is a fate that is expected to haunt SERV stock at least for the near term, making it hard for traders to squeeze out any sizable returns.
About Serve Robotics Stock
Based in San Carlos, California, Serve Robotics is a robotics company that develops and operates low-emission robots. The company’s robots are designed to deliver food to people in commercial and public spaces, with the core business focused on self-driving delivery robots that can operate without a human driver.
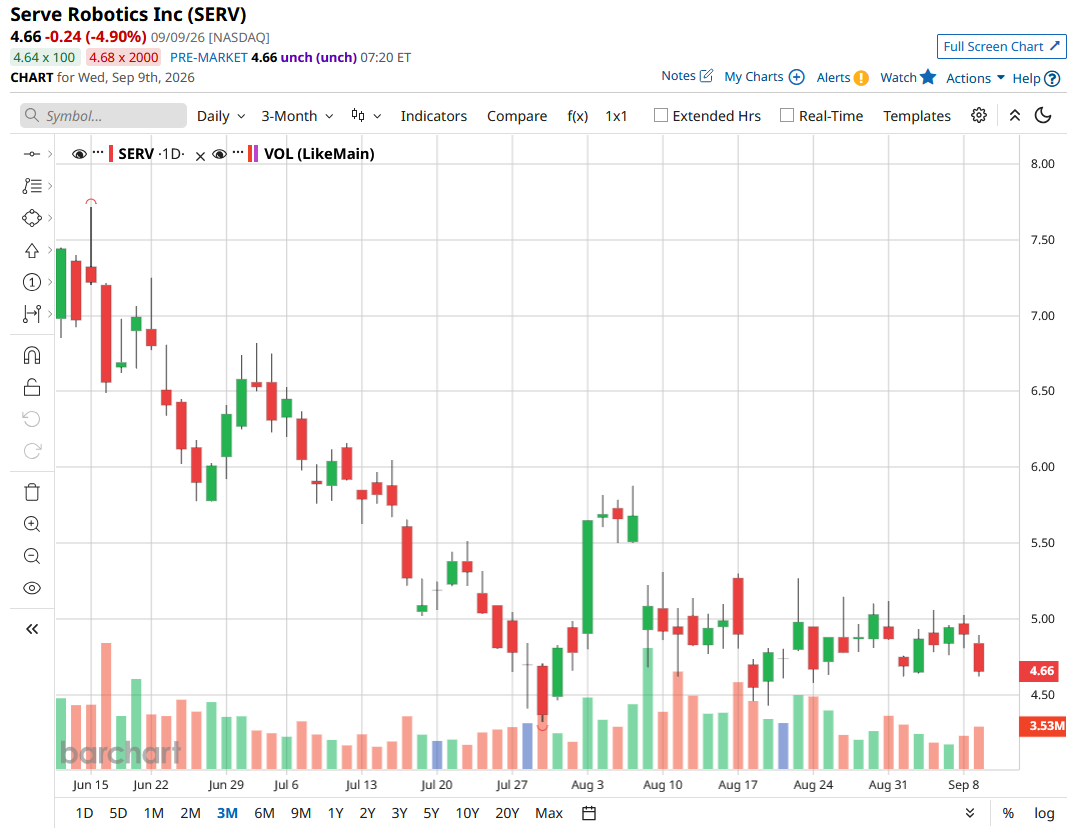
Serve Robotics has had a difficult year, with shares falling roughly 61% for the past 52 weeks. The decline reflects continued losses, high short interest, and broader investor concerns about unprofitable micro-cap robotics companies. SERV stock has stayed in a persistent downtrend since early 2026 with few signs of a meaningful recovery. In comparison, the Global X Robotics and Artificial Intelligence ETF (BOTZ) has performed much better, posting a return of about 3% for the past year but a decline of more than 2% year-to-date (YTD).
Poor Earnings Report Triggers a Selloff
Serve Robotics reported second-quarter revenue of $3.2 million, representing 404% year-over-year (YOY) growth, although that figure came in below the consensus estimate of about $3.5 million. Meanwhile, the company's non-GAAP loss of $0.59 per share was in line with market expectations.
Notably, Serve cut its full-year 2026 revenue guidance to $9 million to $10 million from $26 million. The guidance reduction reflects weaker Uber Eats delivery volumes and the removal of previously expected second-half demand. According to CEO Ali Kashani, the change resulted from disagreements with Uber over merchant integration and fleet coordination rather than weaker customer demand. The company does not currently plan to renew its Uber agreement in early 2027 without improvements to the operating model. Management also lowered operating expenses guidance to $140 million to $150 million from $160 million to $170 million.
Why Serve’s Selloff Could Be Overdone
The sharp revenue guidance cut does not necessarily mean Serve Robotics is running out of financial flexibility. The company ended the quarter with $240 million in cash and lower operating expenses, giving it several years of runway to pursue its diversification strategy without needing to raise capital under pressure.
Management said the Uber-related shortfall was caused by operational issues rather than weaker demand. Meanwhile, Serve is building other growth channels through advertising and DoorDash. Advertising now contributes nearly 50% of food delivery revenue. The company is also expanding into healthcare robotics following its acquisition of Diligent Robotics. With recurring revenue now making up more than half of total revenue, the selloff may reflect justified short-term execution risks rather than a long-term story.
What Are Analysts Saying About Serve Robotics?
Last month, Freedom Broker upgraded Serve Robotics from “Hold” to “Buy” while cutting its price target on SERV stock from $18 to $8. The firm cited the company's strong balance sheet, a lower valuation, and early growth signs. The $8 price target is based on an 8 times sales multiple applied to its 2028 revenue forecast.
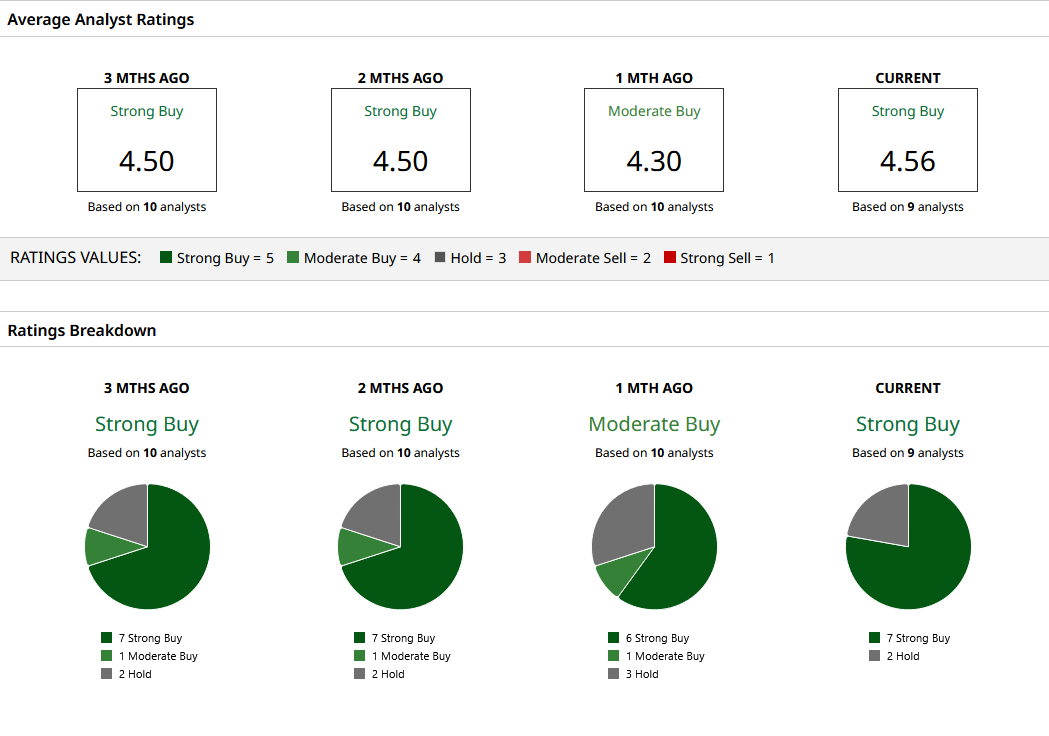
Based on nine Wall Street analysts covering the stock, Serve Robotics carries a consensus “Strong Buy” rating overall. The mean price target of $12.14 suggests potential upside of approximately 171% from current levels. Moreover, the highest price target of $22 is attractive for investors, as it suggests SERV stock could climb as much as 390% from here.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.