


NOV (NOV) Dividend Raises Fresh Questions About Valuation
NOV dividend move puts payout sustainability in focus
NOV Inc (NOV) has declared a total dividend of $0.09 per share, continuing a track record of payments that stretches back to 2009. The current payout ratio of 1.62 is drawing fresh attention from income focused investors.
NOV’s latest dividend decision lands after a strong stretch for investors, with a year to date share price return of 28.58% and a 1 year total shareholder return of 67.41%. Short term share price momentum has cooled slightly, while longer term performance still reflects increased confidence in the business and its valuation profile.
Compare NOV’s payout profile with other income candidates by scanning our hand picked 6 dividend fortresses that are poised to offer yield with sturdier financial footing.
NOV’s rebound and rich recent returns set a high bar from here. Does the current valuation still leave enough upside to justify the dividend risk investors are taking on?
Most Popular NOV Valuation Narrative: 4.4% Undervalued
NOV last closed at $21.10, against a widely followed fair value estimate of $22.08 that is built on detailed earnings and margin forecasts.
Anticipated acceleration in offshore oil and gas activity beginning in 2026, with deepwater projects increasingly becoming the incremental source of global production, is expected to drive significant demand for NOV's high-spec drilling and production technologies. This is expected to position the company for robust revenue and margin growth as project backlogs convert. The global rollout of unconventional resource development (outside North America) requires large-scale infrastructure and advanced drilling equipment, providing NOV with expanded market opportunities as international E&Ps replicate shale success. This is likely to lead to higher equipment and aftermarket sales.
Curious what sits behind that offshore and unconventional story for NOV. The fair value hinges on paired revenue and earnings expansion, plus a lower future earnings multiple. The narrative leans on improving profitability and a specific discount rate, yet still treats the current share count path as a key swing factor.
Result: Fair Value of $22.08 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the NOV story can unravel if tariffs, inflation and trade policy keep pressuring margins, or if offshore and Middle East orders fall short of expectations.
Find out about the key risks to this NOV narrative.
Another view on NOV’s valuation using earnings multiples
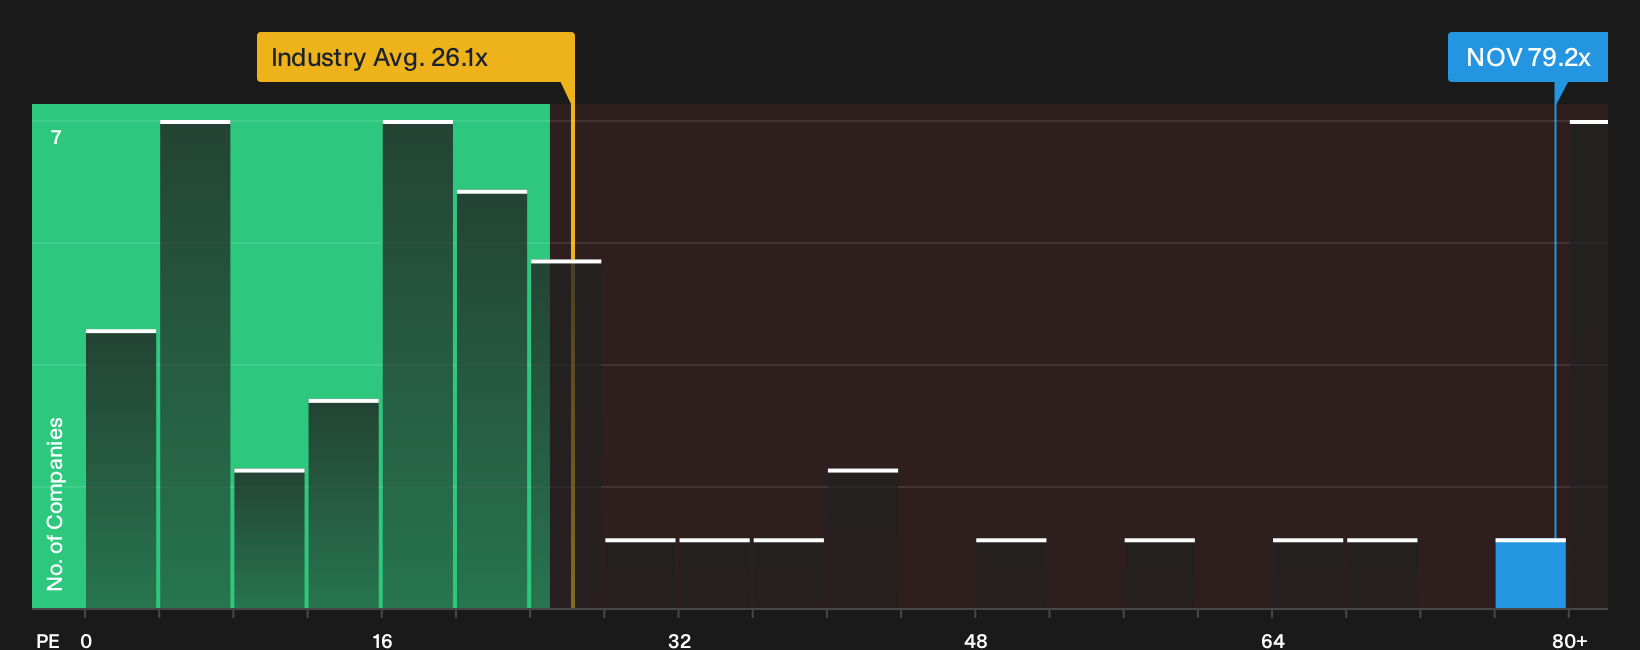
The earlier fair value story casts NOV as 4.4% undervalued based on forecasts and discount rates. The earnings multiple view is less forgiving. NOV trades on a P/E of 79.2x, while the fair ratio is 28.2x and the US Energy Services group averages 26.1x. This highlights potential valuation risk if sentiment cools.
The stock also trades higher than its peer average P/E of 43.4x, which suggests investors are already paying a premium for execution and future profit growth. If those expectations soften, the share price could move closer to that fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around NOV’s valuation and dividend strength can leave you on the fence, so move quickly from headline impressions to your own evidence based view with the 2 key rewards and 3 important warning signs.
Hunting for more NOV-like investment ideas?
You do not need to stop with NOV. Broaden your watchlist now by using the Simply Wall St Screener to spot other opportunities that fit your income or value goals.
- Target resilient returns by focusing on companies that pair reasonable valuations with healthy finances using the 11 resilient stocks with low risk scores.
- Zero in on potential bargains where quality and pricing line up sensibly through the 32 high quality undervalued stocks.
- Strengthen your income toolkit by finding payout options backed by stronger fundamentals using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com