


What Is Drawing Attention To Helmerich & Payne (HP)?
Helmerich & Payne (HP) drew fresh attention after its recent share price performance, with the stock last closing at US$44.04 and recording mixed short term returns alongside stronger long term total return figures.
Recent trading has cooled slightly, with the share price slipping over the past week and month. However, Helmerich & Payne still carries a strong year-to-date share price return and a very strong 1-year total shareholder return, which points to earlier momentum now easing as investors reassess growth prospects and risk.
Scan how Helmerich & Payne stacks up against a hand picked group of energy peers by running the 32 high quality undervalued stocks alongside this latest share price move.
So is this recent cooling in Helmerich & Payne a signal that the underlying drilling business no longer matches earlier enthusiasm, or has sentiment simply swung further than the fundamentals justify, given how the valuation now looks?
Most Popular Narrative: 1.9% Overvalued
Helmerich & Payne's most followed valuation storyline pins fair value at $43.20, slightly below the latest close of $44.04, which leaves only a small premium for investors to weigh.
Global energy demand, particularly from emerging markets and the secular global trend toward greater onshore natural gas development, is supporting H&P's international growth pipeline, especially in the Middle East and South America, providing durable long-term utilization and revenue visibility. The company's growing international footprint, highlighted by the successful KCA integration and new tender opportunities in Saudi Arabia and Argentina, positions H&P to capture incremental market share and expand EBITDA as geopolitical instability and supply concerns reinforce demand for high-spec rigs.
Curious how that story translates into numbers? The narrative leans heavily on measured revenue expansion, improved margins and a future earnings multiple that sits below many current sector peers.
Result: Fair Value of $43.20 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Helmerich & Payne faces two clear swing factors: a potential rig overcapacity if drilling activity falls further and its heavy reliance on U.S. shale basins.
Find out about the key risks to this Helmerich & Payne narrative.
Another View: Helmerich & Payne Through A Cash Flow Lens
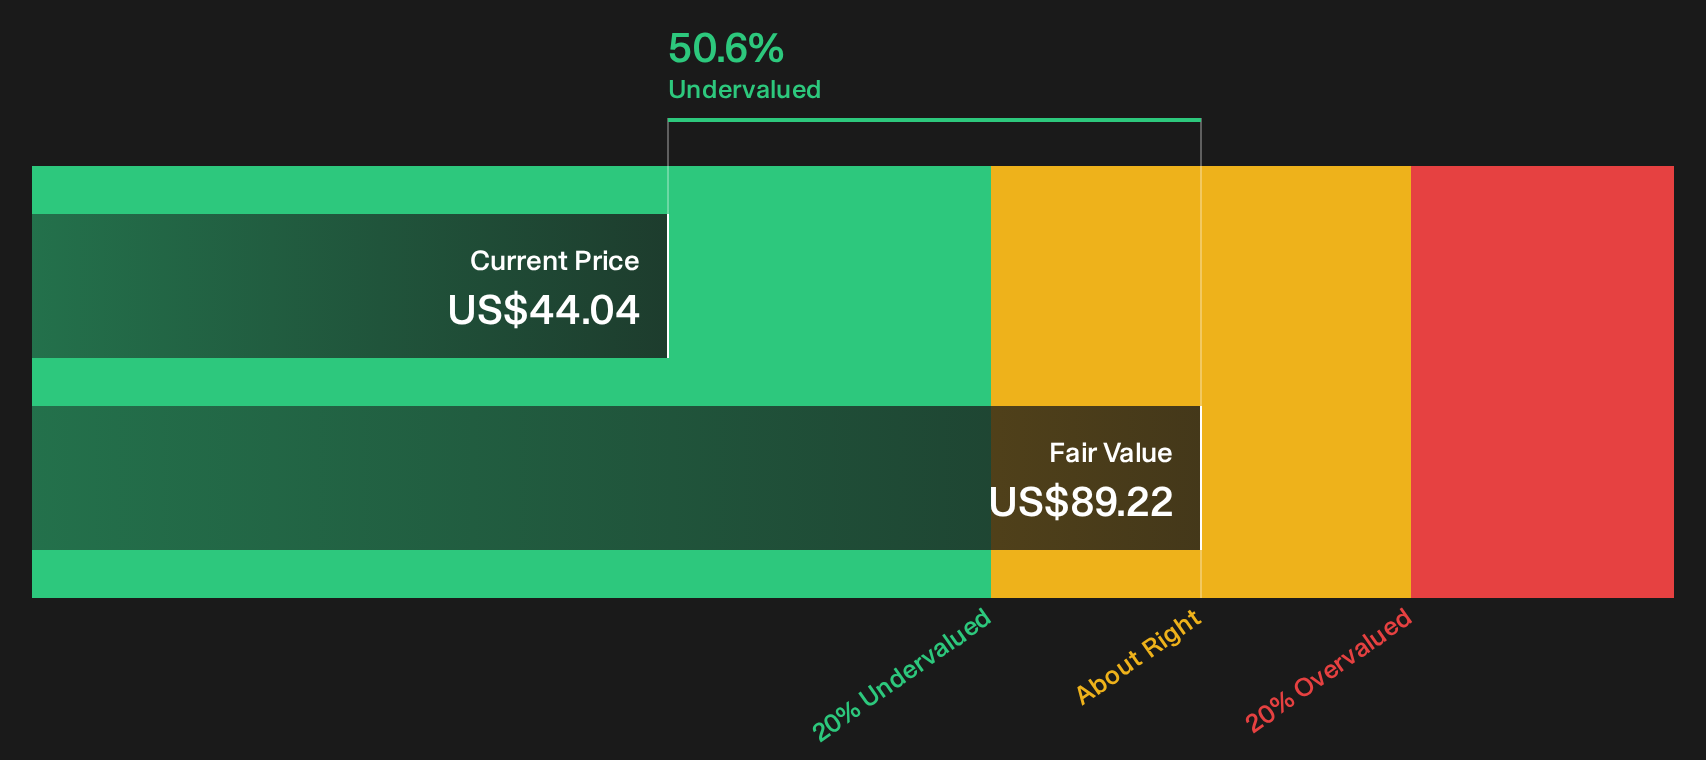
The analyst narrative sees Helmerich & Payne as only 1.9% overvalued at $44.04 compared with a fair value of $43.20. The SWS DCF model tells a very different story, with an estimated future cash flow value of $89.22, which frames the current quote as deeply undervalued. Which version of fair value do you trust more, the earnings-based target or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Helmerich & Payne's value story so far? Use that tension as a prompt to move quickly: pull up the numbers, compare assumptions, and then weigh the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Helmerich & Payne?
Do not stop with Helmerich & Payne. If you only focus on one stock, you risk missing other opportunities that might fit your goals even better.
- Chase potential upside by scanning a focused pool of stocks that screen as undervalued through the 32 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by running a 11 resilient stocks with low risk scores that filters for companies with more resilient profiles.
- Hunt for under-the-radar opportunities by using the 15 high quality undiscovered gems that highlights quality businesses the crowd may have overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com