


How Investors Are Reacting To Intuit (INTU) Soft Full Year Guidance
- Intuit reported Q2 revenue of US$4.35b, about 2% above analyst expectations, but issued softer full-year guidance and missed earnings-per-share forecasts. This created pressure on the outlook despite ongoing investment in its AI and platform strategy.
- The mixed update highlights a core tension in Intuit's model: heavy near-term spending to expand its end-to-end financial platform versus investor focus on margin and earnings predictability.
- We will now look at how Intuit's investment narrative could be affected by softer full-year guidance and an EPS shortfall.
Intuit Investment Narrative Recap
To own Intuit, you need to believe its AI driven, end to end financial platform across QuickBooks, TurboTax, Credit Karma and Mailchimp can keep pulling more services and payments into a single workflow for consumers and businesses. The near term focus is on whether recent revenue beats can translate into cleaner earnings delivery after the softer full year guidance and EPS miss.
The main short term catalyst is execution on AI led products and mid market expansion, while keeping Mailchimp, international and Credit Karma volatility contained. The recent guidance reset already reflects some of those pressures, so the fresh information appears more about timing and confidence than a major change to the operating thesis.
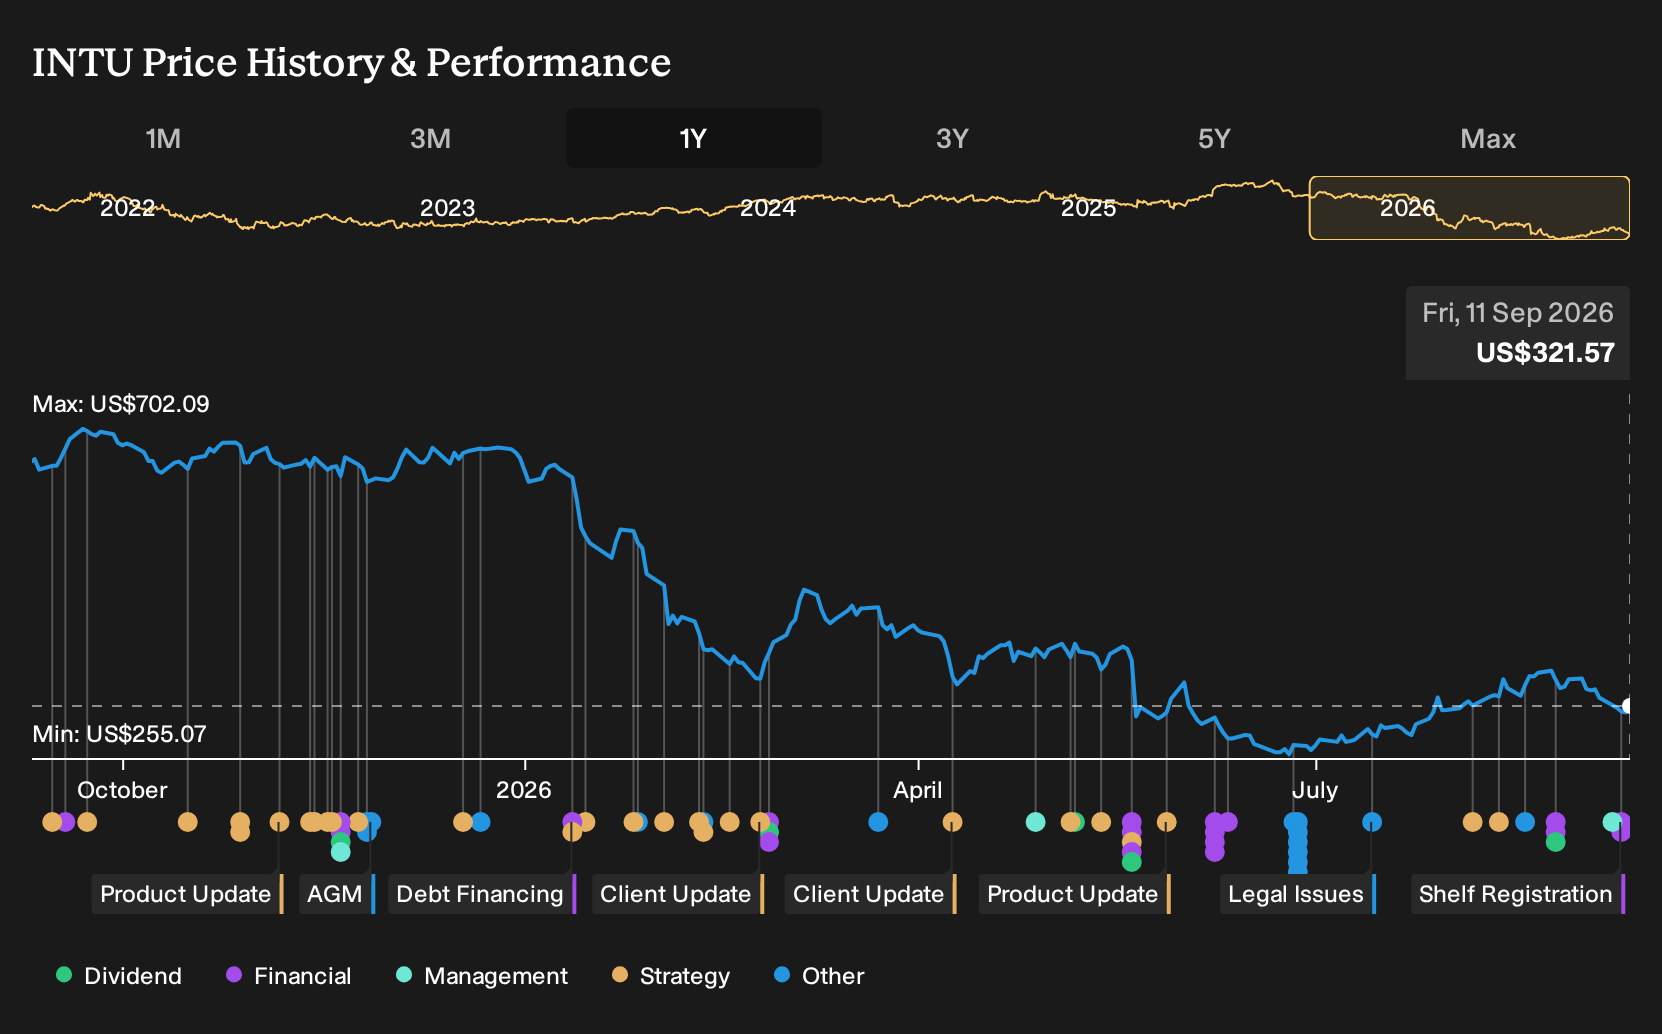
The most relevant recent update is Intuit’s new omnibus shelf registration that covers common and preferred stock, debt securities and warrants. This filing gives the company flexibility to access capital markets quickly, which matters when it is investing in AI, rolling out mid market products and considering potential add on deals to strengthen the overall platform.
For investors, this sits squarely in the catalyst and risk mix. Extra balance sheet flexibility can support ongoing product spending if Mailchimp softness or lower pricing uplift in 2026 affects organic cash generation. It can also introduce funding and dilution questions if used heavily, so execution around capital allocation is now more closely linked to the equity story.
Intuit's narrative projects US$29.1b revenue and US$6.8b earnings by 2029. This assumes 11.6% yearly revenue growth and an earnings increase of about US$2.2b from US$4.6b today.
Uncover why Intuit's fair value indicates a 40% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Intuit, the big swing factor in the alternate view is AI execution. The most cautious analysts already worked off lower expectations, with annual revenue growth at 8.3% and earnings of about US$6.5b by 2029. They see heavier AI and mid market spending as a drag on future margins, and the fresh shelf registration could shift those narratives again.
Explore 16 other Intuit fair value estimates, including one that suggests it could be worth just $390.00!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Intuit research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Intuit. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intuit's overall financial health at a glance.
Looking For More Investment Ideas Beyond Intuit?
Once you have a view on Intuit, it can help to widen the lens and compare it with other opportunities that fit different risk, income, or quality profiles using the Simply Wall St Screener.
- For investors who want potential upside with an eye on fundamental strength, scan our hand picked set of 15 high quality undiscovered gems.
- If capital preservation and steadier profiles matter most to you, focus your search around our curated group of 11 resilient stocks with low risk scores.
- Income focused portfolios can start by shortlisting companies from the 6 dividend fortresses that aim to combine higher yields with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com