


Automatic Data Processing (ADP) Could Be 6% Undervalued As AWS AI Tie Up Expands
Automatic Data Processing (ADP) stock is in focus after the company deepened its relationship with Amazon Web Services by appointing AWS as its primary cloud provider to support AI driven HR and payroll tools.
Recent price action shows that Automatic Data Processing has given back some ground in the very short term, with a 7 day share price return of a 3.37% decline and a 30 day share price return of a 1.72% decline. However, the 90 day share price return of 20.18% signals strong near term momentum building around its AI partnership narrative and ongoing dividend announcements. The 1 year total shareholder return of a 5.95% decline contrasts with a 5 year total shareholder return of 50.97%, pointing to a story where long term holders have still seen material value creation despite a softer recent stretch.
Scan how Automatic Data Processing’s AI and cloud story compares with a hand picked group of 32 AI small caps riding similar adoption tailwinds in HR tech and adjacent sectors.
Automatic Data Processing looks like a high quality HR and payroll platform with a deepening AI partnership and a long dividend record. The real tension is whether that mix is already fully reflected in today’s US$268 share price.
Most Popular Narrative: 6.4% Undervalued
Automatic Data Processing’s most followed narrative pegs fair value at $286.67, a touch above the recent $268.26 close. This view puts extra weight on the AI and cloud expansion story that underpins those numbers.
Adoption of Next Gen products (like Lyric HCM and Workforce Now Next Gen) and integration of acquisitions (e.g., WorkForce Software) are accelerating demand for advanced, cloud-based, and AI-driven HR solutions, directly locking in higher average revenue per user and supporting earnings growth through margin expansion.
Read the complete narrative. Read the complete narrative.
Want to see what growth recipe needs to play out for that fair value to hold up? The narrative leans hard on rising margins, steadier recurring revenue, and a premium earnings multiple that has to hold its ground. The detailed playbook is already mapped out. The question is whether you agree with it.
Result: Fair Value of $286.67 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Automatic Data Processing faces real pressure if bookings stay soft and payroll trends weaken, since slower client adds or retention could quickly undercut that 6.4% undervalued story.
Find out about the key risks to this Automatic Data Processing narrative.
Another View: What Multiples Say About Automatic Data Processing
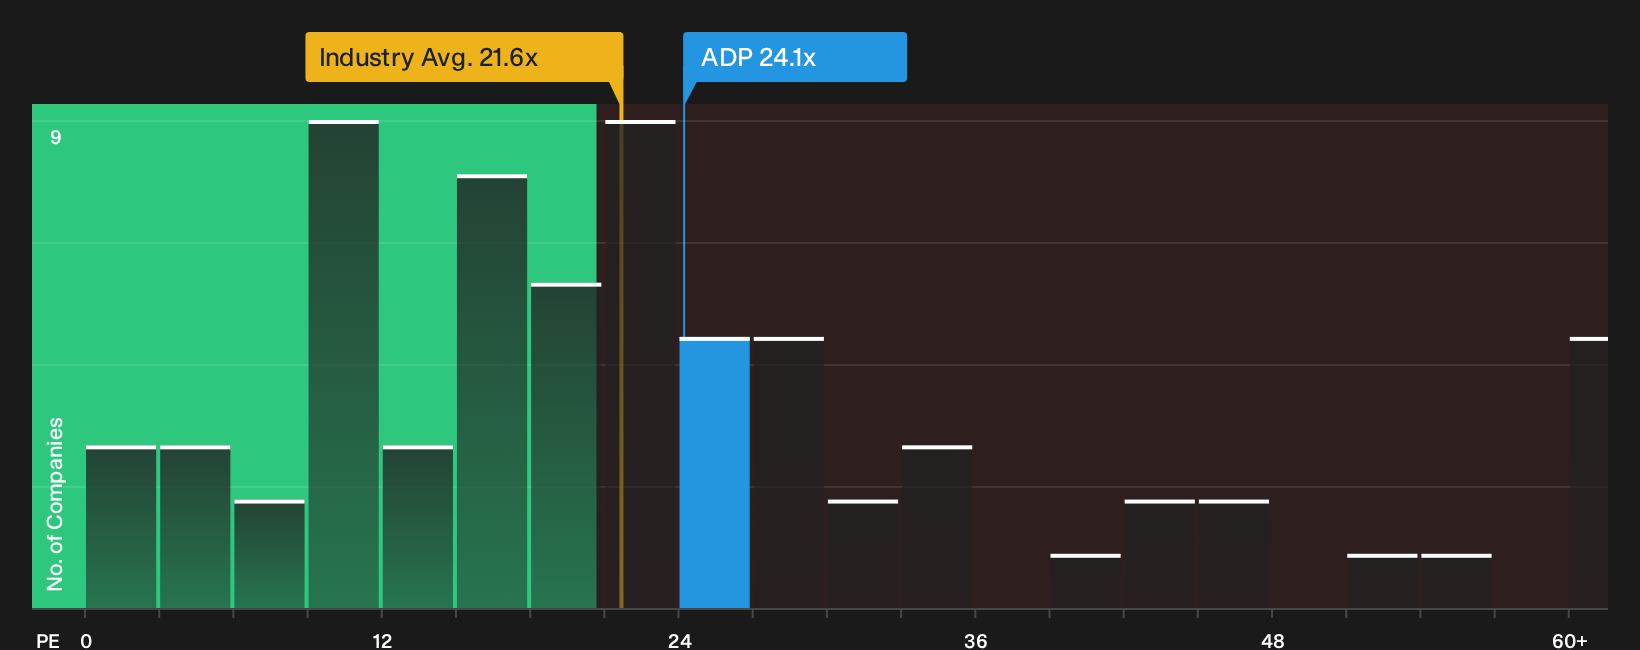
On the flip side of the fair value story, Automatic Data Processing trades on a P/E of 24.1x, which is higher than both the US Professional Services industry on 21.6x and peers on 20.5x. The fair ratio sits at 26.8x, so is this a valuation cushion or a margin for error if sentiment cools?
Investors who lean on relative pricing rather than cash flow models might focus on whether that gap to the fair ratio offers enough room for missteps, or whether paying above sector and peer averages simply compresses the margin of safety in a slower growth setup. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Automatic Data Processing is mixed, which is exactly why it helps to inspect the underlying drivers yourself and move quickly while sentiment is still reset. To see which positives investors are focused on, review the 3 key rewards.
Looking for more investment ideas beyond Automatic Data Processing?
If you like the setup around Automatic Data Processing but do not want all your capital tied to a single story, you can broaden your opportunity set with a focused screener shortlist before the next leg of market rotation leaves you reacting instead of prepared.
- Target potential value gaps by scanning a curated pool of companies that screen as quality but possibly mispriced through 32 high quality undervalued stocks.
- Strengthen income potential by reviewing a hand picked group of resilient payers through the 6 dividend fortresses.
- Dial down risk by checking a carefully filtered 11 resilient stocks with low risk scores that highlights businesses with more durable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com