


Dole (DOLE), Why Is The Produce Giant Back In Focus?
Dole (DOLE) is back in focus after fresh analysis compared the fruit supplier with avocado specialist Mission Produce, highlighting Dole’s broader mix of fresh produce, global reach, and automation efforts as key differences for investors to weigh.
Recent trading has been softer, with Dole’s share price down 1.8% over the last day and 4.9% over the past week. However, the 3-year total shareholder return of 18.9% versus a near flat 1-year total shareholder return suggests longer term holders have seen steadier progress than recent price moves imply.
Scan beyond Dole and compare it with a curated group of fresh-produce and packaged food players by reviewing the list of solid balance sheet and fundamentals (23 results).
Dole’s share price has eased even as fresh analysis flags a discounted valuation and a mixed recent return profile. Is most of the easy upside already behind the stock, or is the bigger opportunity still in front of it?
Most Popular Narrative: 38% Undervalued
Dole closed at $13.33 while the most followed valuation story pins fair value at $21.50, so the gap between market price and that narrative is wide.
While analyst consensus sees the refocused strategy following the Fresh Vegetables divestiture enabling improved capital allocation and margin expansion, the clarity and agility afforded by this move could unlock a multi-year cycle of strategic bolt-on acquisitions and organic investments, driving both accelerated revenue growth and sustainably higher net margins well beyond current market expectations.
Read the complete narrative. Read the complete narrative.
It is worth considering what kind of earnings path and margin profile would need to align with that $21.50 figure. The narrative leans on steady top line expansion, firmer profitability and a richer future earnings multiple to bridge the distance between today’s Dole share price and that higher fair value mark.
Result: Fair Value of $21.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Dole’s reliance on bananas and pineapples, along with higher sourcing and shipping costs, could pressure profitability and challenge the more optimistic valuation story.
Find out about the key risks to this Dole narrative.
Another View On Dole’s Valuation
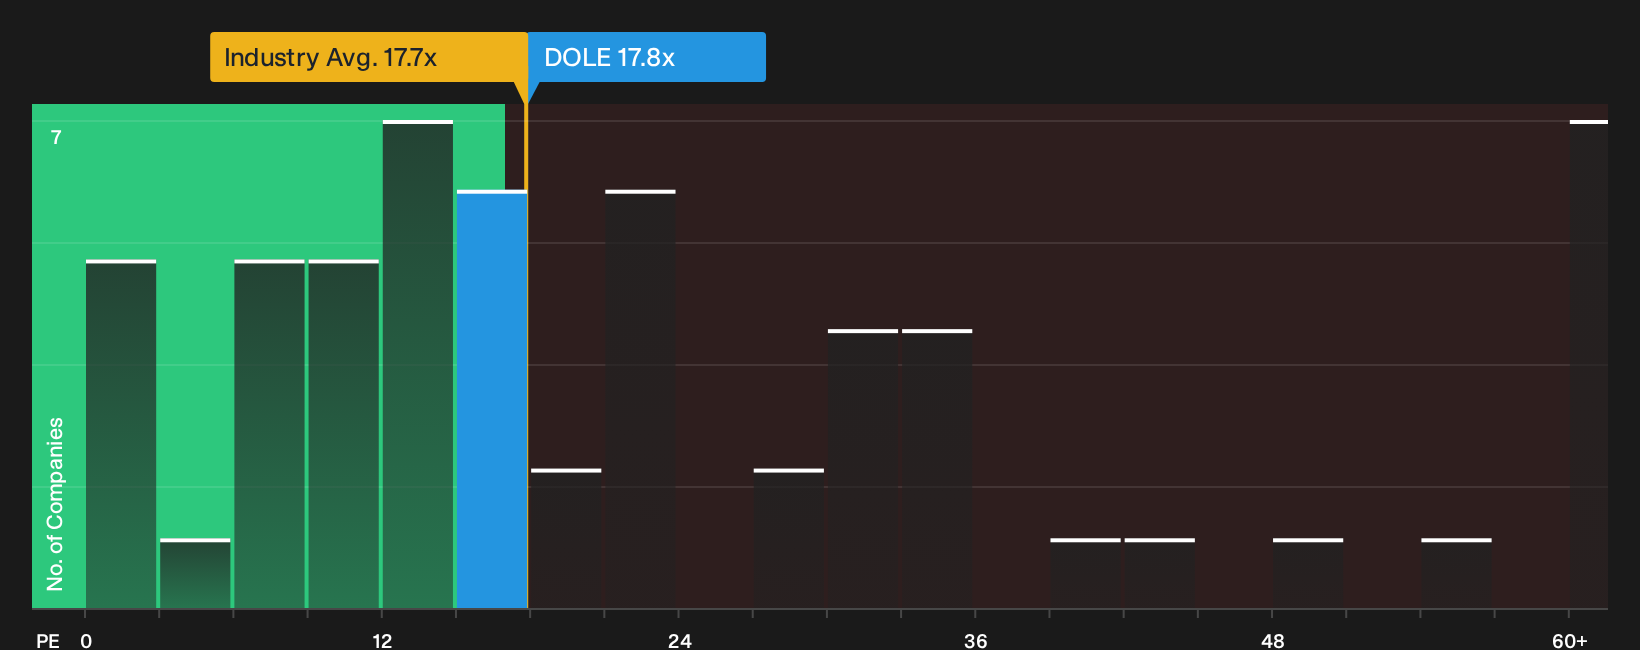
The SWS fair ratio points to a different angle. Dole trades on a P/E of 17.8x, very close to both peer and US Food industry averages of 17.7x, yet below a fair ratio of 20.4x. That mix hints at some upside on paper, but also raises the question of how much mispricing really exists.
For a closer look at how this earnings multiple stacks up against peers and the fair ratio, and what that might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Dole’s valuation and risk profile can pull you in both directions, so review the full risk and reward picture now and test it against your own judgment with the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Dole?
If Dole has you thinking harder about valuation and risk, keep that momentum and line up fresh candidates before the next move catches you off guard.
- Target resilient balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality businesses that the market may be overlooking by reviewing the 15 high quality undiscovered gems.
- Focus on income potential and stability by checking companies that qualify as 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com