


Does PCIe 6.0 Certification Change The Bull Case For Cadence Stock?
- Cadence Design Systems reported that its PCIe 6.0 PHY and controller IP on TSMC’s N3 process achieved first pass compliance at a recent PCI-SIG workshop, and the full subsystem is now listed and available to SoC providers.
- This PCIe 6.0 certification positions Cadence’s IP portfolio more squarely in the AI and high performance computing build out, where demand for high bandwidth connectivity can influence customer design wins and future licensing activity.
- We will now look at how Cadence’s fully certified PCIe 6.0 subsystem on TSMC N3 could influence the broader investment narrative.
Scan beyond Cadence Design Systems and see how other chip and infrastructure plays are positioning for high bandwidth AI workloads with our curated 89 AI infrastructure stocks
Cadence Design Systems Investment Narrative Recap
To own Cadence Design Systems you need to believe its AI driven design software and IP portfolio can keep attracting long term contracts even as competition in chip design tools intensifies. The recent PCIe 6.0 certification on TSMC N3 reinforces that story but does not radically change near term demand, which still hinges on customers prioritising AI and data center projects.
The nearer term swing factor remains execution in AI centric tools and IP, alongside how well Cadence converts collaborations with players like NVIDIA and Intel into recurring deals. The biggest risk sits with external shocks, including China exposure and acquisition integration, which could pressure margins if customer spending or operations are disrupted.
The PCIe 6.0 subsystem passing full compliance and moving onto the PCI SIG Integrators List looks most relevant here. It ties directly into Cadence Design Systems’ reported strength in its IP segment, where AI, chiplet architectures and new foundry routes have been important drivers, and gives SoC customers a certified, ready to deploy connectivity block on TSMC’s leading edge N3 node.
For you as an investor, the operational question is whether this type of certified IP can translate into steadier licensing pipelines and deeper relationships with large AI and data center clients, while geopolitical and competitive pressures stay manageable. Execution on this PCIe roadmap, up to PCIe 7.0, now sits alongside AI design platforms as a key catalyst to watch.
Cadence Design Systems' current analyst story points to US$8.3b in revenue and US$2.0b in earnings by 2029, based on revenue growing at 12.6% a year and earnings rising by US$0.6b from US$1.4b today to that 2029 consensus level.
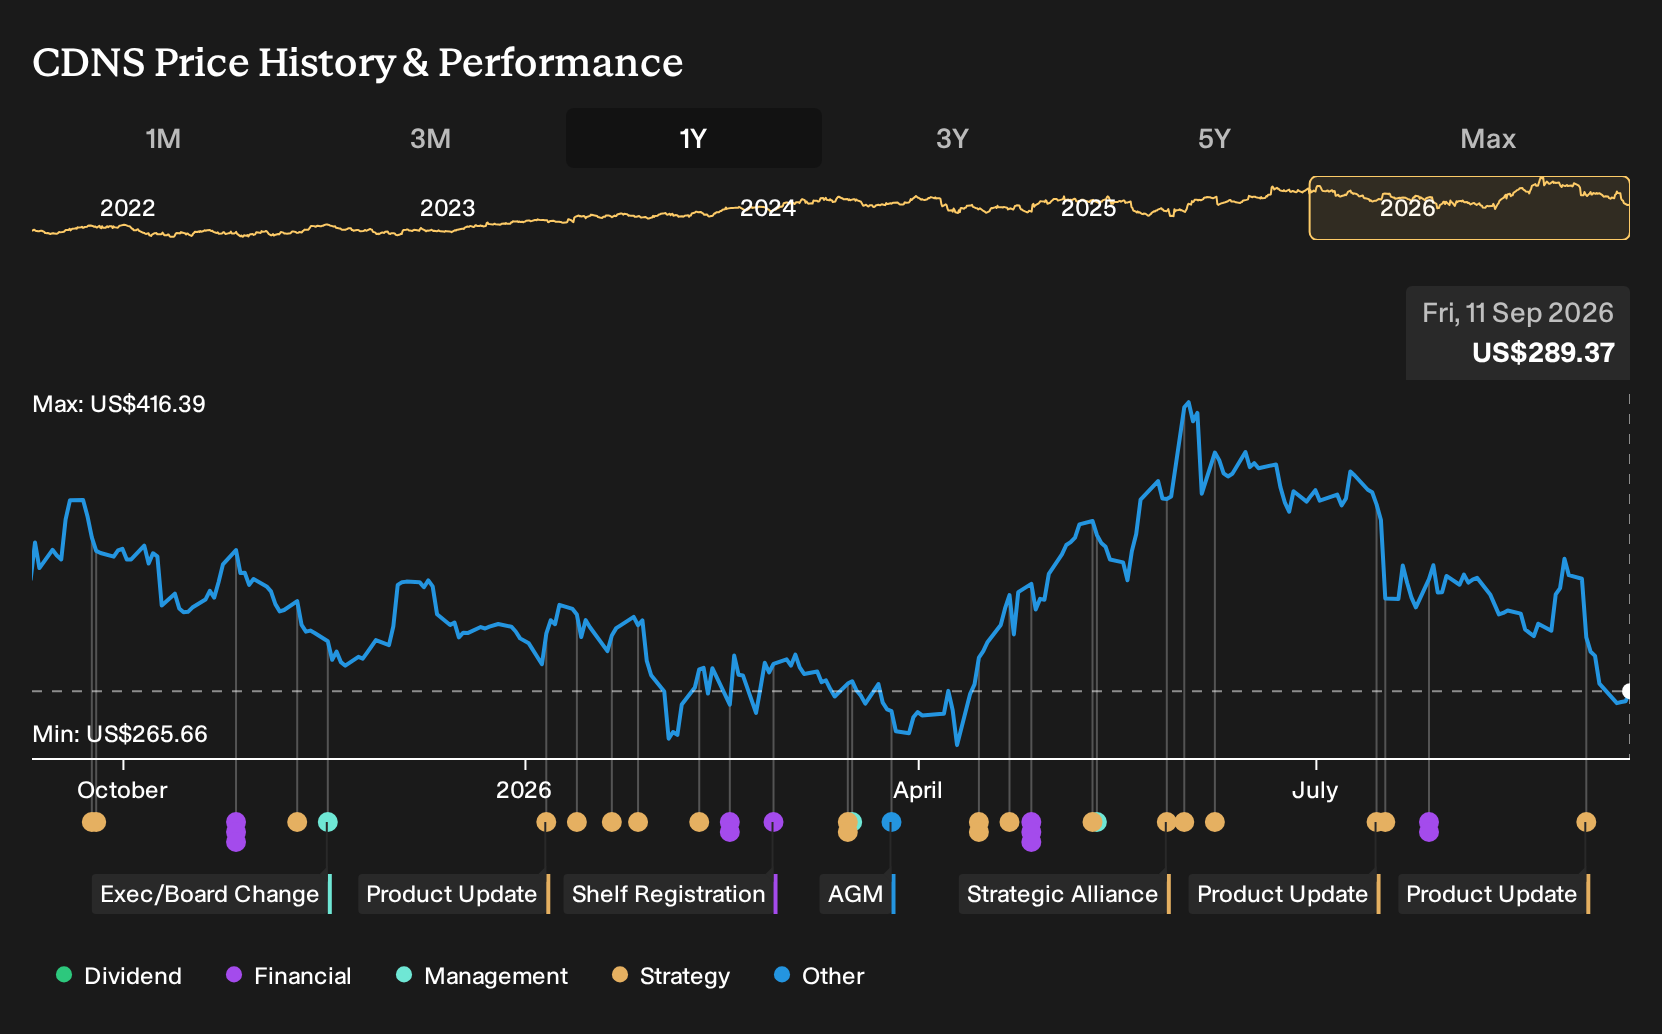
Uncover how Cadence Design Systems' fair value indicates a 40% potential upside to its current price, while that discount to expectations is still open.
Exploring Other Perspectives
You can also frame this PCIe 6.0 win as a more positive catalyst suggesting that Cadence Design Systems’ IP business could outpace earlier assumptions. The most optimistic analysts were already modelling revenue of about US$9.1b and earnings near US$2.6b by 2029. Those views predate this announcement, so you may see opinions shift again.
Explore 6 other Cadence Design Systems fair value estimates, including one that suggests as much as 62% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cadence Design Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cadence Design Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cadence Design Systems' overall financial health at a glance.
Looking For More Ideas Beyond Cadence Design Systems?
If the Cadence Design Systems story has sharpened your interest in AI and infrastructure, it can help to widen the watchlist and see how other businesses stack up on quality, risk, and income potential.
- If you want potential value with quality fundamentals, start with our 32 high quality undervalued stocks that already clear a basic bar on cash flows and balance sheet strength.
- If capital preservation and steadier profiles matter more to you than big swings, filter for 11 resilient stocks with low risk scores that score well on financial health and risk metrics.
- If you prefer hunting for underfollowed opportunities, focus on 15 high quality undiscovered gems that pair solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com