


Momentum shift from grains to cattle continues
Howdy market watchers!
We pray for America and all the families impacted by the September 11th attacks.
Hope everyone enjoyed the unofficial end to summer with a long, Labor Day Weekend. While it was a shortened trading week, there was still plenty of time for action in the markets.
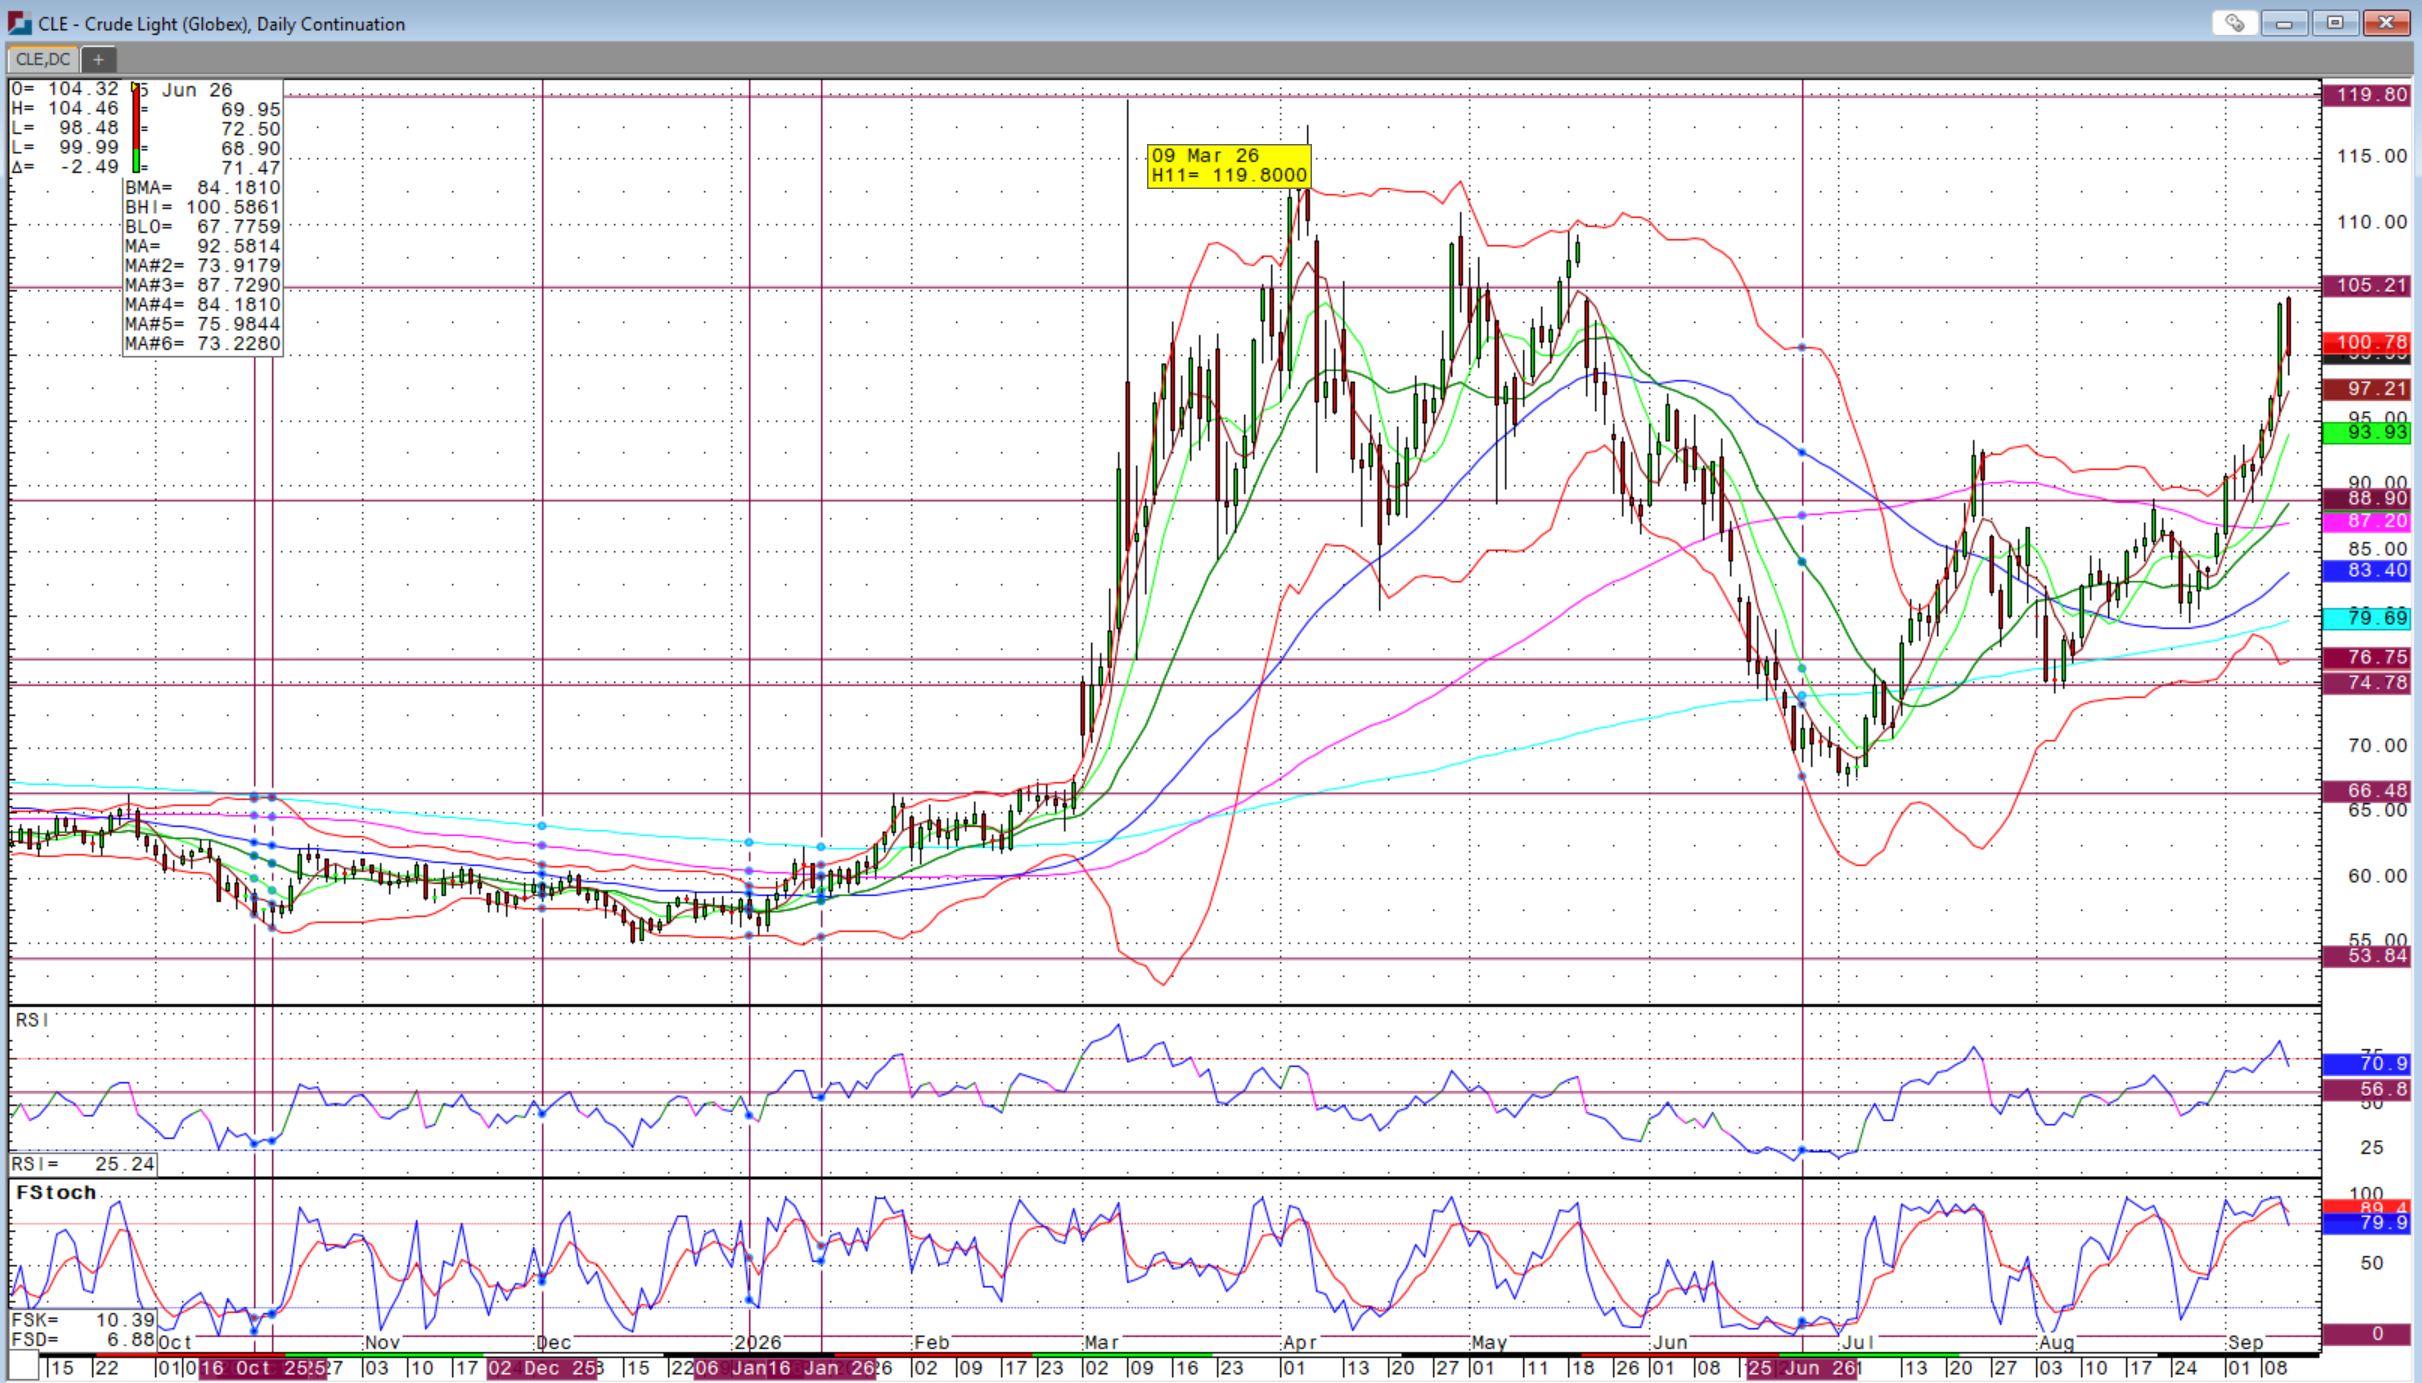
The energy complex was the most impulsive with crude oil surging to the highest levels since May 19th on escalation in the Strait of Hormuz between Iran and the US forces. Both Brent and WTI crude oil closed the week above $100 per barrel.
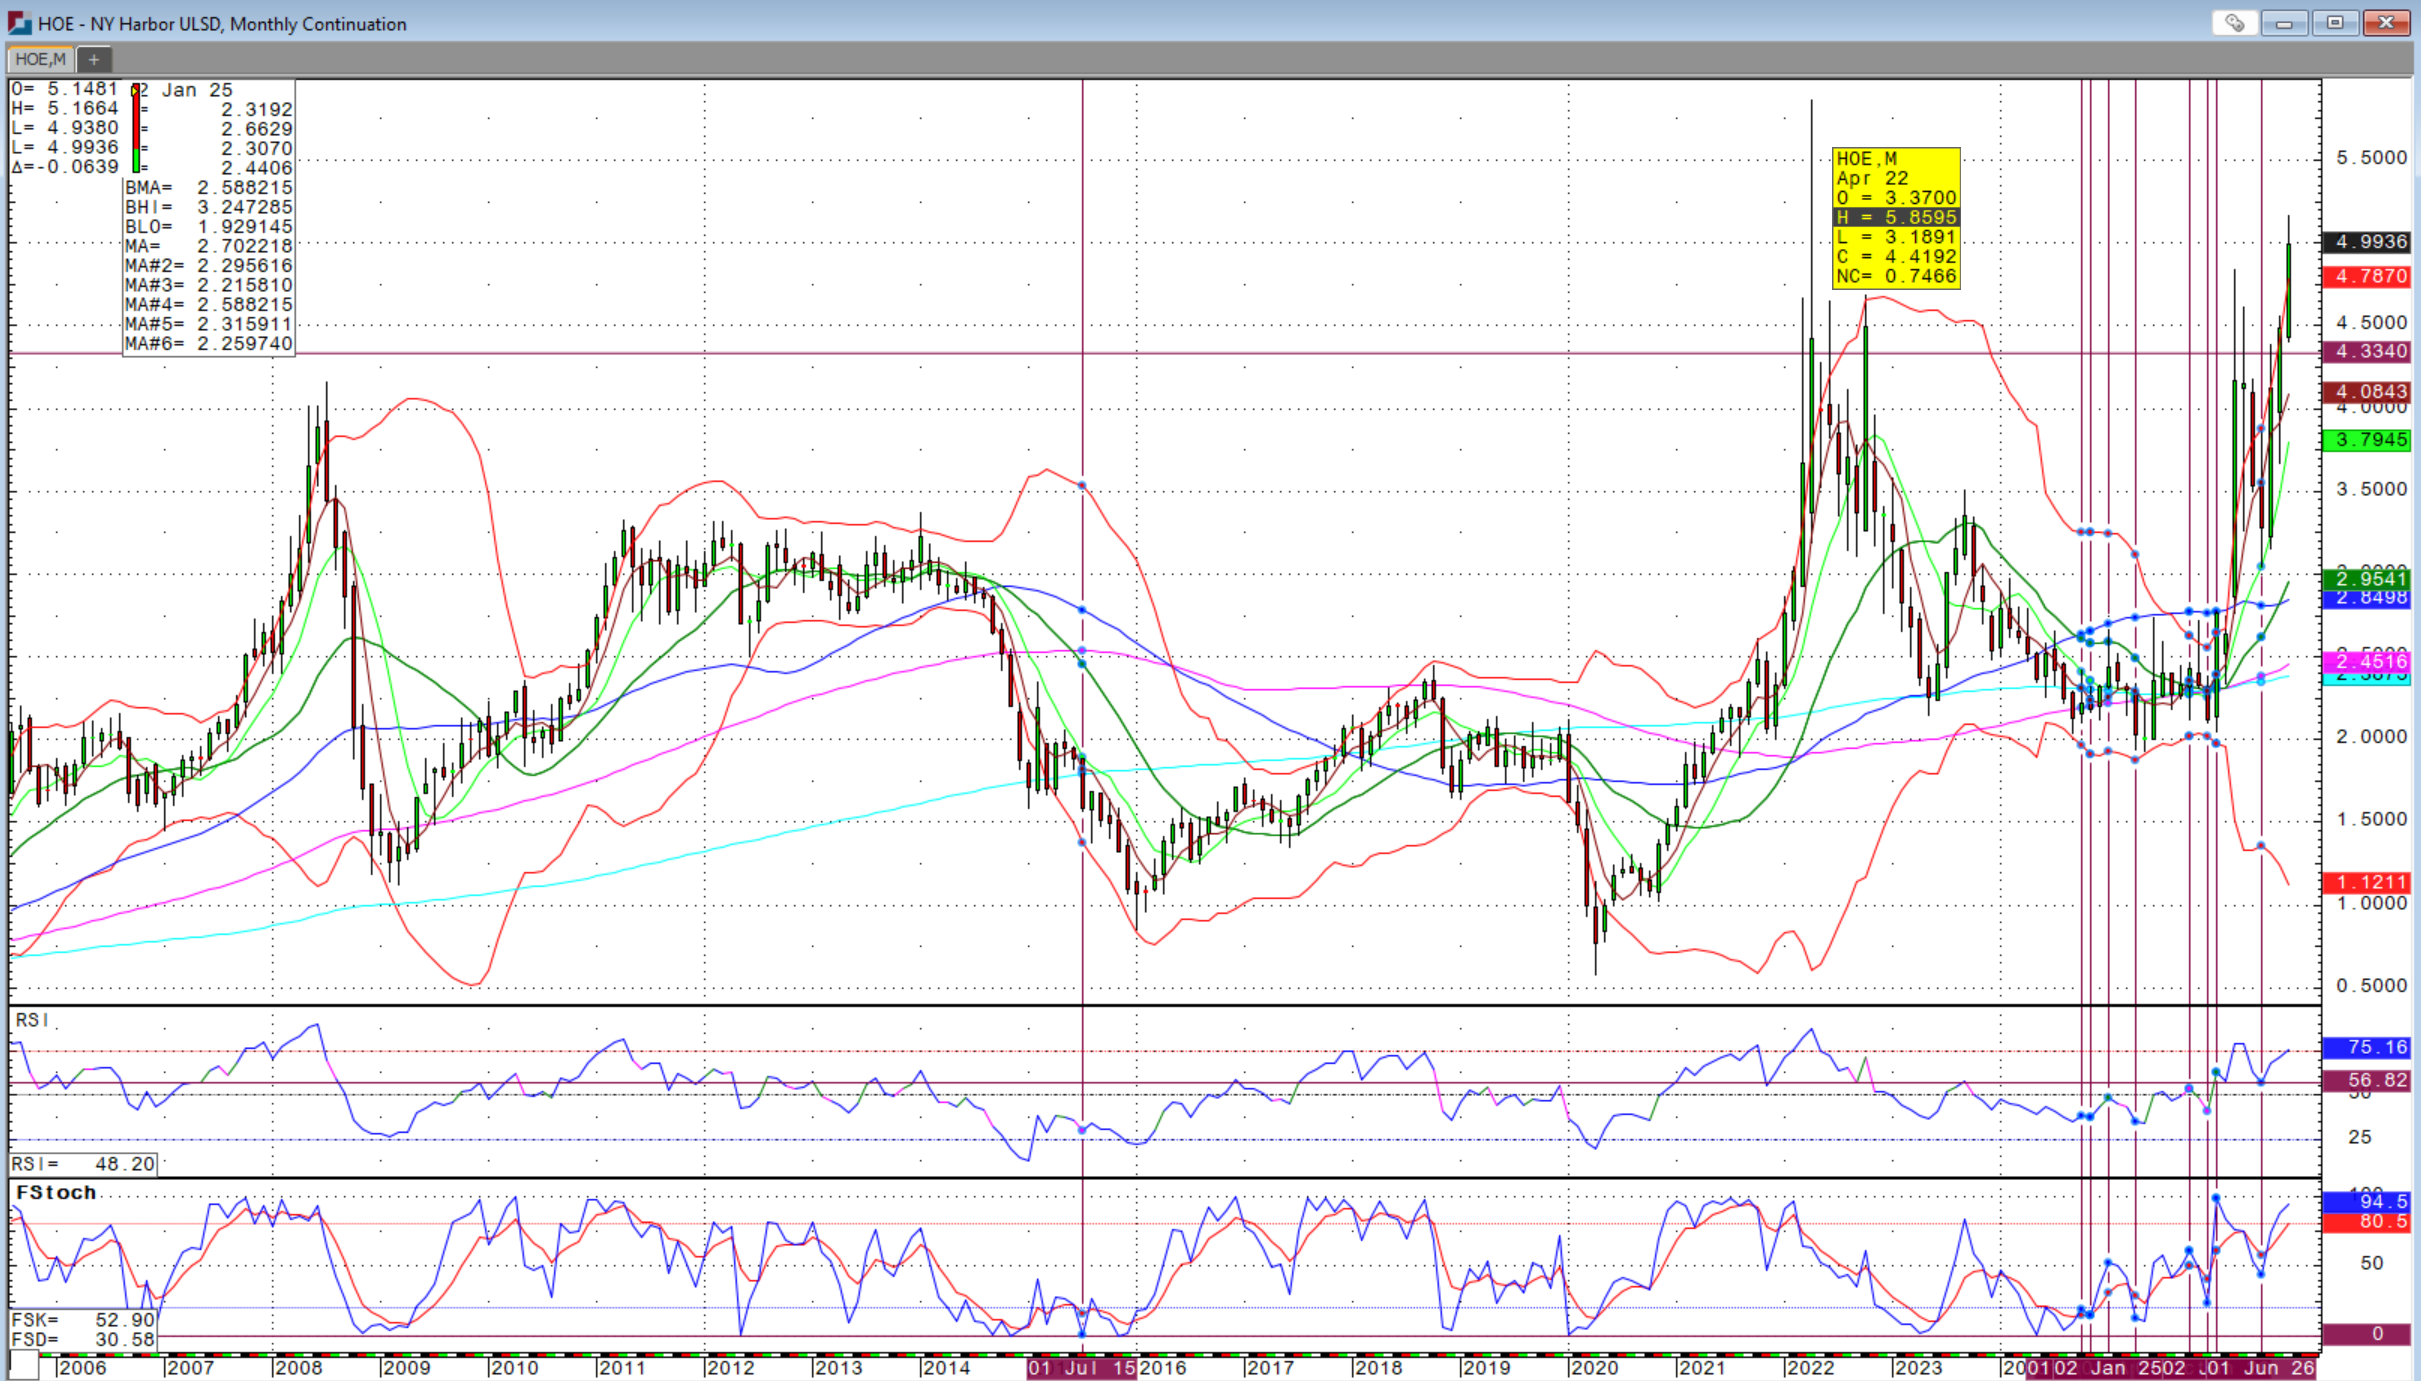
Perhaps the more concerning and relatable context is the surge in diesel prices that in some areas of the world reached the highest level ever this past week. The NY Harbor ULSD (Ultra-Low Sulfur Diesel) futures posted new recent highs above the March 2026 peak when the Iran conflict started and closed near the $5.00 level. This is the highest level ever on the ULSD since Russia’s attack on Ukraine in April 2022.
This price surge in energy prices comes at a time when inflation is creeping higher. Fuel is an input for basically everything and such gains in this critical cost item will lead to follow-on inflation in virtually every category for the consumer. In fact, August CPI was released on Friday morning and showed inflation increasing to 3.4 percent year-over-year versus the Federal Reserve’s target at 2.0 percent. The odds of an interest rate increase at next week’s FOMC meeting are increasing by the day.
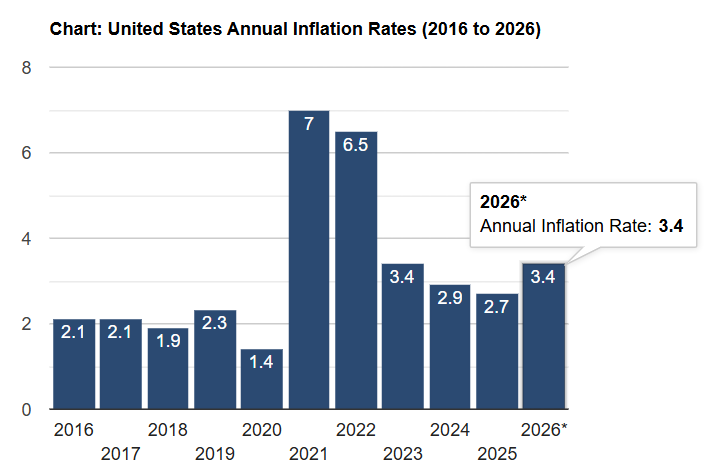
Source: US Inflation Calculator
For agriculture, such increases in fuel prices come right at the time when the bulk of corn harvest is starting in the Midwest and preparations for winter wheat planting are beginning in the Southern Plains. Indeed grain prices have rallied in recent months since the end of June low, it really is not enough to offset the cost of inputs including fertilizer in addition to fuel.
While grain prices are still at elevated levels, the momentum is beginning to shift as harvest approaches. I informed clients at the beginning of the week that it looked like the long grains, short cattle trade was beginning to flip. That is exactly how the week panned out into the USDA Crop Production and WASDE reports released on Friday at 11 AM CDT.
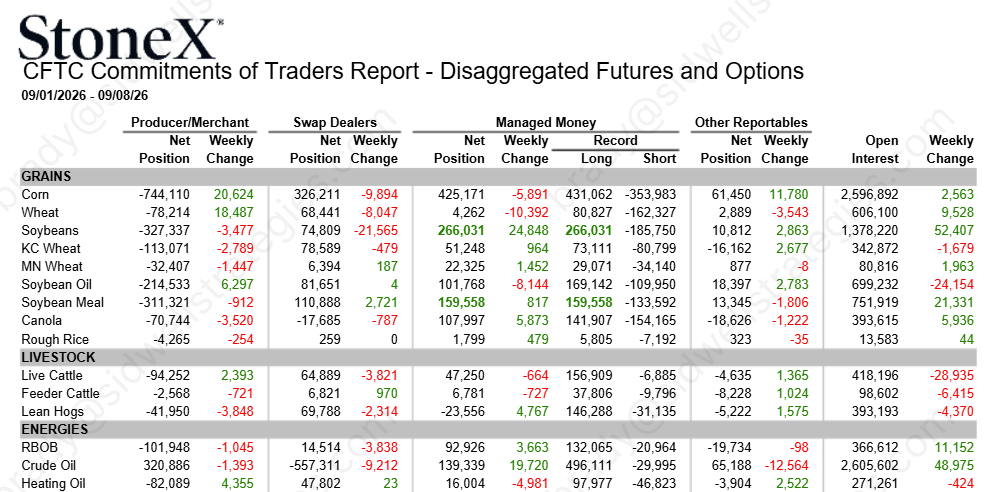
With the extended rally in grain markets and the record net long of managed money in corn, there was significant anticipation for this report. Recall, the most recent USDA yield for the US corn crop was at 180.7 bushels per acre (bpa) in stark contrast to Profarmer’s recent 173.2 bpa.
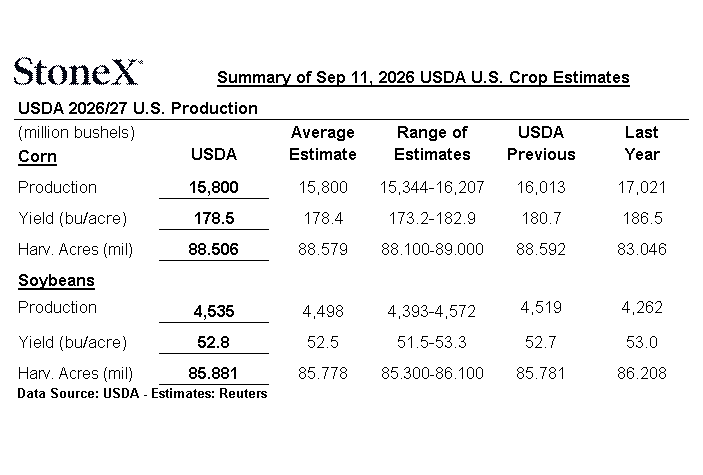
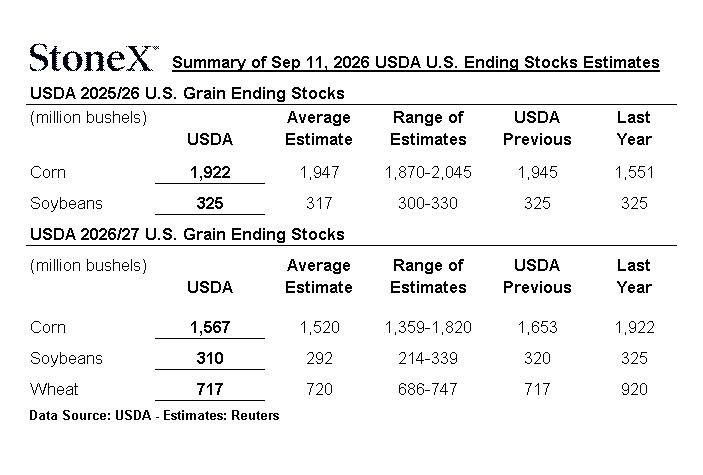
The USDA ended up cutting corn yields to 178.5 bpa versus trade expectations for 178.4 bpa. With harvested acres cut from 88.592 million acres to 88.506 million acres, total US corn crop production was reduced to 15.800 billion bushels exactly in line with trade guesses versus last month’s 16.013 billion bushels. US soybean yields were increased by 0.1 bpa above last month’s estimation and 0.3 bpa higher than trade guesses. Harvested acres were pegged at 85.881 billion bushels, up from last month’s 85.781 billion bushels to bring total production to 4.535 billion bushels, above last month’s 4.519 billion bushels and trade guesses of 4.498 billion bushels. US wheat ending stocks were unchanged from last month at 717 million bushels while trade guesses were for an increase to 720 million bushels.
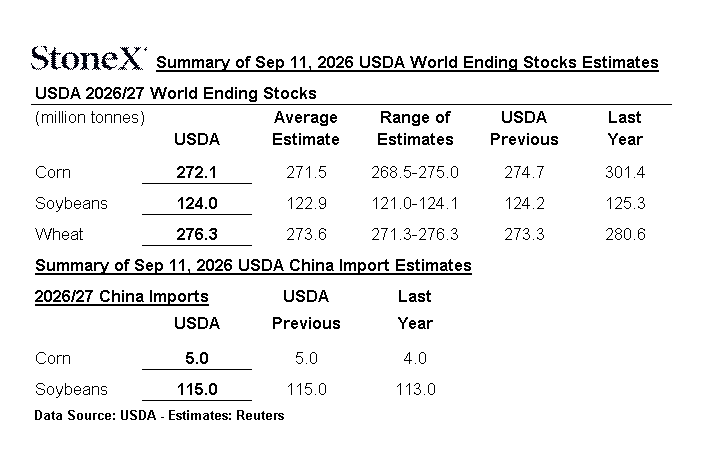
On a global level, corn ending stocks were cut to 272.1 million bushels from 274.7 million bushels while trade guesses were for more of a decrease to 271.5 million bushels. World soybean ending stocks were cut from 125.0 million bushels last month to 124.0 million bushels while a further cut to 122.9 million bushels was expected.
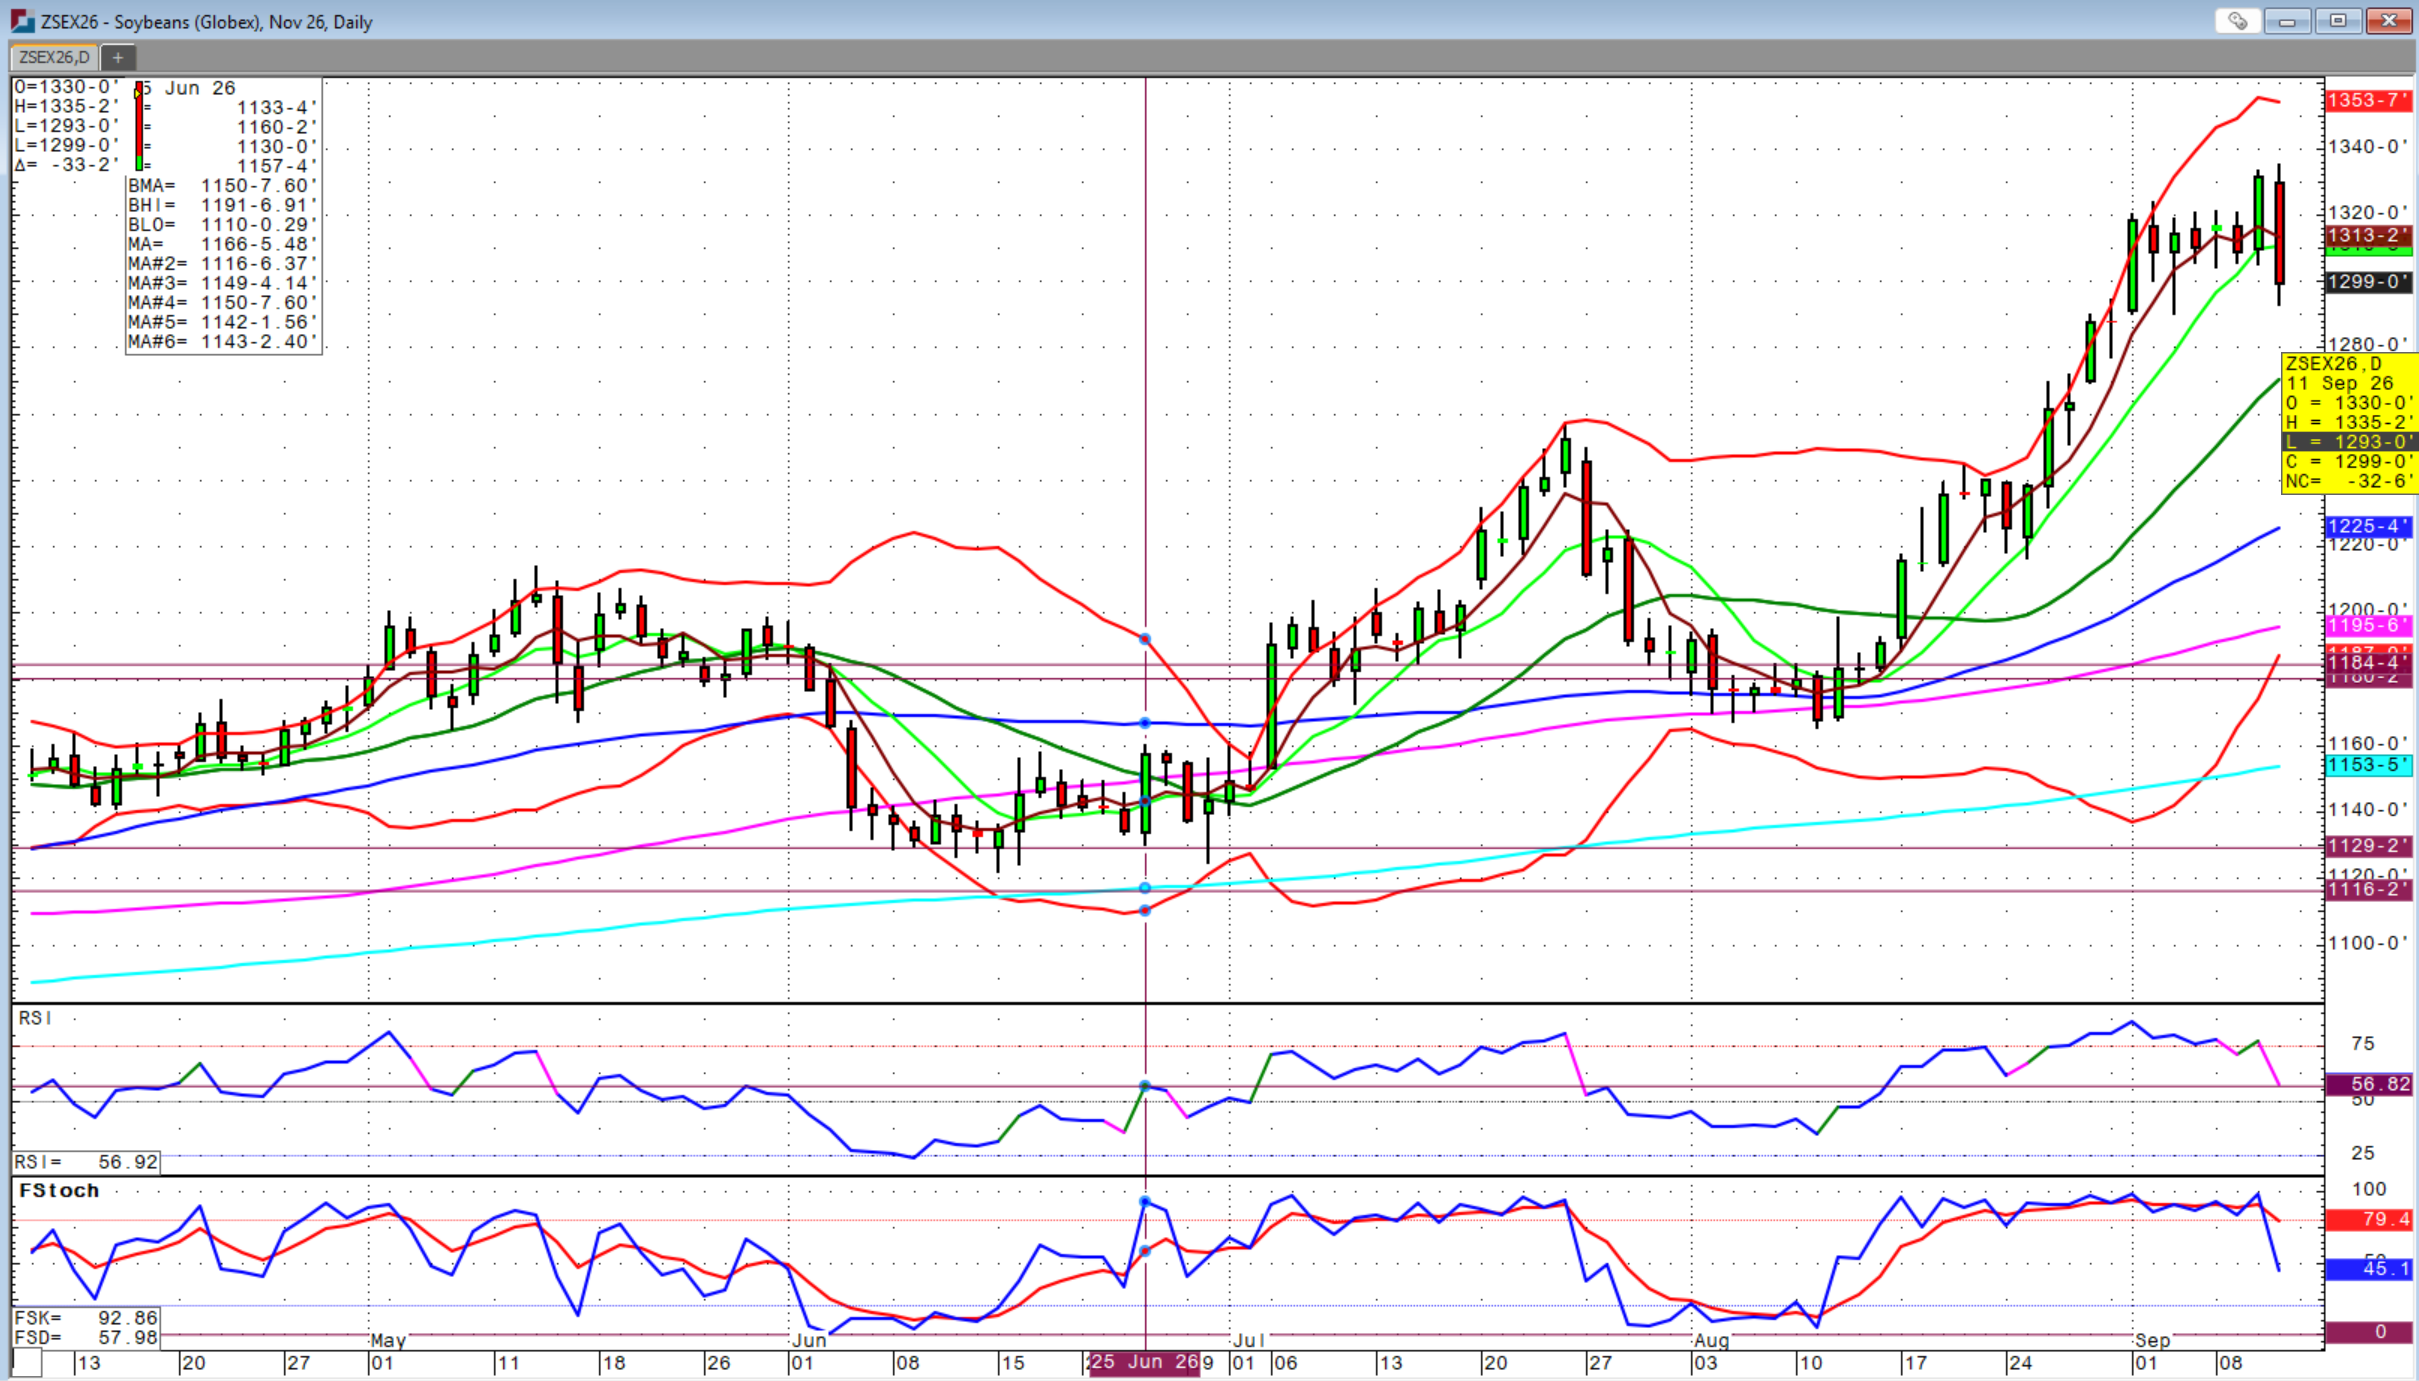
With all grain markets down sharply pre-report, there was a rebound after the report’s release with corn up 8 cents at one point right after the release, but then the rally faded into the close. The soybean futures chart put in an outside reversal lower day with a higher high and lower low, but with a lower close while corn had an outside day high-low, but closed nearly neutral on the day.
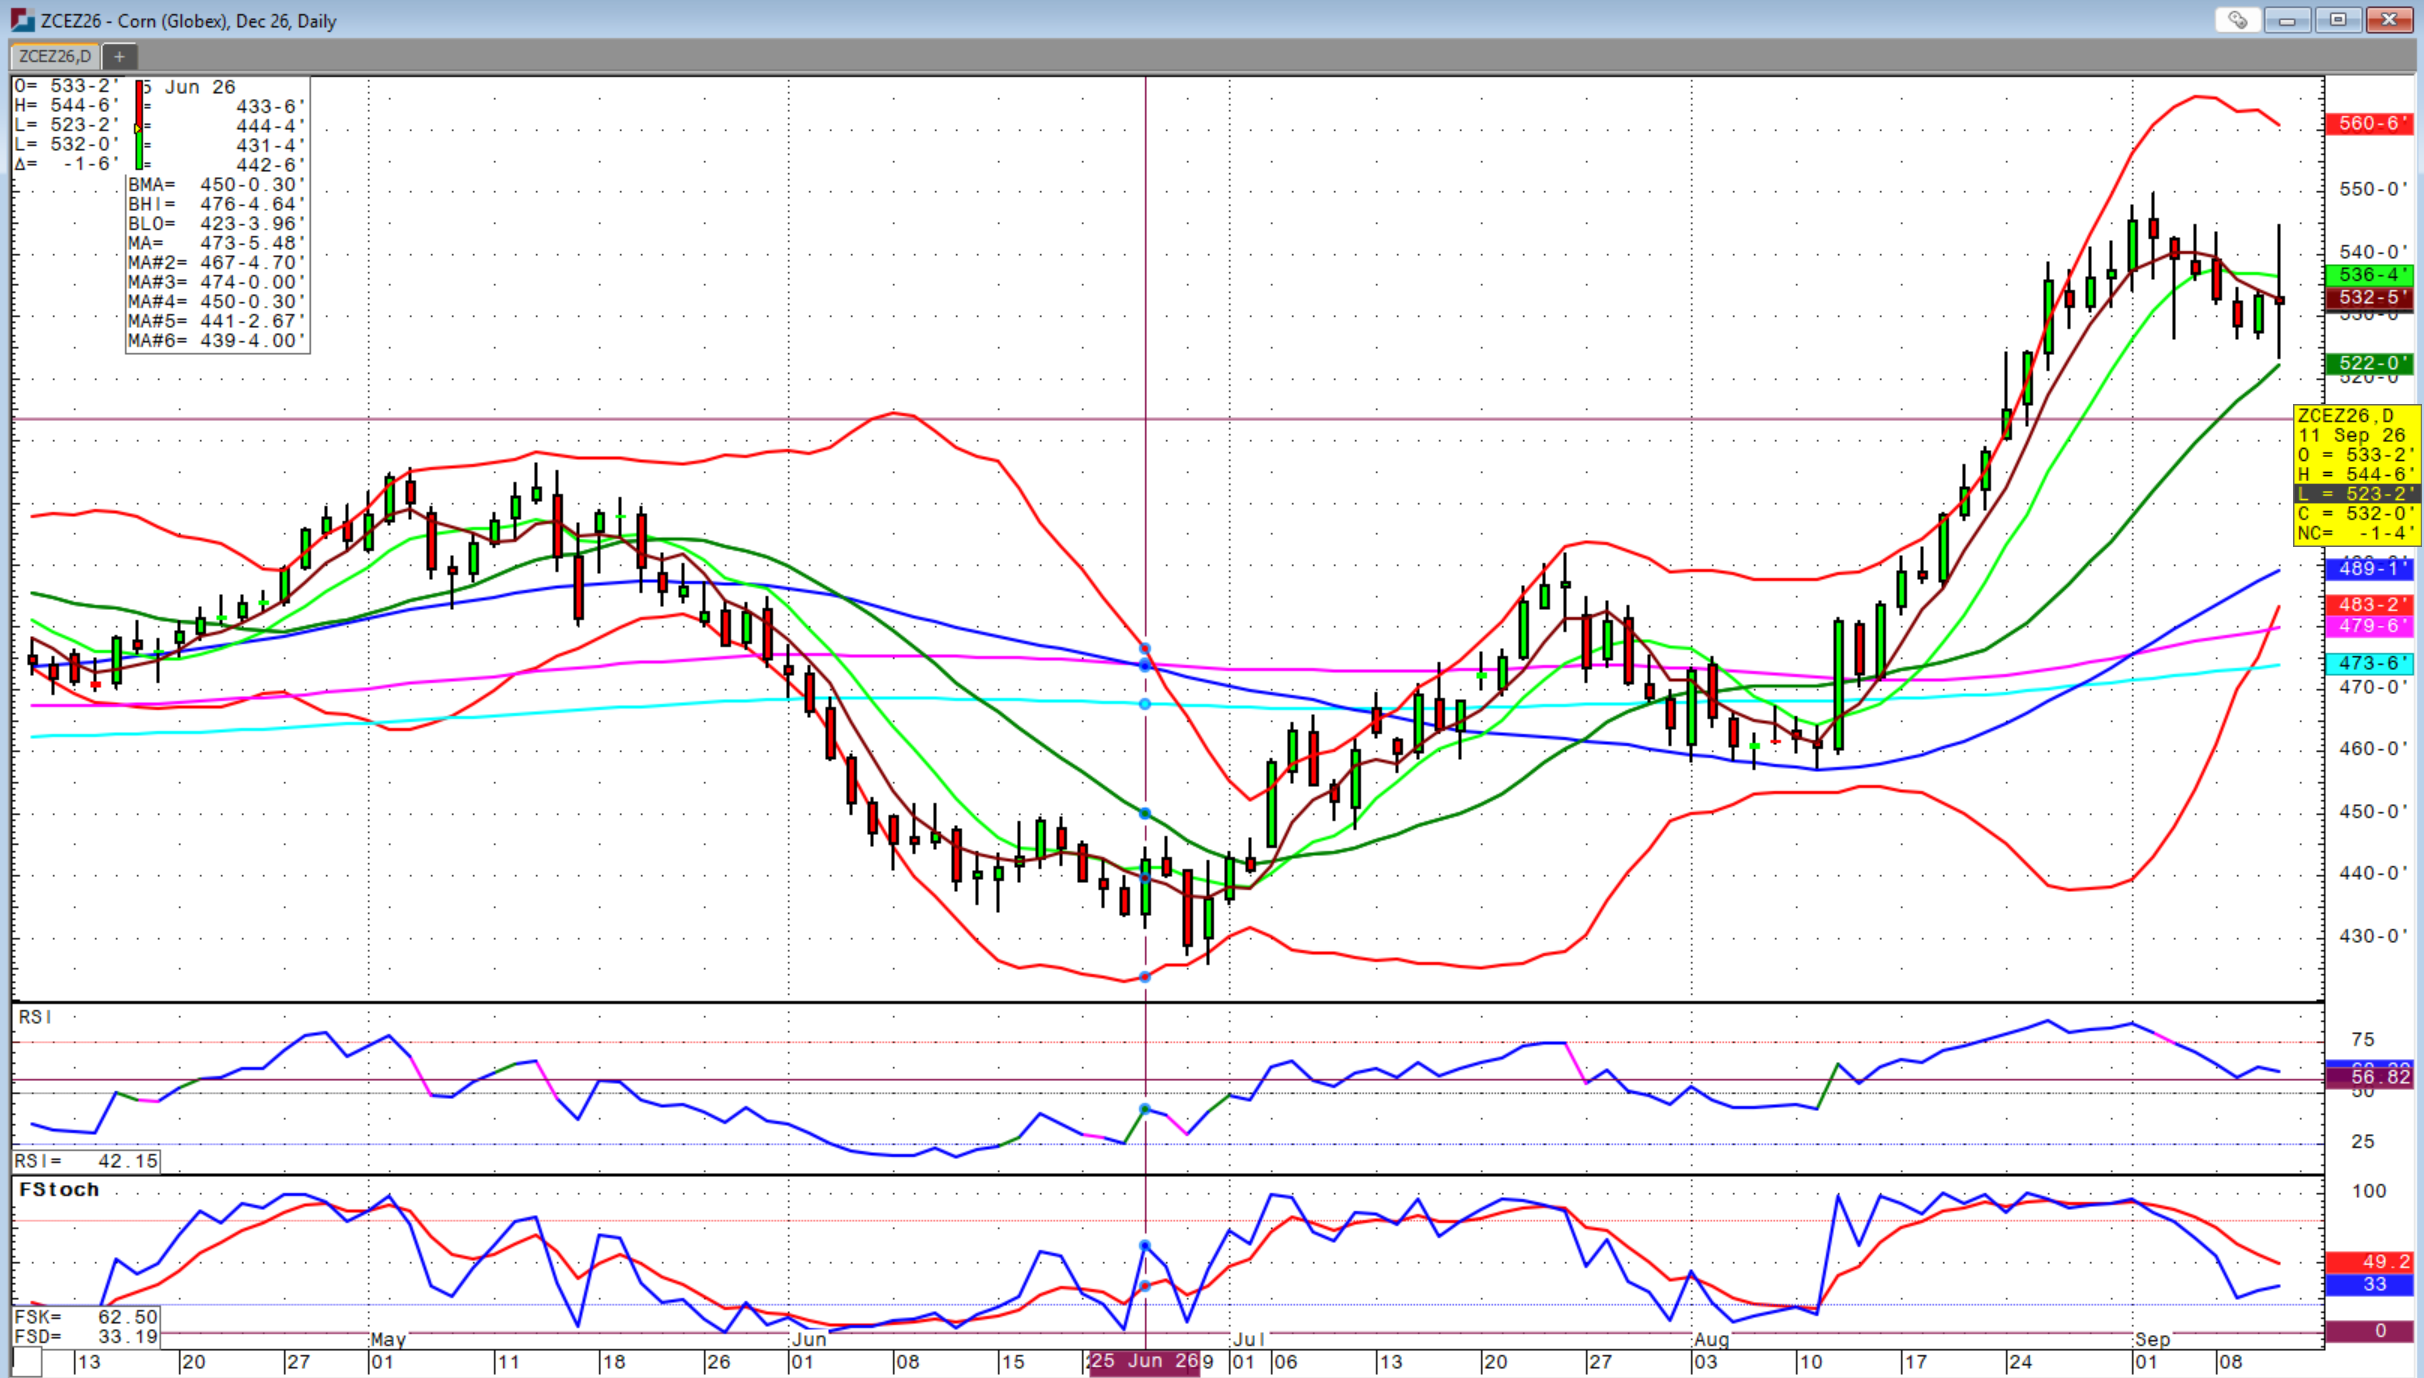
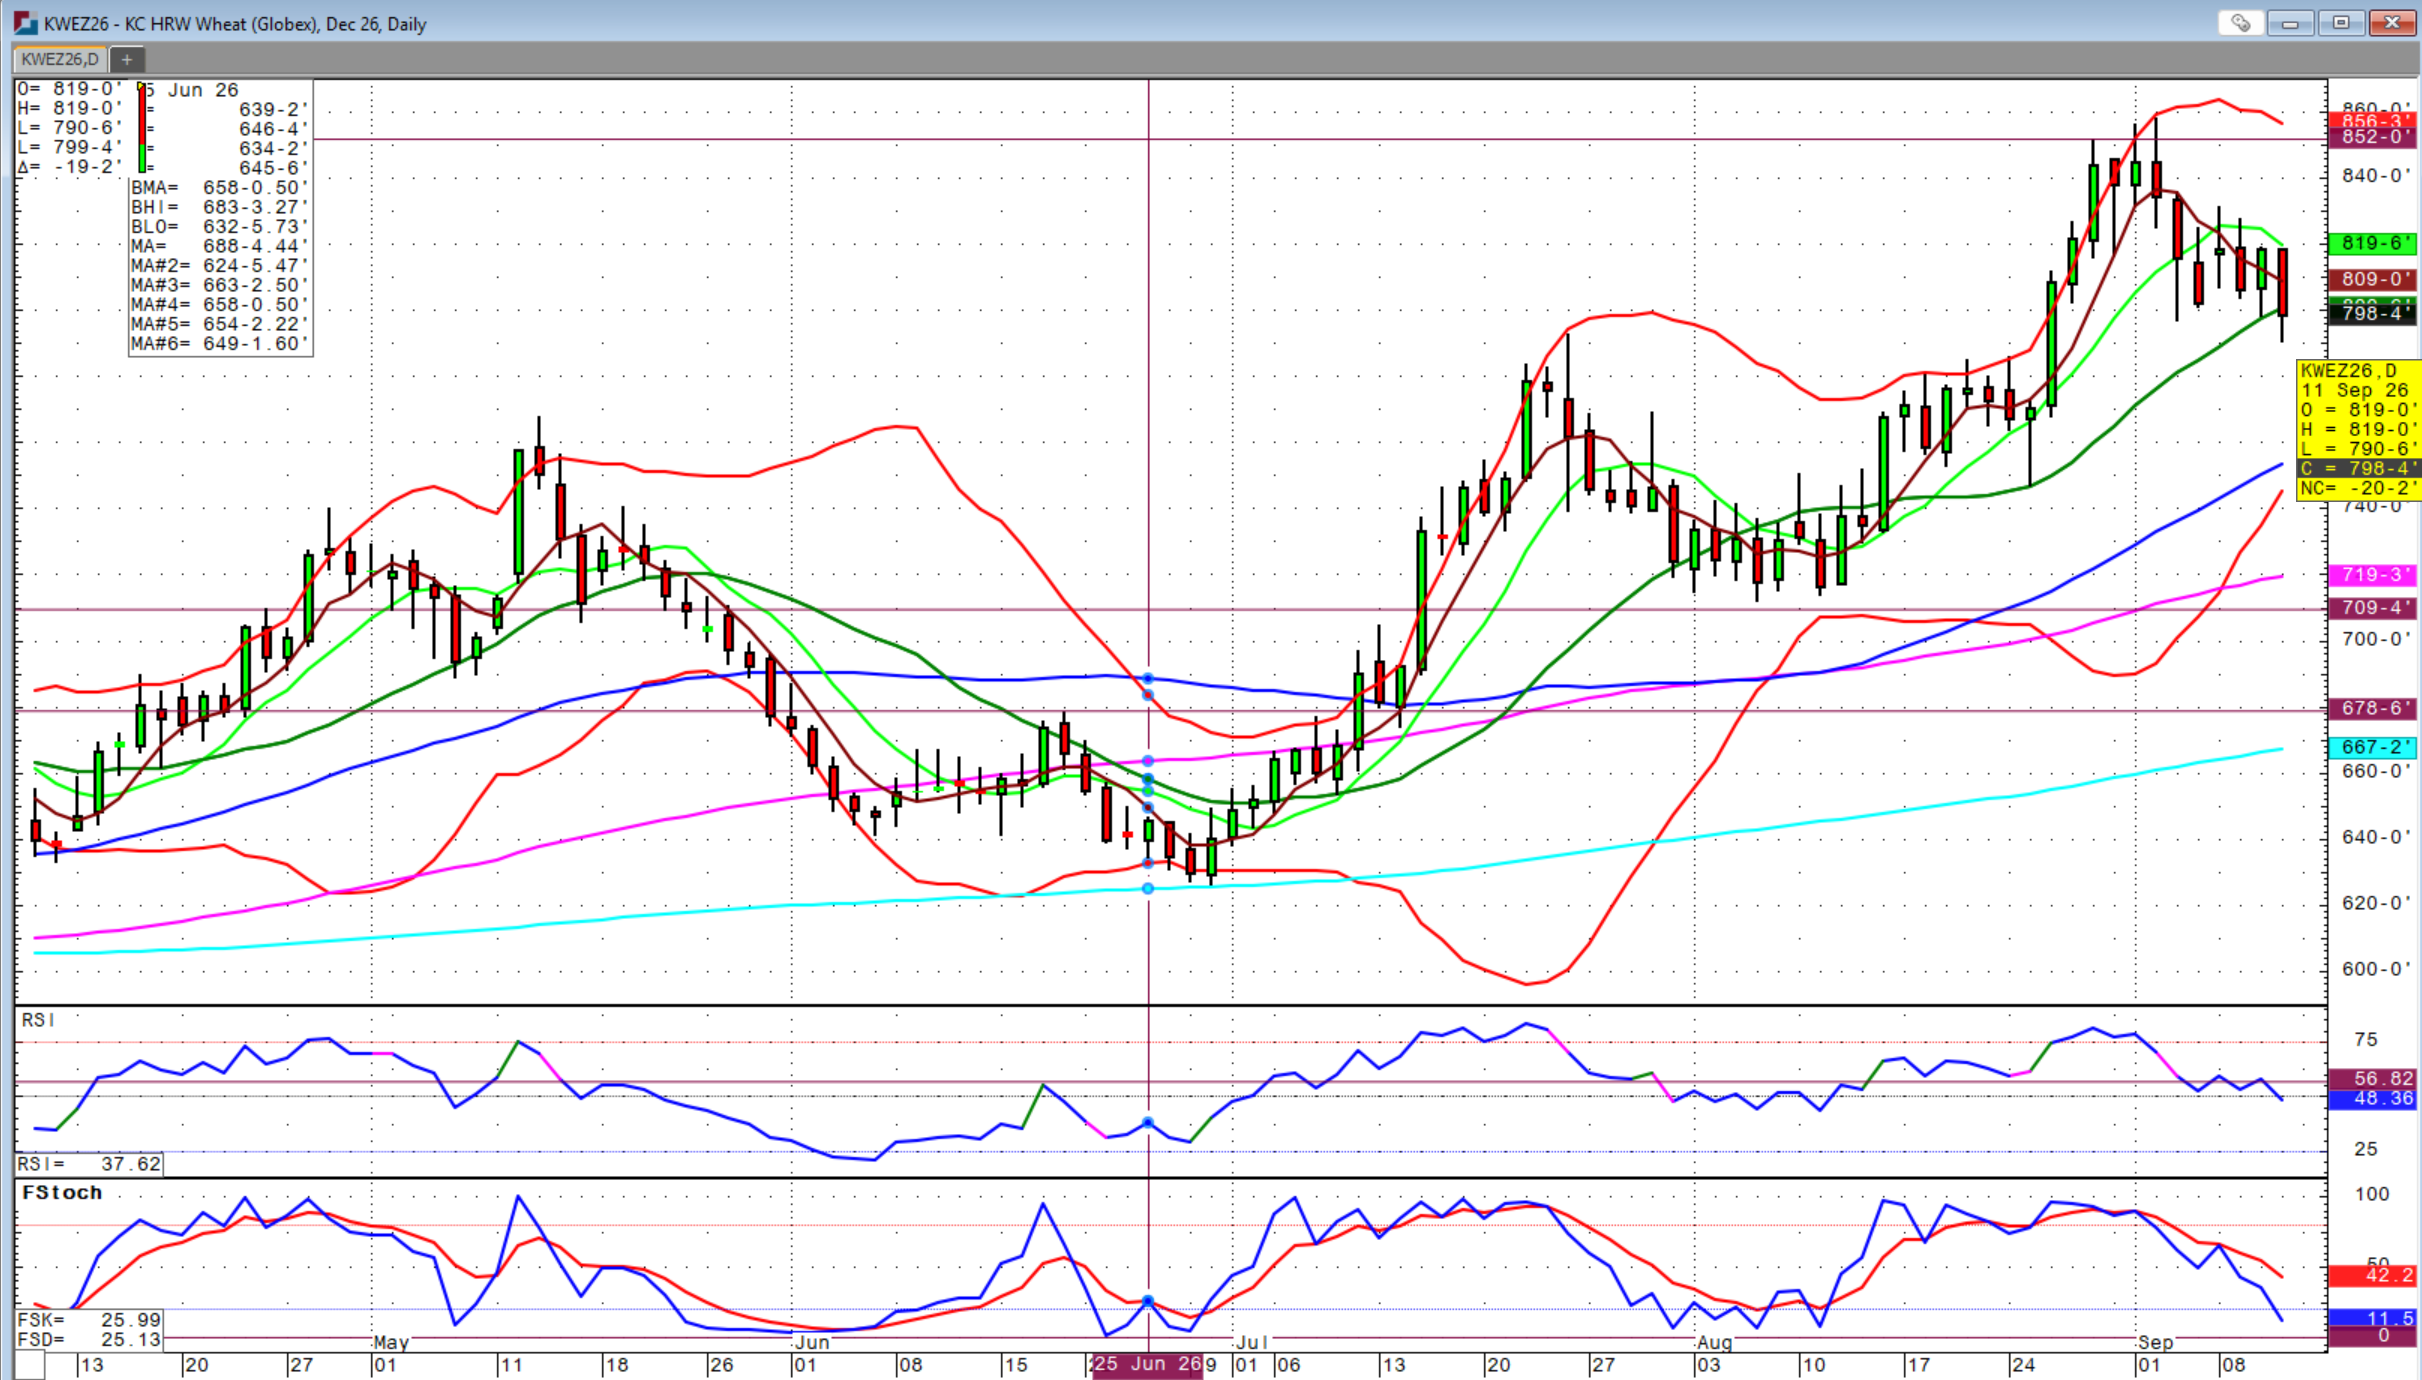
The action in the soybean chart looked weak while the corn chart was less determinant. The wheat market was also lower on the day and weak into the close, but finished right at the 20-day moving average and just above the prior day’s low.
Russia’s President Putin again said on Friday that he would be open to peace talks just as he did last weekend that dropped the wheat market, but we saw how that turned out with immediate Russian attacks on Ukraine after the American delegation left Kyiv. Both the Black Sea and Hormuz situation are extremely unpredictable and volatile and highly impactful on commodity markets.
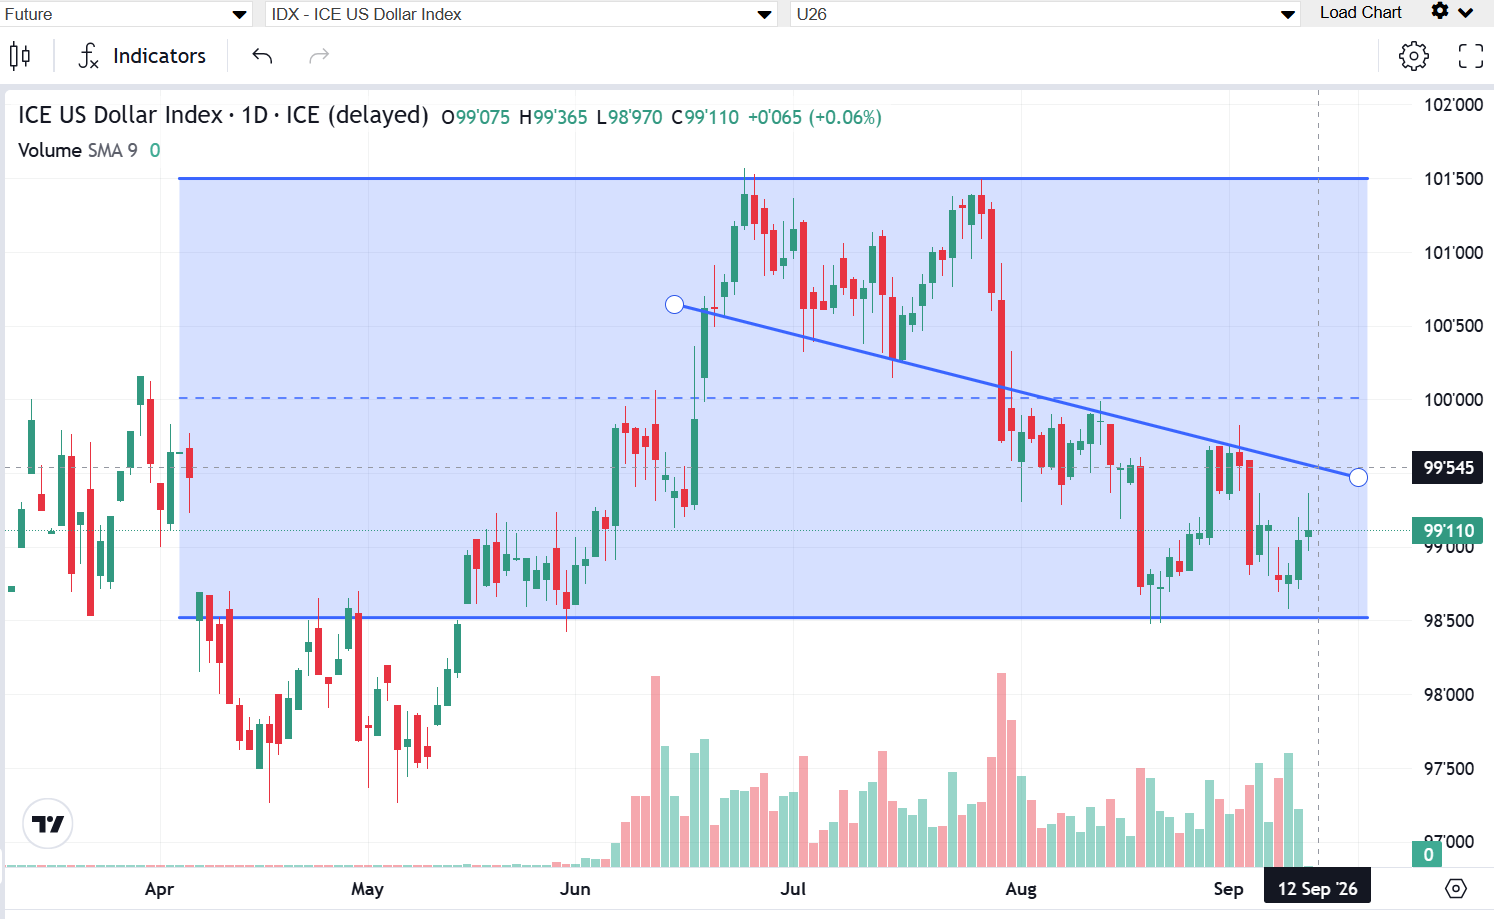
If US interest rates increase this next week like the EU interest rates did this week, the US dollar could increase and create a headwind for commodities. Just be aware of this as I sense the bullish sentiments in the commodity markets are extreme as is the long position of managed money that can turn quickly with a trigger.
Geopolitical rallies are always tricky as they too can change in an instant. As the US mid-term elections approach, pronouncements are becoming wilder by the day. President Trump made several of those this week, which were borderline ridiculous if not exactly that. Promising payouts to voters is not how we do things here nor can our country afford it and such spending would fuel higher inflation.
The Trump Administration has also not done any favors for the cattle rancher nor the cattle complex in recent weeks dare I say years. Finally, the cattle futures are turning around after the news cycle could not get any more negative. However, it has cost the US cattle industry a lot of money and unknown anxiety.
Cattlemen have been caused insurmountable stress from the precipitous drop in cattle futures since late June. So much so that I’m sure many producers have been sucked in to adding protection at these lower and likely, negative margin levels. While it has been tense, I have cautioned my clients to tread carefully, but not lock in these lower levels.
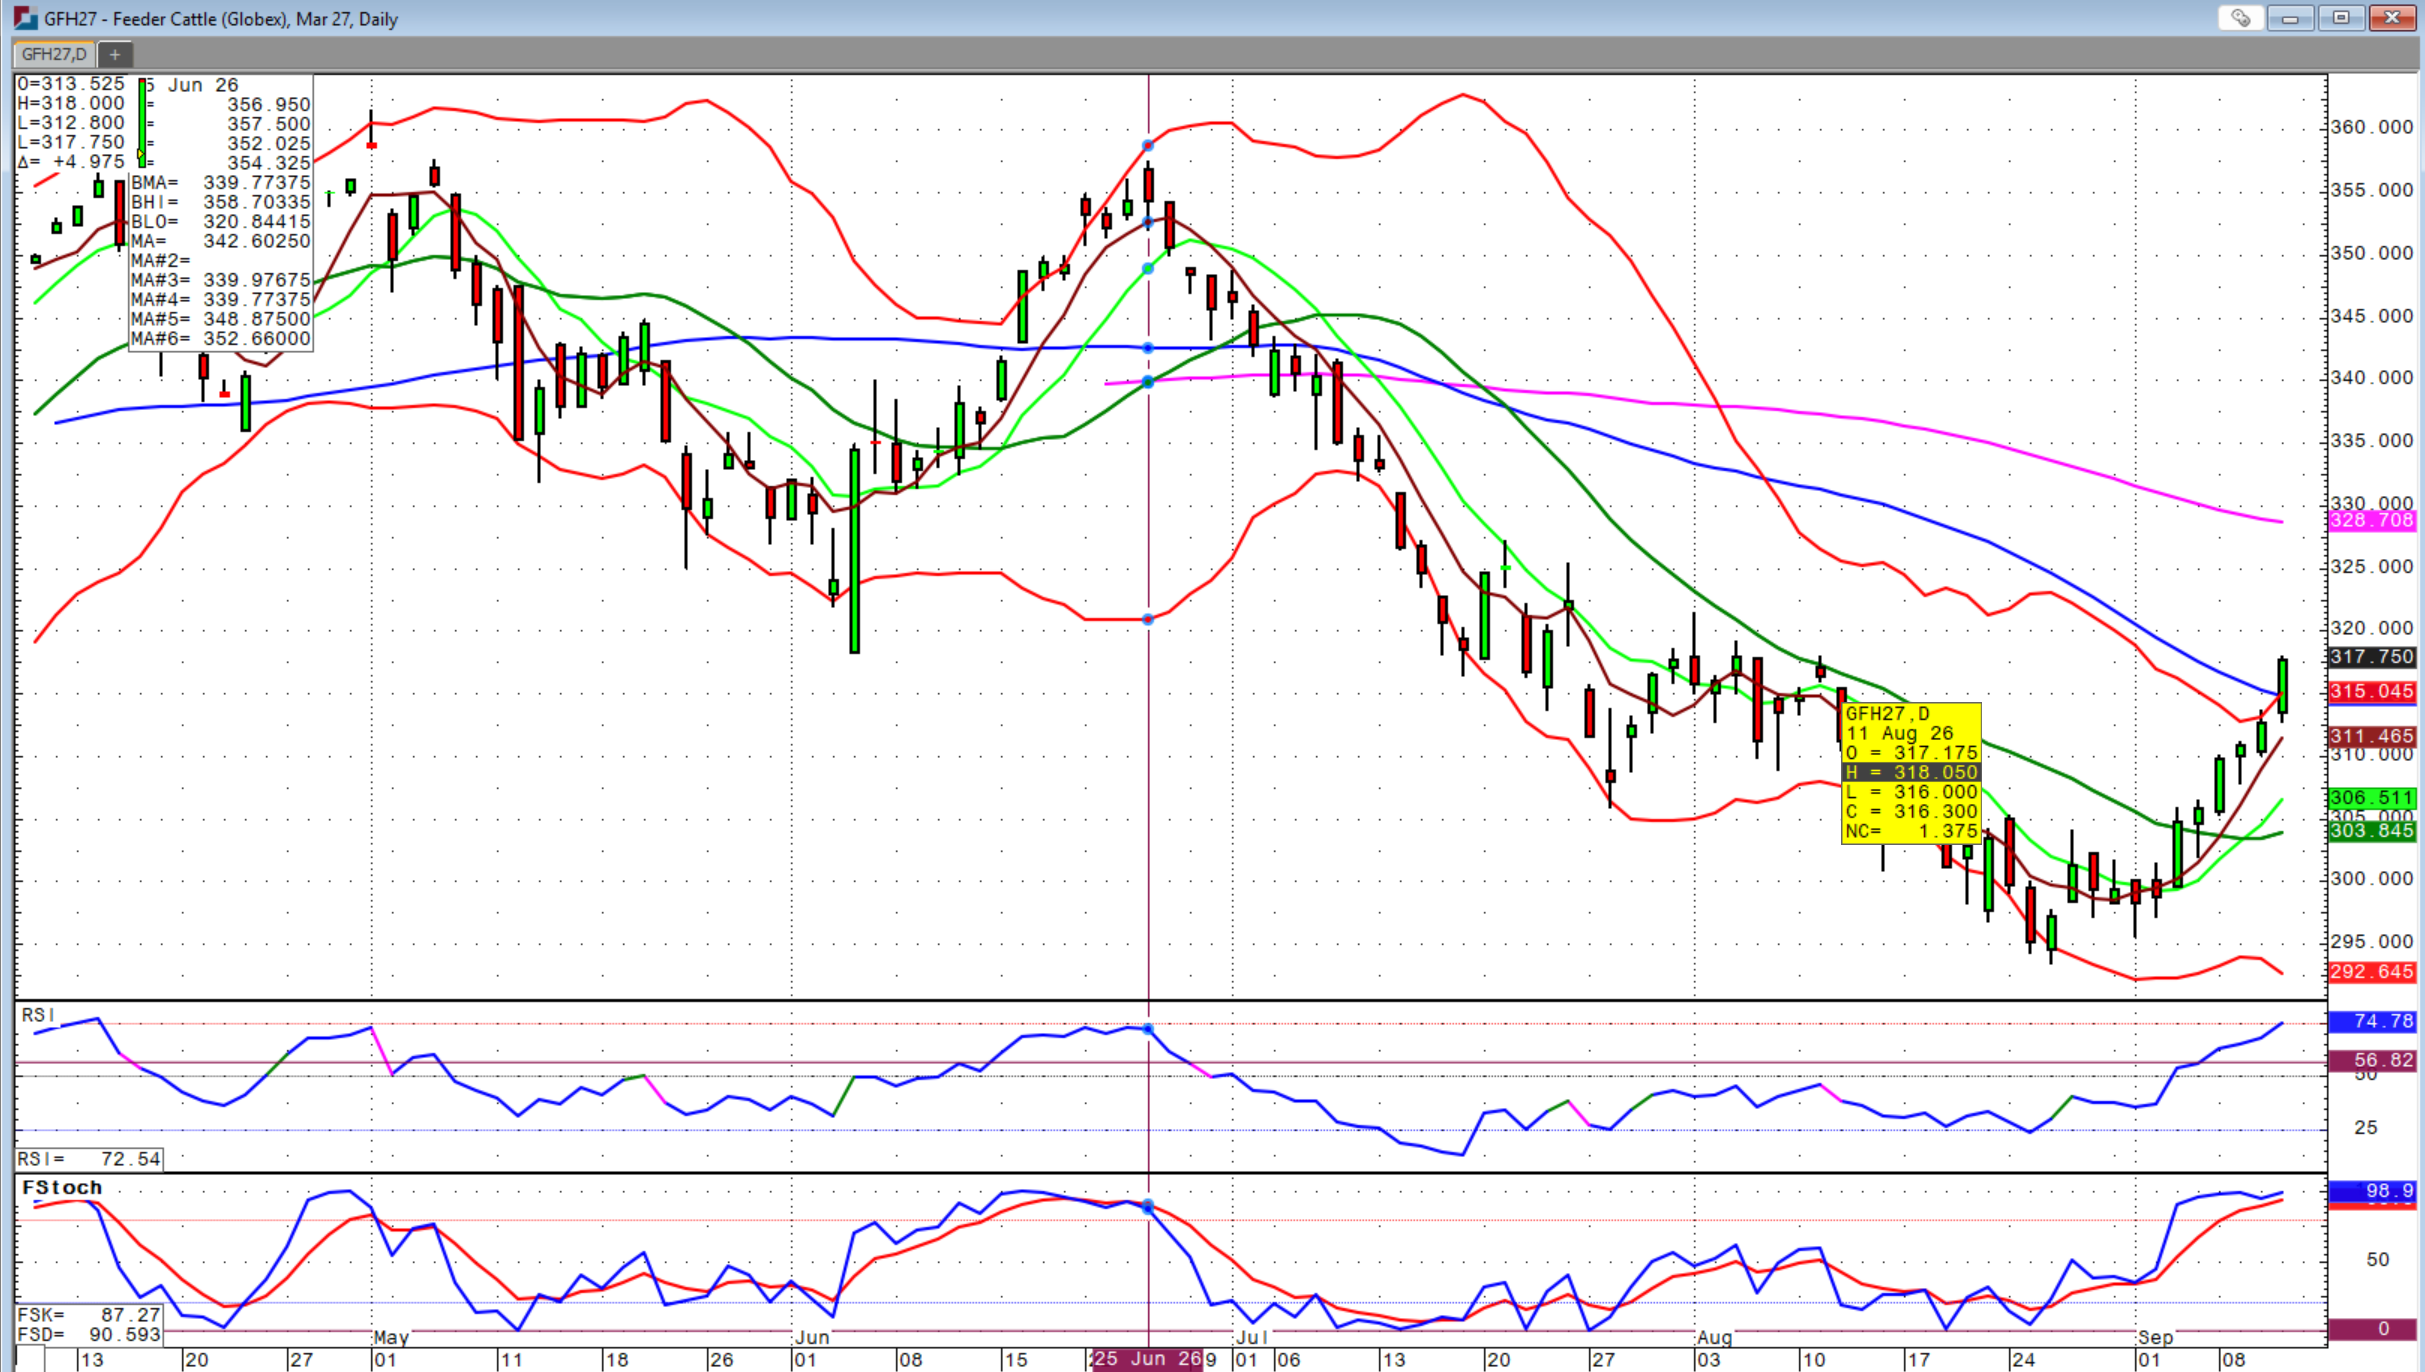
At the same time, I have advised clients who have had to sell cattle at these levels to re-enter the market on the upside with call options or long futures. That has worked out very well. While we will still have setbacks in the cattle market from time-to-time, I believe the momentum is shifting.
The holiday season is approaching albeit not just yet and Cargill’s Fort Morgan facility is back operating and demand will begin to steady and increase in the coming months with little relief on the supply side even with Trump’s supposed import of ground beef. Many of the feeder and live cattle futures contracts reached the 50-day moving averages in an incredible recovery week.
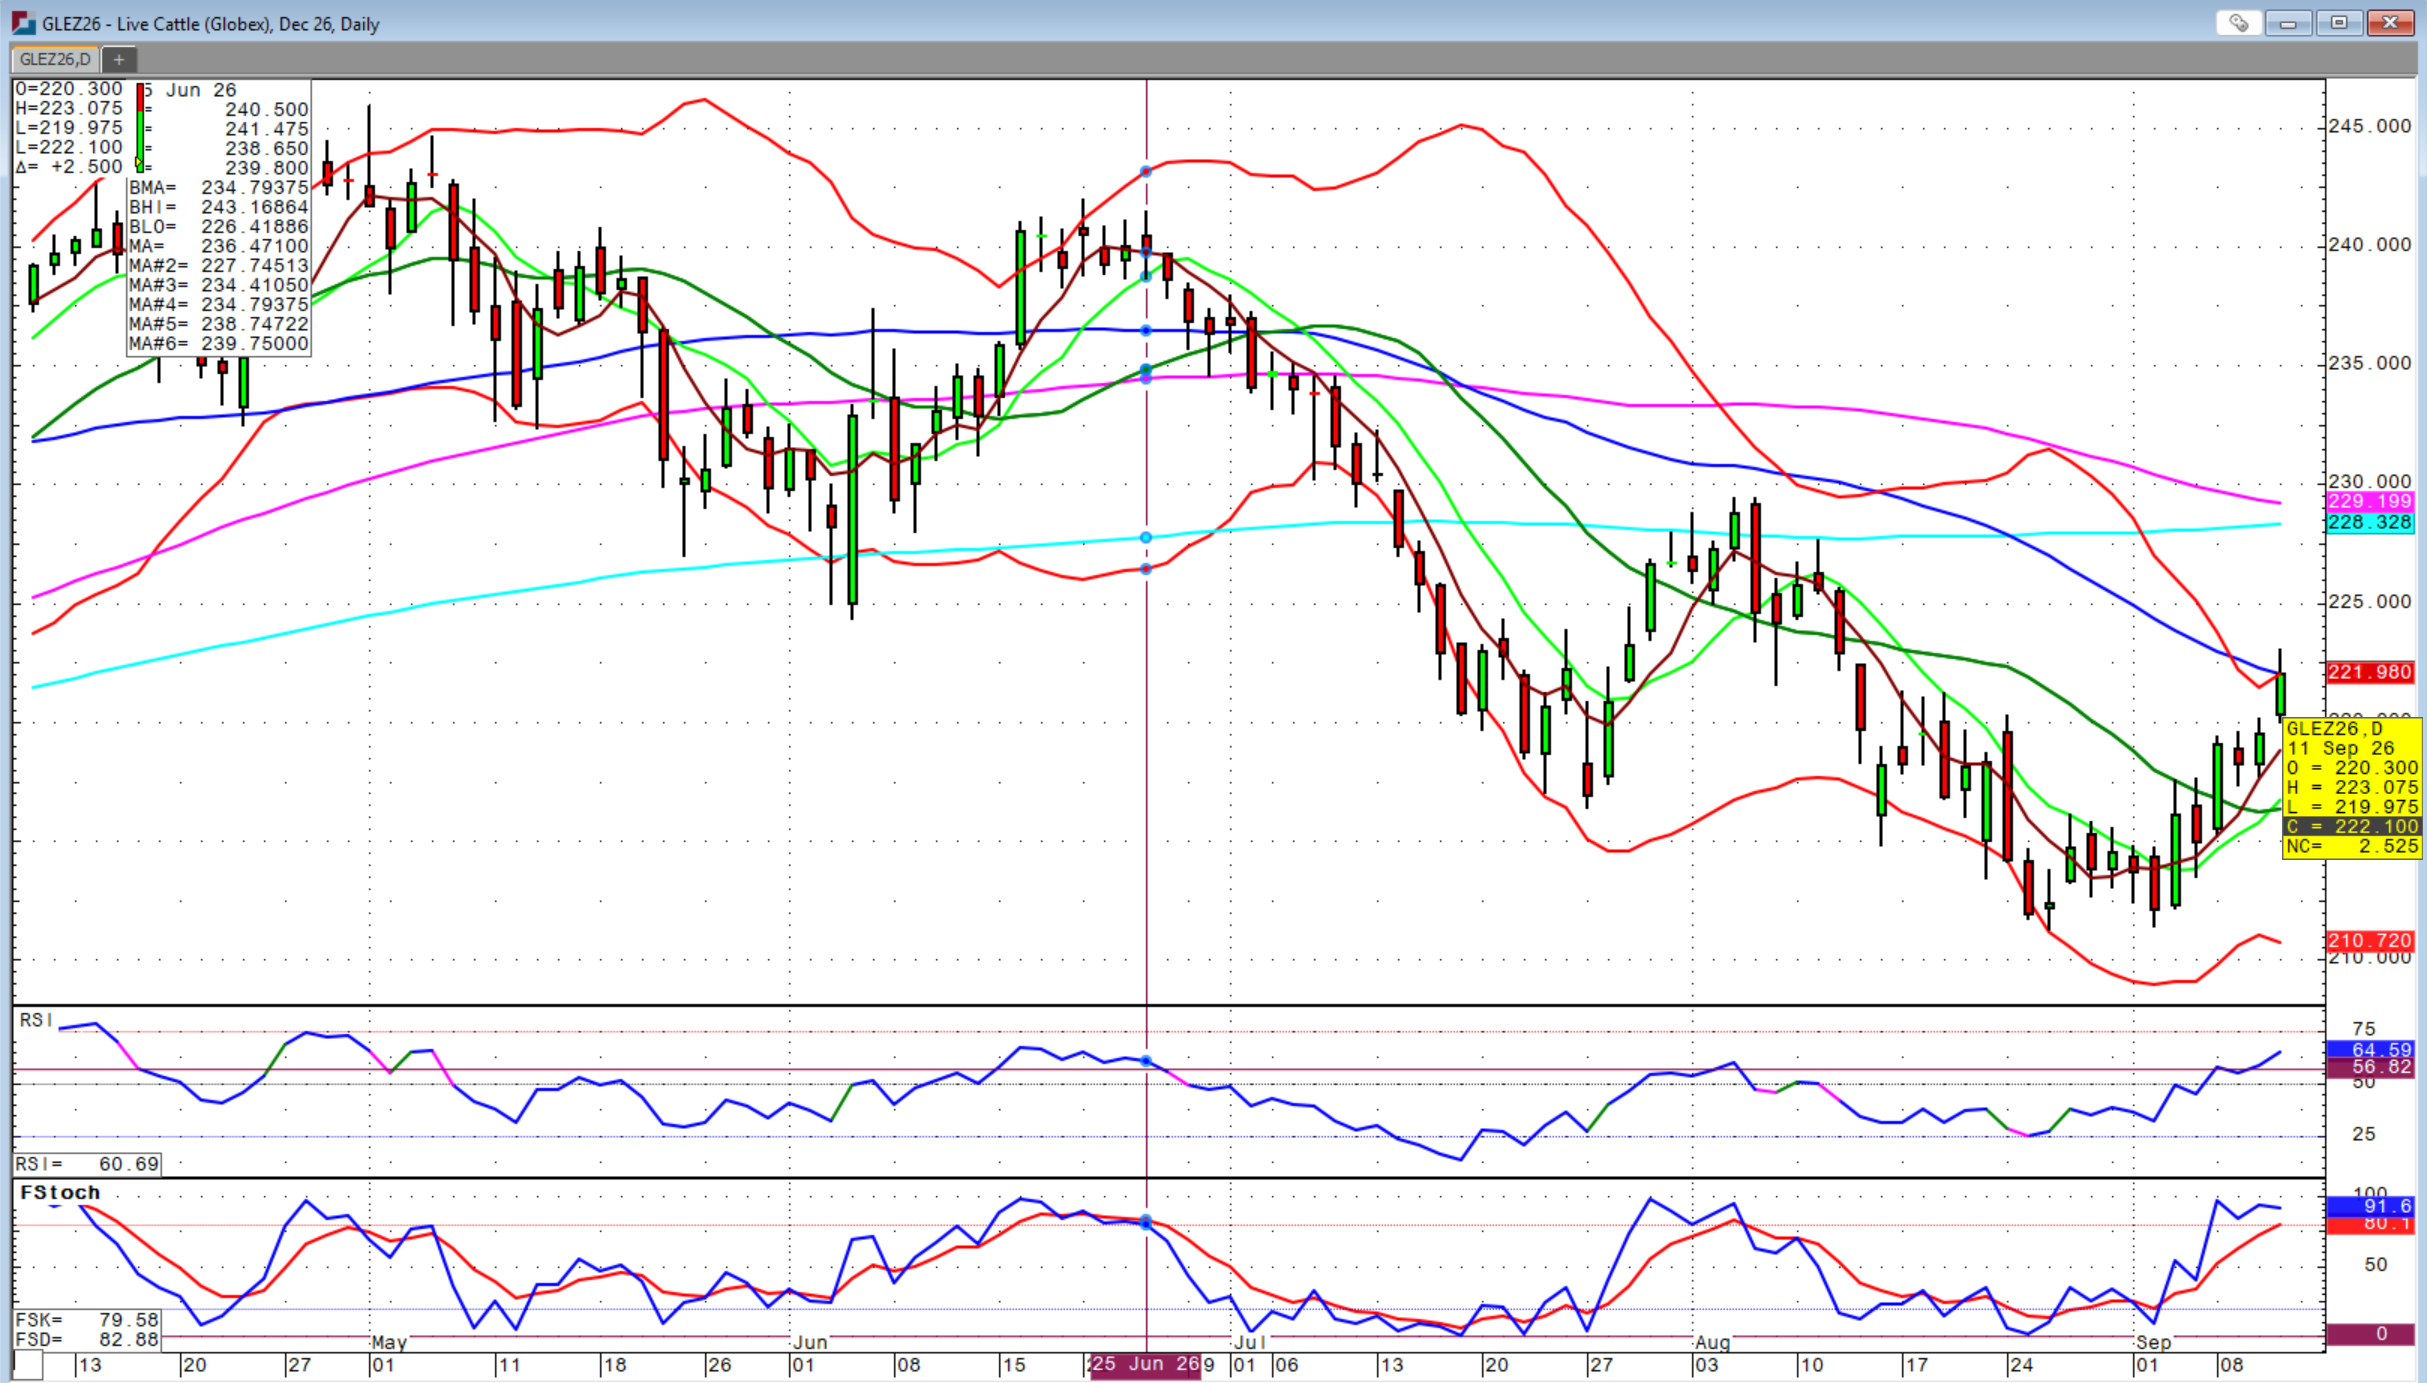
If the grain rally continues to stall here, I think there could be more upside in the cattle complex. This is a huge sigh of relief to many cattlemen with high priced cattle purchased and raised in the midst of a sizeable setback in the markets over the past two months. I believe we could see another $10 per cwt higher in both feeder and live cattle futures.
Sidwell Strategies is the one-stop shop to protect cattle with futures, puts, LRP or a combination of all, which is probably the best strategy overall. If you’re ready to trade commodity markets, give me a call at (580) 232-2272 or stop by my office to get your account set up and discuss risk management and marketing solutions to pursue your objectives. Self-trading accounts are also available. It is never too late to start and there is no operation too small to get a risk management and marketing plan in place.
Wishing everyone a successful trading week! Let us know if you'd like to join our daily market price and commentary text messages to stay informed!
Brady Sidwell is a Series 3 Licensed Commodity Futures Broker and Principal of Sidwell Strategies. Open your Trading Account with Sidwell Strategies at https://portal.stonex.com/prefill/index/BradySidwellU52F112P. Contact us at (580) 232-2272 or at trade@sidwellstrategies.com.
Futures and Options trading involves the risk of loss and may not be suitable for all investors. Review full disclaimer at https://www.sidwellstrategies.com/fccp-disclaimer-21951.