


Southern (SO) Could Be 14% Undervalued On Its Power Demand Growth Story
Southern (SO) continues to attract attention as investors reassess the utility after a choppy stretch, with the stock down about 6% over the past month and roughly 7% in the past three months.
Over the past year Southern has delivered a slightly negative total shareholder return of 2.4%, even though the share price is close to flat year to date. The latest quote at US$87.17 now sits on top of a much stronger 3 and 5 year total return record, which hints that recent weakness looks more like cooling momentum than a sharp break in the longer term story.
Compare Southern's recent cooling momentum with other potential breakouts and defensives in the sector by scanning our curated list of 11 resilient stocks with low risk scores.
Southern looks like a solid regulated utility on the surface, yet the recent pullback and US$87.17 share price raise a sharper question. Are you paying a fair price for that stability today?
Most Popular Narrative: 14% Undervalued
On the widely followed narrative, Southern’s fair value sits at $101.34 against the latest $87.17 close, which suggests the stock trades at a discount and puts the focus squarely on how future earnings are expected to develop.
The expansion of large-scale electrification projects, including hyperscaler data centers and industrial developments, across Alabama, Georgia, and Mississippi is materially increasing Southern's load outlook. This is resulting in regulatory approvals and filings for up to 10 GW of new generation and $13 billion of incremental capital investment, which is driving long-term earnings and rate base growth.
Want to see what sits behind that earnings push? The narrative leans on rising power demand, higher margins and a premium future P/E to back that fair value.
Result: Fair Value of $101.34 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Southern’s heavier capital plan and equity issuance, together with dependence on supportive regulators, could pressure earnings per share and dilute that undervaluation story.
Find out about the key risks to this Southern narrative.
Another View On Southern’s Valuation
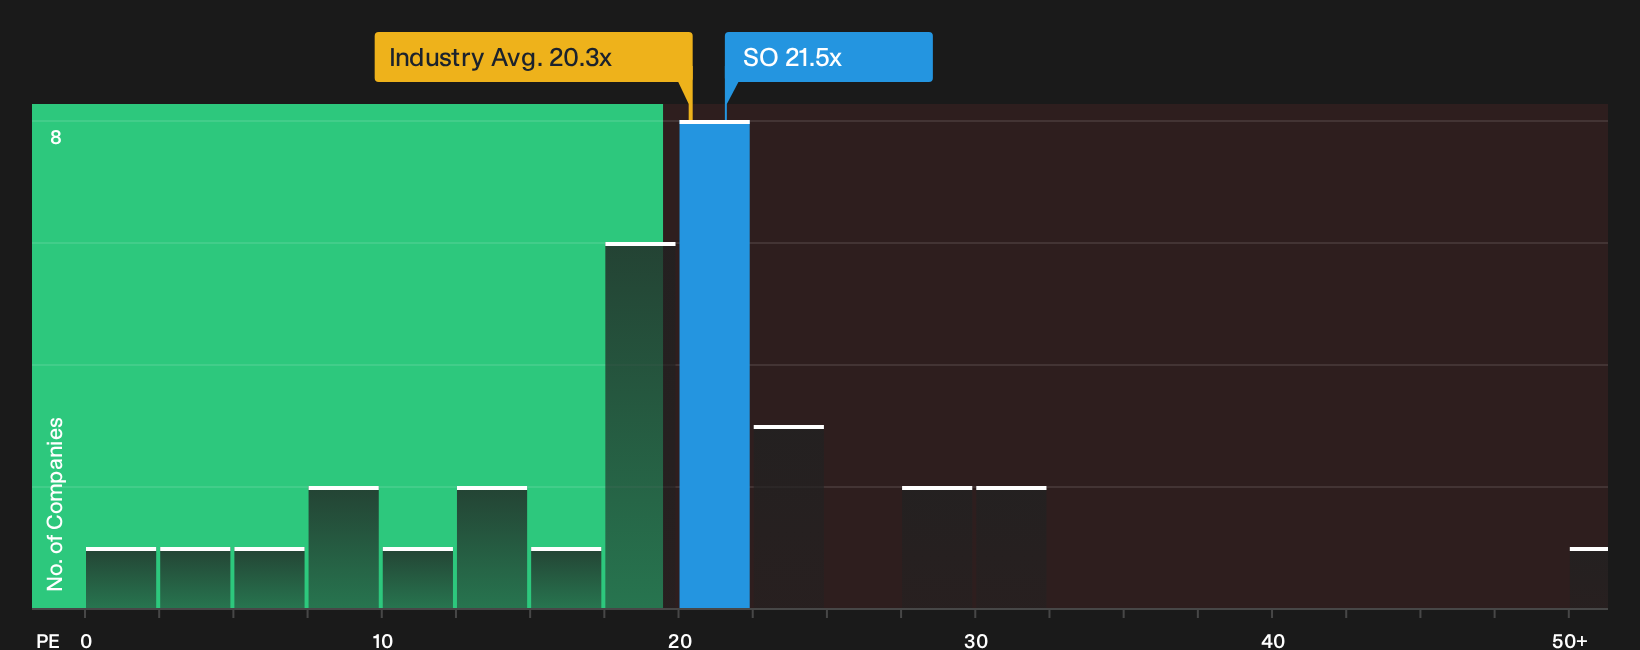
That 14% discount to fair value paints one picture. The basic earnings multiple tells a different story. Southern trades on a P/E of 21.5x, which is richer than the US Electric Utilities average at 20.3x, even though its own fair ratio is estimated at 23.6x.
This means the share price already prices in a premium versus the wider sector and peers, while still sitting below where the fair ratio suggests the market could move. The practical question for you is whether that gap feels like limited upside or a cushion against further disappointment.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Southern can feel messy, yet decisions rarely wait for perfect clarity. Pressure test the data yourself and weigh both sides. To frame that view with more structure, review our breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Southern?
If Southern feels interesting but not enough on its own, widen your opportunity set with a few focused stock ideas sourced from our screeners.
- Target potential mispricing by reviewing companies that currently look cheap on quality and valuation through our 32 high quality undervalued stocks.
- Build a steadier income base by zeroing in on high yield payers that aim to keep distributions resilient using the 6 dividend fortresses.
- Tighten your risk profile by focusing on businesses with stronger finances and cleaner balance sheets through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com