


Lululemon Athletica (LULU) Could Be 39% Undervalued On Its Cash Flow Narrative
Lululemon Athletica (LULU) just put fresh numbers on the table, reporting second quarter results and cutting its 2026 outlook as revenue and earnings softened versus last year.
At around US$98.97, lululemon athletica’s recent slide has been steep, with a year-to-date share price return down 53.05% and a 1-year total shareholder return down 38.09%. This signals fading momentum even after this week’s 2.16% one-day share price rebound following the guidance cut, CEO transition headlines and ongoing debate around the turnaround story.
Spot fresh opportunities alongside lululemon athletica’s reset by scanning our handpicked 32 high quality undervalued stocks list, which combines resilient cash flows with balance sheets built to handle tougher conditions.Lululemon athletica now trades near eight year lows after its reset, so the key question is whether most of the pain is already priced in or if the upside was largely realized years ago.
Most Popular Narrative: 38.8% Undervalued
According to one widely followed valuation thesis, lululemon athletica screens as materially mispriced, with that framework putting fair value well above the recent $98.97 close.
The company generated $10.32 billion in Free Cash Flow to Equity against $7.2 billion in Net Income. This surplus of cash over accounting earnings speaks to the exceptional quality of their revenue.
Read the complete narrative. Read the complete narrative.
The fair value call from HarishPK leans heavily on rich cash generation, strong profitability and a specific view on future margins and growth. It explores which cash flow paths, discount rate and profitability assumptions support a fair value near $160 per share while the market prices lululemon athletica under $100.
Result: Fair Value of $161.80 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, a prolonged revenue and net income decline, combined with further weakness in key Americas markets, could quickly challenge the bullish lululemon athletica narrative.
Find out about the key risks to this lululemon athletica narrative.
Another View: SWS DCF Model Flags Overvaluation
The user narrative leans on a custom cash flow model that points to lululemon athletica being undervalued, but the SWS DCF model tells a different story. At $98.97, the share price sits above our DCF estimate of $85.95, which implies the stock screens as overvalued on this framework.
This gap between an $85.95 DCF value and a $161.80 fair value from the user model raises a practical question for investors: Which set of assumptions around future cash flows feels more realistic to you, and how much model risk are you willing to live with when sizing a position?
Look into how the SWS DCF model arrives at its fair value.
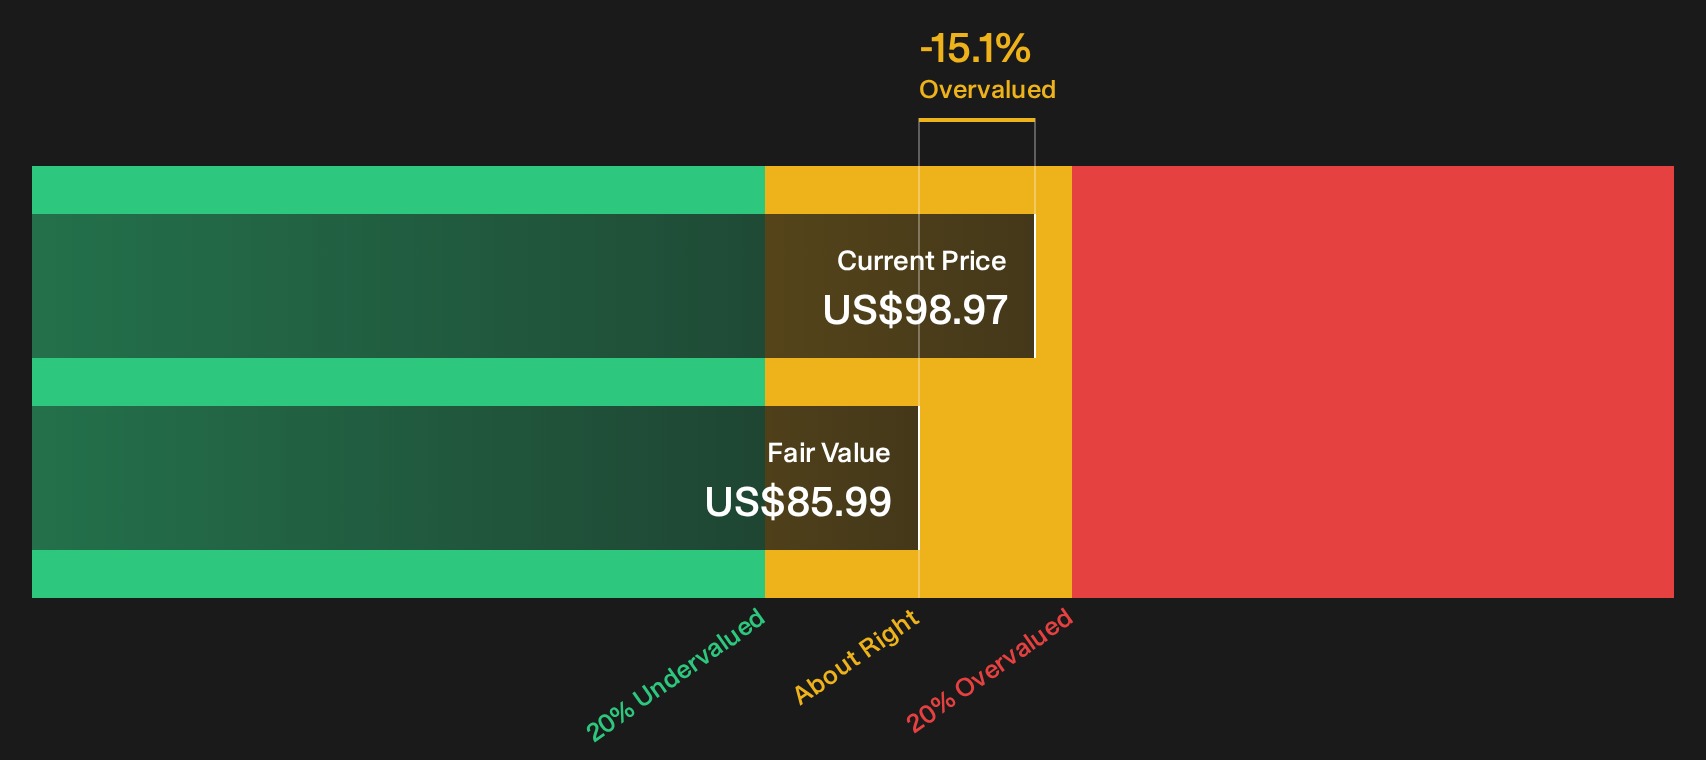
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out lululemon athletica for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on lululemon athletica after this reset are clear, so move quickly, review the numbers yourself and weigh both the upside and the threats by checking the 2 key rewards and 1 important warning sign.
Looking for more lululemon athletica investment ideas?
If lululemon athletica has your attention, do not stop here. Cast a wider net now so you do not miss stronger risk reward setups.
- Target potential mispricings by scanning companies that look cheap on quality and valuation using the 32 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can better withstand tough conditions and funding stress.
- Spot future leaders early by checking a curated pool of 15 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com