


Drone Engine Supply Chain Stocks Investors Are Watching Beyond China
War in Ukraine has quietly turned into a live stress test for the global drone and propulsion supply chain, and capital is paying attention. Faster, cheaper jet-powered drones and tighter export controls are reshaping where money can actually flow. That shift creates both openings and tripwires for your portfolio. This article unpacks three stocks exposed to these developments and shows how each might fit, or not fit, into your own defence-risk playbook.
The three stocks below are just a small sample, and the full screen surfaced 54 more non Chinese propulsion and drone engine suppliers with equally detailed stories that are not covered here. To identify and analyze the highest conviction angles in this theme, head straight to the Non-Chinese Aerospace Propulsion and Drone-Engine Suppliers screener.
Hexcel (HXL)
Overview: Hexcel develops advanced lightweight composite materials and structures used across commercial aerospace, defense, space and industrial platforms, including propulsion related components.
Operations: Hexcel generates about US$1.7b in revenue from Composite Materials and US$406 million from Engineered Products, partly offset by corporate costs.
Market Cap: US$7.0b
Hexcel matters for this propulsion-focused screen because its carbon fiber composites and engineered structures sit directly in the airflow around engines and unmanned platforms, putting the business at the material level of any shift toward lighter, longer-range drones.
"Rising global defense spending, especially across NATO members and key international markets, is driving orders for a new generation of military aircraft and autonomous systems. These platforms have increasing advanced composite content, which supports steady revenue growth and enhanced earnings visibility for Hexcel's defense portfolio."
What happens to Hexcel's margin story if one quiet pressure on pricing power and contract terms starts to bite more than expected?
If that pressure is building, you need the full narrative for Hexcel to see whether rising defense demand is masking contract risk or setting Hexcel up for a stronger cycle.

Albany International (AIN)
Overview: Albany International makes advanced machine clothing and 3D woven composite parts, including engine and nacelle components for aerospace propulsion platforms.
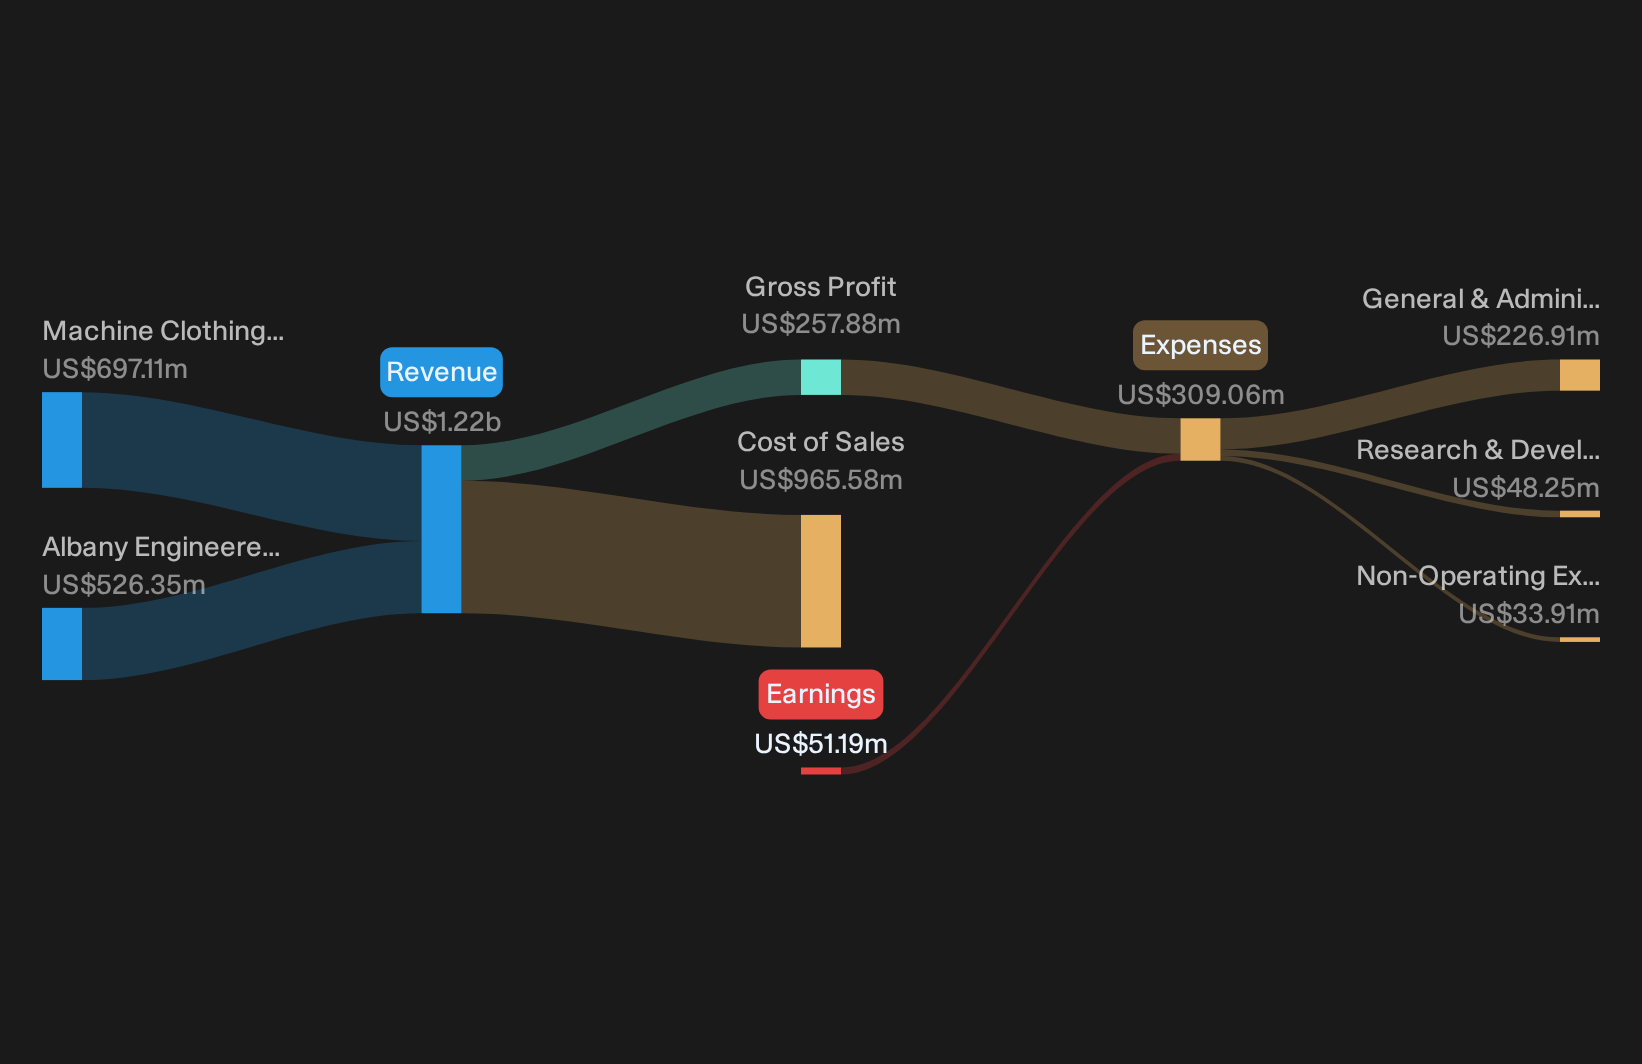
Operations: Albany International generates about US$697 million from Machine Clothing and US$526 million from Albany Engineered Composites revenue each year.
Market Cap: US$1.7b
Albany International fits this propulsion screen because its engineered composites feed directly into engine and nacelle hardware for jets, missiles and UAVs at a moment when non Chinese supply options are becoming more valuable.
"Operational improvements, innovative composites, and a focus on sustainability are important factors for margins and market share in aerospace and industrial sectors."
What really matters next is how one unresolved pressure on future defense program volumes and contract terms shapes that margin story.
That unresolved pressure is exactly what the full narrative for Albany International unpacks, separating transient contract noise from an accelerating Albany International defence story that many are still overlooking.
DEUTZ (XTRA:DEZ)
Overview: DEUTZ develops and services diesel, gas, hydrogen and electric drive systems that power machinery and defense platforms across global end markets.
Operations: DEUTZ currently discloses limited segment detail, but reports €591 million from the Americas and €140.6 million from China.
Market Cap: €2.0b
For this screener, DEUTZ matters because engine design is the core product, and that know how can extend into auxiliary propulsion and power units for unmanned systems that need trusted, non Chinese suppliers.
"The company's accelerating transformation from an engine pure play to a diversified solutions provider, especially via strategic M&A in electrification, energy systems, and defense, is intended to align it with the global shift toward decarbonization and rising demand for low-emission/hybrid powertrains."
What are the implications for DEUTZ's propulsion opportunity if one fast moving defense oriented powertrain program scales faster than its current balance sheet comfort zone?
If that tension is on your radar, the full narrative for DEUTZ outlines how DEUTZ's defence push, capital needs and propulsion upside could be accelerating far faster than headlines suggest.

Seeking Alternatives Before The Crowd Moves
Fresh themes gain momentum fast, and the most interesting breakouts rarely stay under the radar for long. Scan these curated ideas while it still matters, then act now.
- Spot early movers in under-covered sectors and track where institutional money could head next by scanning the 15 high quality undiscovered gems before the crowd catches on.
- Target resilient payers that aim to keep income streams flying even when sentiment drops by running the 6 dividend fortresses while yields still look compelling.
- Follow the backbone of the AI build out and watch where infrastructure capital might concentrate by working through the 89 AI infrastructure stocks before pricing reflects the full story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com