


Is Ducommun (DCO) Undervalued Following Its Defense Backlog Driven Growth Narrative?
Recent trading in Ducommun (DCO) has drawn attention after the stock moved about 3% in a day, while showing a gain over the past week but a decline over the past month.
Set against a 1-month share price return that is down 16.6%, Ducommun’s 90-day gain of 4.5% and year-to-date share price return of 78.4% point to momentum that has cooled recently but remains strong over a longer run. At the same time, the 1-year total shareholder return of 85.7% and 3-year total shareholder return of about 2.8x highlight how sentiment around the business has shifted over time as investors reassess both its growth potential and risk profile.
Scan other aerospace and defense manufacturers showing similar momentum and re-rating with a curated set of 15 high quality undiscovered gems that share Ducommun’s mix of growth and sector exposure.
Ducommun now trades below both its estimated fair value and the average analyst target, even after a sharp run and recent pullback. Is that discount-driven caution well placed or overly conservative on this story?
Most Popular Narrative: 18.5% Undervalued
On the latest numbers, Ducommun’s most followed narrative pegs fair value at $212 per share, compared with the recent close of $172.73. This sets up a valuation gap built on detailed growth and margin assumptions.
Elevated global defense spending and the replenishment of missile and radar inventories, highlighted by strong double-digit growth in both segments and a 30% increase in missile backlog, positions Ducommun to sustain and expand revenue as defense modernization accelerates over the next several years, with increasing program content and order activity.
Want to understand why this fair value leans on defense backlogs, higher margin mix, and a richer profit profile than today? The storyline hinges on how quickly earnings scale, what happens to margins as automation and consolidation kick in, and which revenue streams carry the heaviest weight in the long run.
This narrative applies an 8.19% discount rate to those projected cash flows and earnings, and it assumes Ducommun grows into a profit margin and valuation multiple that sit above current results but below the broader US aerospace and defense P/E used in the comparison. Analysts behind the narrative also build in expectations for share count creep and use that to arrive at a long term earnings per share figure that supports the $212 fair value anchor.
Result: Fair Value of $212 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, two pressure points could unsettle that Ducommun narrative: any shift in U.S. defense budgets and setbacks in facility consolidations or program transfers.
Find out about the key risks to this Ducommun narrative.
Another View on Ducommun’s Valuation
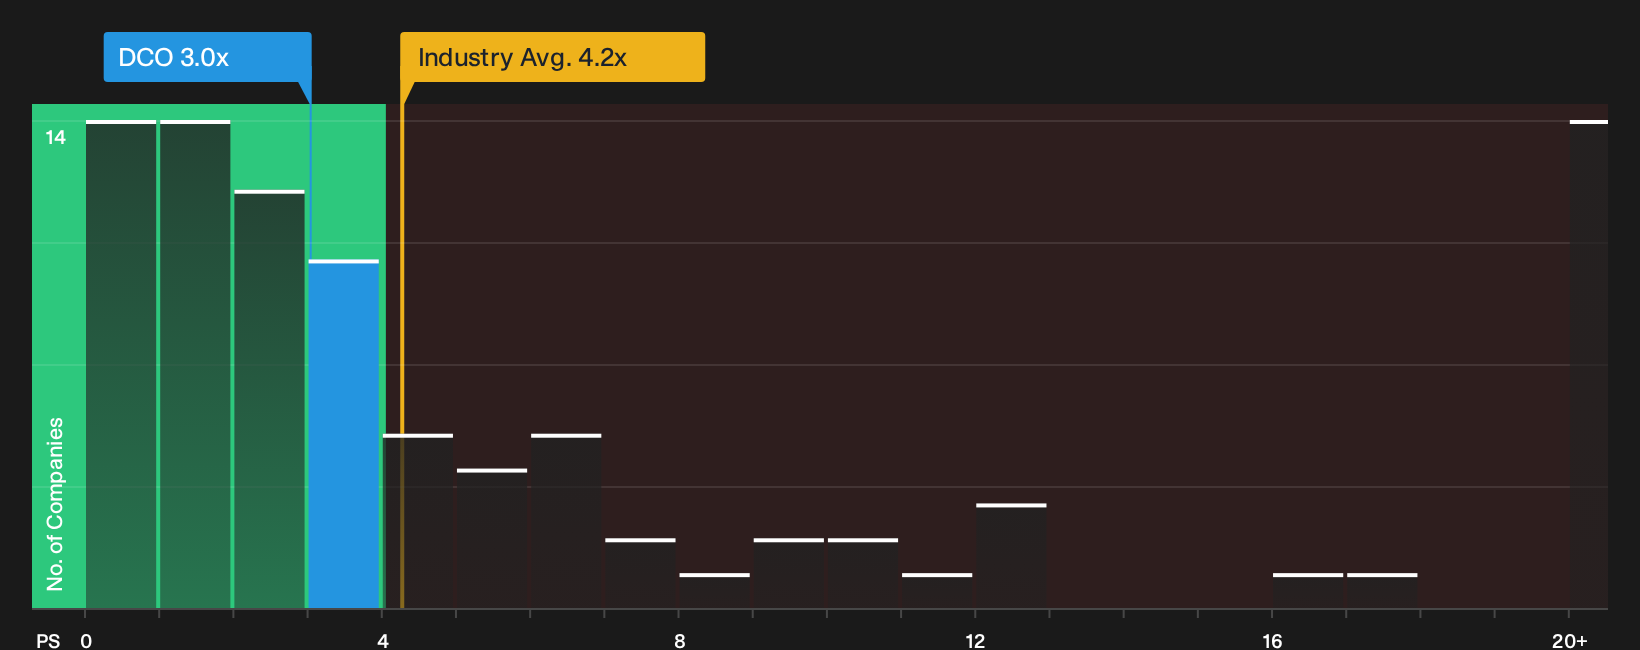
The first narrative leans on discounted future earnings for Ducommun. A simpler lens, the P/S ratio, tells a different story. The stock trades on roughly 3x sales, while the fair ratio is 1.4x and peers sit nearer 5.5x. That mix suggests both value risk and relative appeal. Which signal do you trust more?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Ducommun story so far? Treat this as a starting point, review the full data set promptly, and pressure test your own thesis by drilling into the 3 key rewards.
Looking for more Ducommun-sized ideas?
Do not stop your research with Ducommun. Use the Simply Wall Street Screener to quickly surface fresh ideas that match your risk tolerance and return goals.
- Target potential mispricings by reviewing a curated 32 high quality undervalued stocks that could offer compelling opportunities if the market is slow to adjust.
- Prioritize staying power by focusing on a list of solid balance sheet and fundamentals (23 results) that can better handle shocks and funding needs without constant dilution risk.
- Lean into resilience with a 11 resilient stocks with low risk scores that may help smooth portfolio swings and keep your holdings aligned with your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com