


3 AI Infrastructure Stocks Retail Investors Are Buying For Data Center Growth
AI safety debates are suddenly front-page news, with headline CEOs split between calls for a slowdown and an aggressive push to keep building. That clash is reshaping where money flows into the picks and shovels of AI infrastructure. If you care about where capital might cluster next, this is a moment to pay attention. The article will break down 3 stocks that appear positively exposed to this news shock.
The three examples in this article are only a sample, with the full screen surfacing 57 more large cap infrastructure players with equally compelling AI-adjacent stories that are not covered below. To see the whole field and start sorting for your own highest conviction ideas, head straight to the AI Infrastructure and Hardware Beneficiaries screener.
Hygon Information Technology (SHSE:688041)
Hygon Information Technology develops processors and accelerators for AI servers, data centers, and cloud infrastructure, with chips used in commercial workstations, industrial computing, and security applications. The business has a market cap of about CN¥535.6b, anchoring it firmly among large-cap AI hardware suppliers.
Hygon Information Technology provides direct exposure to the compute engines that power AI data centers. It is associated with high forecast revenue and earnings expansion that are aligned to GPU and accelerator build outs. The key question is how its premium valuation might react if a single growth assumption in that AI hardware cycle weakens.
If that premium ever starts to wobble, the 2 key rewards and 1 important major warning sign explains where expectations could either surprise on the upside or crack under pressure.

Cambricon Technologies (SHSE:688256)
Cambricon Technologies designs AI chips and accelerator cards that plug directly into the AI infrastructure build out, from cloud servers to edge devices. The Beijing based group has a market value of about CN¥653.4b, putting it among the larger listed AI hardware designers.
Cambricon Technologies gives investors exposure to the AI hardware supply chain, since its Siyuan accelerator cards and NeuWare software slot into data centers, cloud workloads, and edge inference where AI capex is being directed. The appeal is clear, although the degree to which customers keep paying up for that capability will depend on how one unseen pressure plays out.
That pressure point is unpacked in the 2 key rewards and 2 important warning signs (1 is major!) so you can see where Cambricon Technologies might be priced for either acceleration or disappointment.

Infineon Technologies (XTRA:IFX)
Infineon Technologies is a €75.9b semiconductor heavyweight whose power, sensor, and connectivity chips help run the electrical backbone of AI data centers and cloud hardware. The group generated €7.5b from Automotive, about €5.0b from Power & Sensor Systems, €1.7b from Green Industrial Power, and €1.4b from Connected Secure Systems.
Infineon Technologies brings something different to this AI infrastructure list, supplying the power and control chips that sit underneath GPUs rather than competing with them. This makes the following capital spending detail especially important.
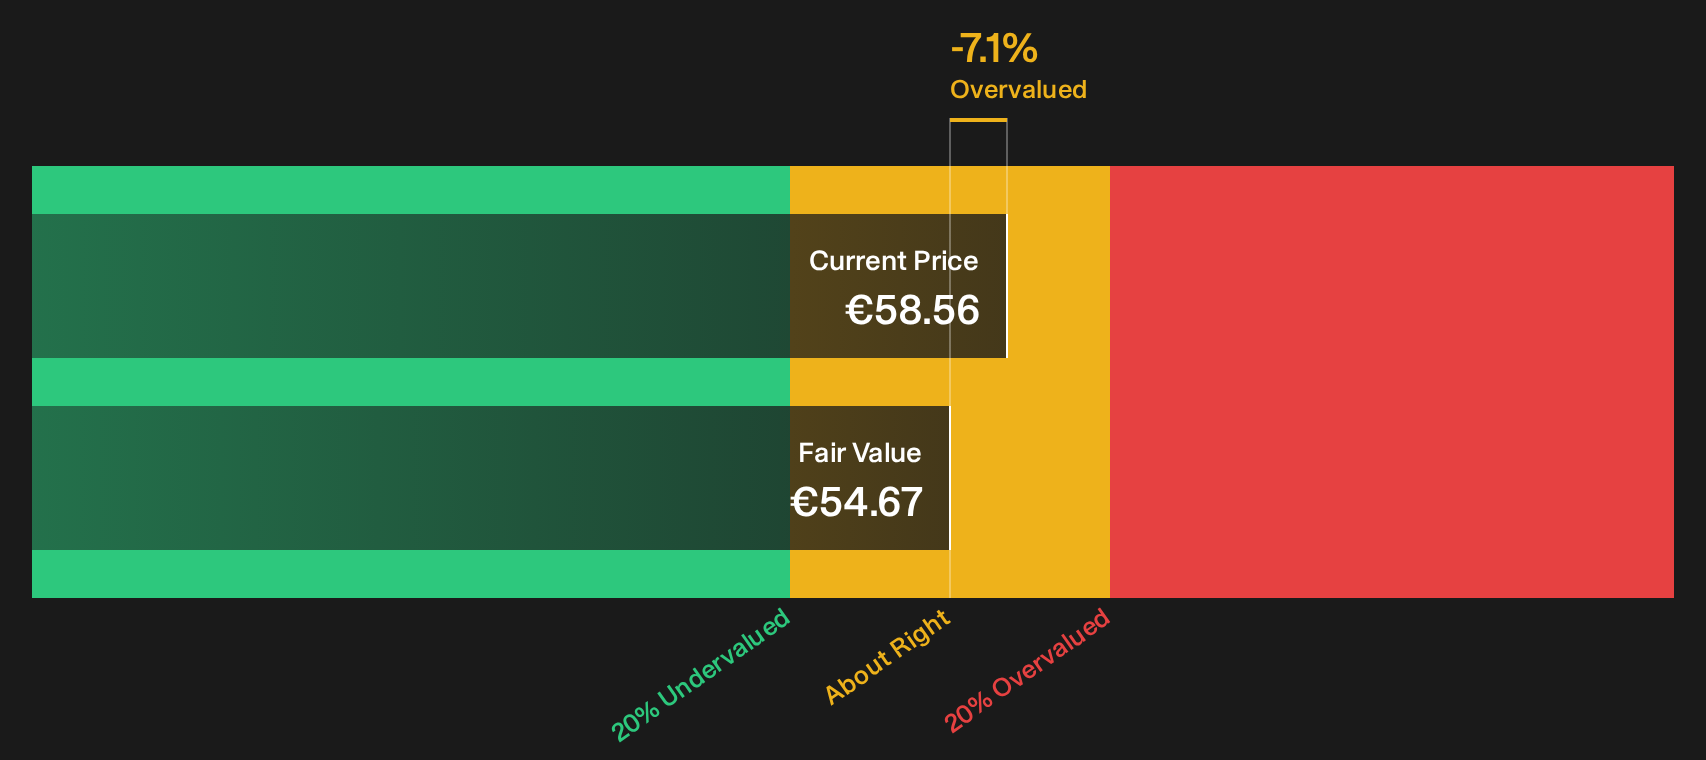
"Since IFX is investing heavily in new production capacity at Dresden: Smart Power Fab (start of construction 2023, invest €5b), an increase FCF to €3.0b is reasonable, and already considered in the “fair value”."
What happens to this story if a single assumption about the intensity and duration of AI data center demand quietly shifts?
That hinge point is exactly where the full narrative for Infineon Technologies shows how Infineon Technologies could see heavy capex, power electronics and AI demand decoupling reshape its risk reward profile.
Seeking Alternatives Before The Crowd Moves
Fresh opportunities move fast. Breakout themes gain momentum, prices start flying, and slow money gets caught chasing. Scan curated stock ideas under the radar for now and get in early.
- Spot potential momentum leaders early by running the 74 profitable AI stocks that aren't just burning cash while pricing dislocations still matter and before cash-generating AI plays get fully crowded.
- Pressure test your defensiveness, then rebalance around the 99 resilient stocks with low risk scores so you are not caught holding fragile stories when volatility picks up.
- Target compounding income streams by using the 161 dividend fortresses to zero in on payout heavy businesses that combine yield strength with solid underlying finances.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com