


Onex (TSX:ONEX) Could Be 17% Above Fair Value Following $26.5 Million Settlement
Onex (TSX:ONEX) is back in focus after a shareholder class action involving its role in the PowerSchool acquisition reached a proposed cash settlement of US$26.5 million, with court approval still pending.
Recent trading around Onex reflects that mix of legal overhang and longer track record. The share price is at CA$110.50 after a 1-day share price return of 2.64%, yet the year to date share price return is down 3.06% and the 1-year total shareholder return has declined 10.8%, even though the 3-year total shareholder return is up 34.93%. This suggests that long term holders have fared better than more recent buyers as momentum has faded in recent months.
Scan beyond Onex and see how other financial stocks are reacting to similar headline pressure with our hand picked 1 resilient stocks with low risk scores in the sector.
With Onex shares still below recent highs and a US$26.5 million settlement proposal on the table, the real issue now is whether the current price fairly reflects that legal risk and the underlying portfolio value.
Price-to-Earnings of 12.6x: Is it justified for Onex?
Onex trades on a P/E of 12.6x at a last close of CA$110.50, which points to a richer valuation than many Canadian capital markets peers.
The P/E ratio compares what investors pay today to the company’s current earnings, so a higher multiple often reflects expectations for steadier profit streams or superior deal making. For an alternative asset manager like Onex, that can also capture the value investors place on long term fee income, carried interest and the embedded gains inside its investment portfolio.
There is a split message in the recent numbers. ONEX has high quality earnings and net profit margins of 66.1% that are above last year, yet earnings have declined by 22.7% per year over the past 5 years and fell 8% over the last year. That pattern suggests the market is paying up for the quality and stability of the current profit base, even though the historical growth profile has been weak.
The comparison with peers makes the premium clear. ONEX is considered good value against a peer average P/E of 38.1x, but it is expensive versus the broader Canadian Capital Markets industry on 6.4x. That combination points to investors assigning Onex a middle ground valuation, richer than the sector as a whole but well below higher multiple peers that the data groups alongside it. See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 12.6x (ABOUT RIGHT)
Still, the unresolved PowerSchool class action and any shift in investor confidence around Onex’s P/E premium could quickly unsettle the current valuation story.
Find out about the key risks to this Onex narrative.
Another view on Onex using cash flows
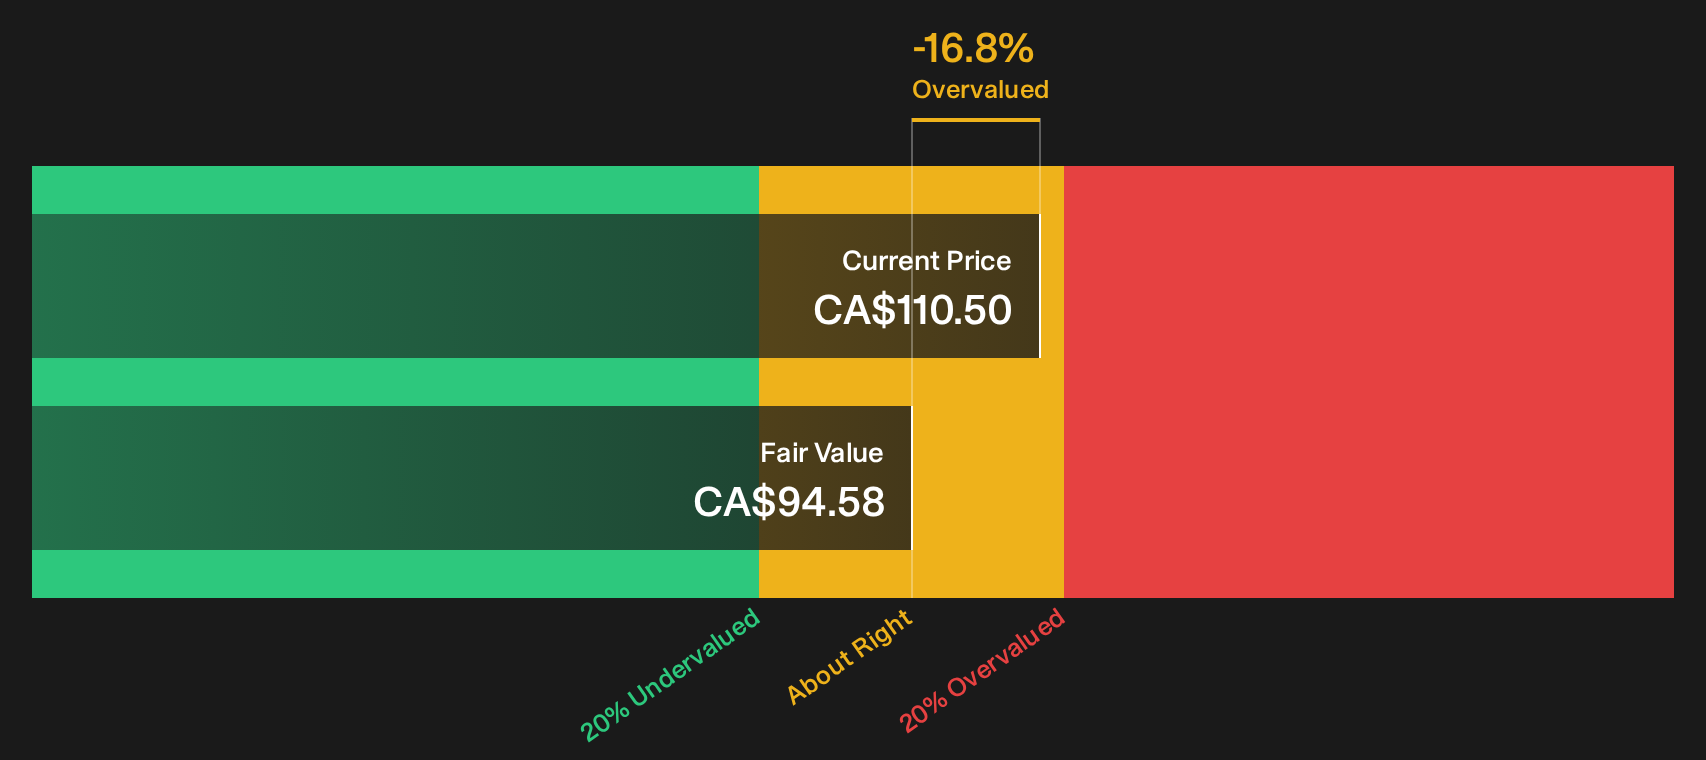
The P/E paints Onex as roughly fairly priced, but the SWS DCF model tells a different story. On that cash flow view, our estimate of fair value is CA$94.58 versus the current CA$110.50. That gap implies investors are paying a premium to the modeled stream of future cash flows.
This kind of disagreement between earnings based and cash flow based yardsticks can matter for you. It raises a simple question: is the extra price over the CA$94.58 DCF value a cushion built on conviction, or a margin of risk if sentiment cools?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Onex for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Onex can feel uncomfortable, so it may be useful to act promptly, stress test the numbers yourself and weigh both the potential upside and the risks with the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Onex?
If Onex has sharpened your thinking, do not stop here. A wider watchlist can surface opportunities you would not spot just following headlines.
- Target resilience by scanning companies that combine low risk profiles with steadier fundamentals using the 1 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing our curated set of 9 high quality undiscovered gems before they attract broader attention.
- Build a sturdier income base by focusing on potential 2 dividend fortresses that could support more reliable cash payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com