


Chipotle Mexican Grill (CMG) Opens In Seoul With Valuation Questions Still In Play
Why Chipotle’s First Asian Restaurant Matters for CMG Stock
Chipotle Mexican Grill (CMG) is testing its playbook in Asia, opening its first restaurant in Seoul through a joint venture with Sangmidang Holdings that treats South Korea as a template market.
Investors now have a live example of how Chipotle plans to balance menu consistency with local execution as it eyes further locations in South Korea and a first site in Singapore. This development raises fresh questions about the long term international potential for CMG.
Chipotle Mexican Grill’s latest moves come after a mixed run for shareholders, with the 1 month share price return of 8.1% and 90 day gain of 10.6% contrasting with a year to date share price decline of 3.4% and a 1 year total shareholder return that fell 6.3%. This suggests sentiment has improved in the short term as investors weigh new menu launches and the Seoul opening against a tougher longer term track record.
Compare Chipotle Mexican Grill’s Asia move with other consumer names that could be setting up their own next chapter through our hand picked 15 high quality undiscovered gems.
Chipotle now trades at a sizable discount to analyst targets, even as the Seoul launch and new menu push reset the growth story. Is the gap signaling opportunity or justified caution once you run the valuation numbers?
Most Popular Narrative: 29.8% Overvalued
The most followed narrative on Chipotle Mexican Grill pitches a fair value of $27.88 against the last close at $36.20, which creates a clear pricing gap for investors to unpack.
Chipotle is a fast-casual restaurant business that makes almost all of its money from company-owned restaurants selling Mexican-inspired food (burritos, bowls, tacos, etc.). Its growth strategy is straightforward: open more stores, increase digital sales, and improve restaurant productivity. In FY2025, Chipotle generated approximately US$11.9 billion in revenue, with around 99.5% coming from food and beverage sales. Around 37% of sales now come through digital channels, including app and online orders.
Want to see what really underpins that lower fair value for Chipotle Mexican Grill? The narrative leans heavily on assumptions around store rollout pace, digital mix and long run profit margins, and how those interact over time.
Result: Fair Value of $27.88 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the bearish Chipotle Mexican Grill story could crack if international execution in markets like Seoul outperforms expectations, or if digital mix supports steadier margins.
Find out about the key risks to this Chipotle Mexican Grill narrative.
Another View on Chipotle Mexican Grill’s Valuation
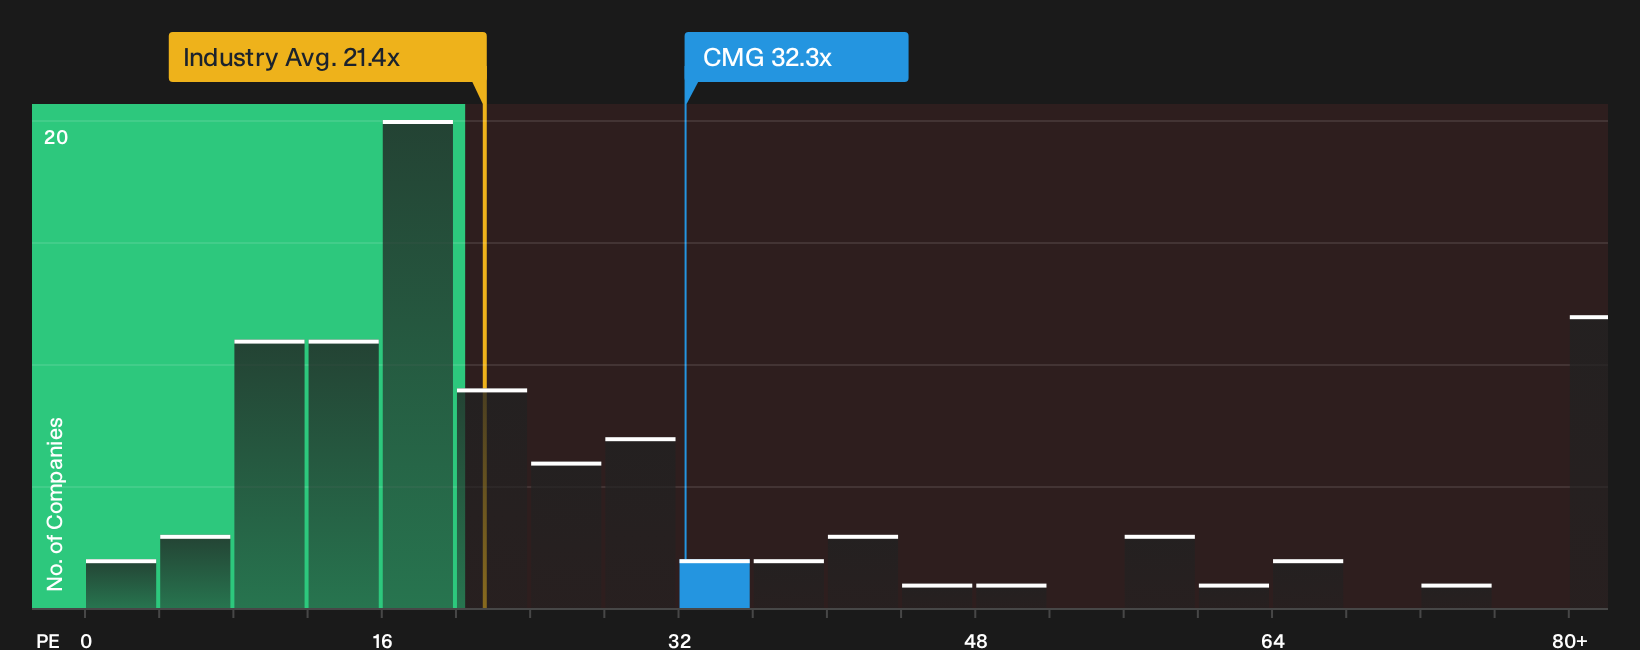
The user narrative leans on a fair value of $27.88, which implies Chipotle Mexican Grill is overvalued. A different lens comes from the P/E ratio. CMG trades on 32.3x earnings versus a US Hospitality average of 21.4x and a fair ratio of 26.9x, so the share price carries a richer-than-market earnings multiple that could compress if sentiment cools.
That richer multiple also screens as good value compared with peer companies on 40.1x, which shows how differently investors can price the same earnings stream. This gap may be interpreted as a valuation stretch or as a premium many investors are still willing to pay for CMG.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Chipotle Mexican Grill so far. Use that tension as a prompt to pull up the numbers yourself and move quickly while sentiment is still forming. To see what optimism the market is already pricing in, start with the 2 key rewards.
Looking for more investment ideas beyond Chipotle Mexican Grill?
If you stop with Chipotle Mexican Grill, you only see one piece of the puzzle. Broaden your watchlist and let stronger opportunities come to you.
- Target fresh upside potential by scanning a 21 elite penny stocks with strong financials universe where balance sheets and earnings quality help separate speculation from genuine opportunity.
- Zero in on quality at a discount by using our 32 high quality undervalued stocks to spot companies where fundamentals and price are pulling in different directions.
- Prioritise resilience and staying power by filtering for a list of solid balance sheet and fundamentals (23 results) that can better handle shocks without constant refinancing pressure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com