


Is Northern Trust (NTRS) Fully Valued Following Its Stablecoin And Singapore Expansion?
Northern Trust (NTRS) has just pushed further into two fast-growing niches, launching a Stablecoin Cash Reserves Portfolio in the US and expanding its Singapore unit trust platform through a new relationship with Perpetual (Asia) Limited.
These product launches come as Northern Trust shares trade at US$189.19, with the stock showing a 9.54% 90 day share price return and a 35.83% year to date share price return, while the 1 year total shareholder return of 49.28% indicates momentum that extends well beyond the recent uptick.
Scan how Northern Trust’s digital asset pivot compares with other financial groups pushing into similar territory by reviewing our curated list of 21 cryptocurrency and blockchain stocks in one place.
Northern Trust’s push into stablecoin reserves and Singapore unit trusts can be read two ways, as a reflection of sturdier underlying earnings power or a sentiment driven chase for hotter themes. Which lens fits current valuation?
Most Popular Narrative: 2.9% Overvalued
The most followed narrative pegs Northern Trust's fair value at $183.81, slightly below the recent $189.19 share price. This suggests a modest premium that hinges on specific growth and margin assumptions.
The analysts have a consensus price target of $183.81 for Northern Trust based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of $180.86, the analyst price target of $183.81 is 1.6% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
Want to see what really underpins that fair value call? The narrative leans on measured revenue growth, firmer margins, and a future earnings multiple that quietly reflects discipline rather than hype.
Result: Fair Value of $183.81 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, a faster shift into low fee passive products or heavier technology spending could pressure Northern Trust’s margins enough to challenge that fair value story.
Find out about the key risks to this Northern Trust narrative.
Another View: Northern Trust Through The P/E Lens
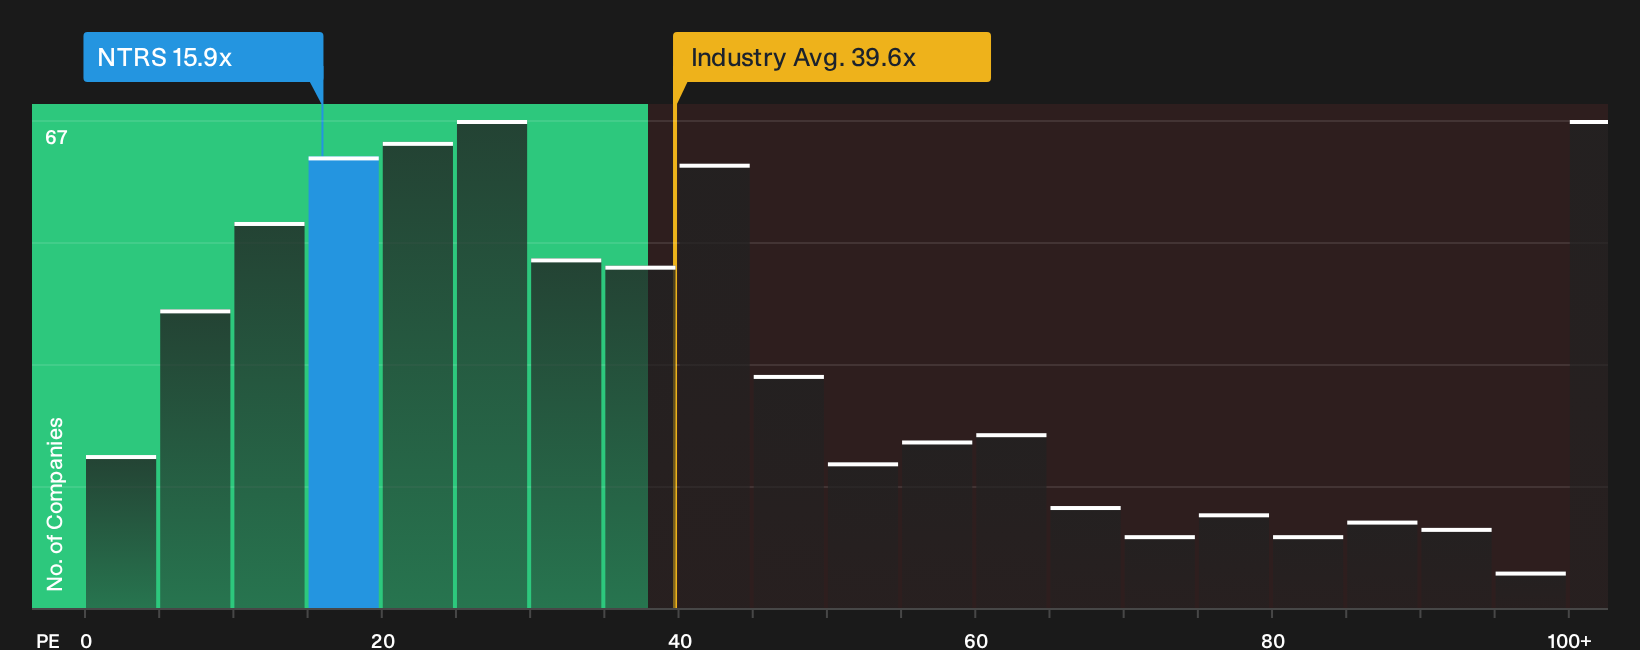
Northern Trust screens cheaply against the US Capital Markets group, with a P/E of 15.9x versus an industry average of 39.6x and a peer average of 22.9x. Yet that same P/E sits above a fair ratio of 14x, which hints at less margin for error if growth cools or sentiment fades.
That combination of apparent relative value and a premium to the fair ratio raises a straightforward question for investors: Is the market paying up for quality, or are expectations being stretched too far, given forecasts for mid single digit revenue and earnings growth?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Northern Trust's valuation story make this a good moment to test the numbers yourself rather than lean on headlines alone. If you want a quick read on what the market is optimistic about, start with the 4 key rewards.
Looking for more Northern Trust sized ideas?
If Northern Trust has sharpened your appetite for what disciplined stock selection can look like, widen your radar now using focused screeners built for different priorities.
- Target reliable income streams with companies that feature resilient payouts using our 6 dividend fortresses.
- Hunt for quality trading below intrinsic value by running a filter on the 32 high quality undervalued stocks.
- Prioritise resilience over excitement by scanning the 11 resilient stocks with low risk scores before the crowd catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com