


Does Raised Earnings Guidance Change The Bull Case For Academy Sports And Outdoors Stock?
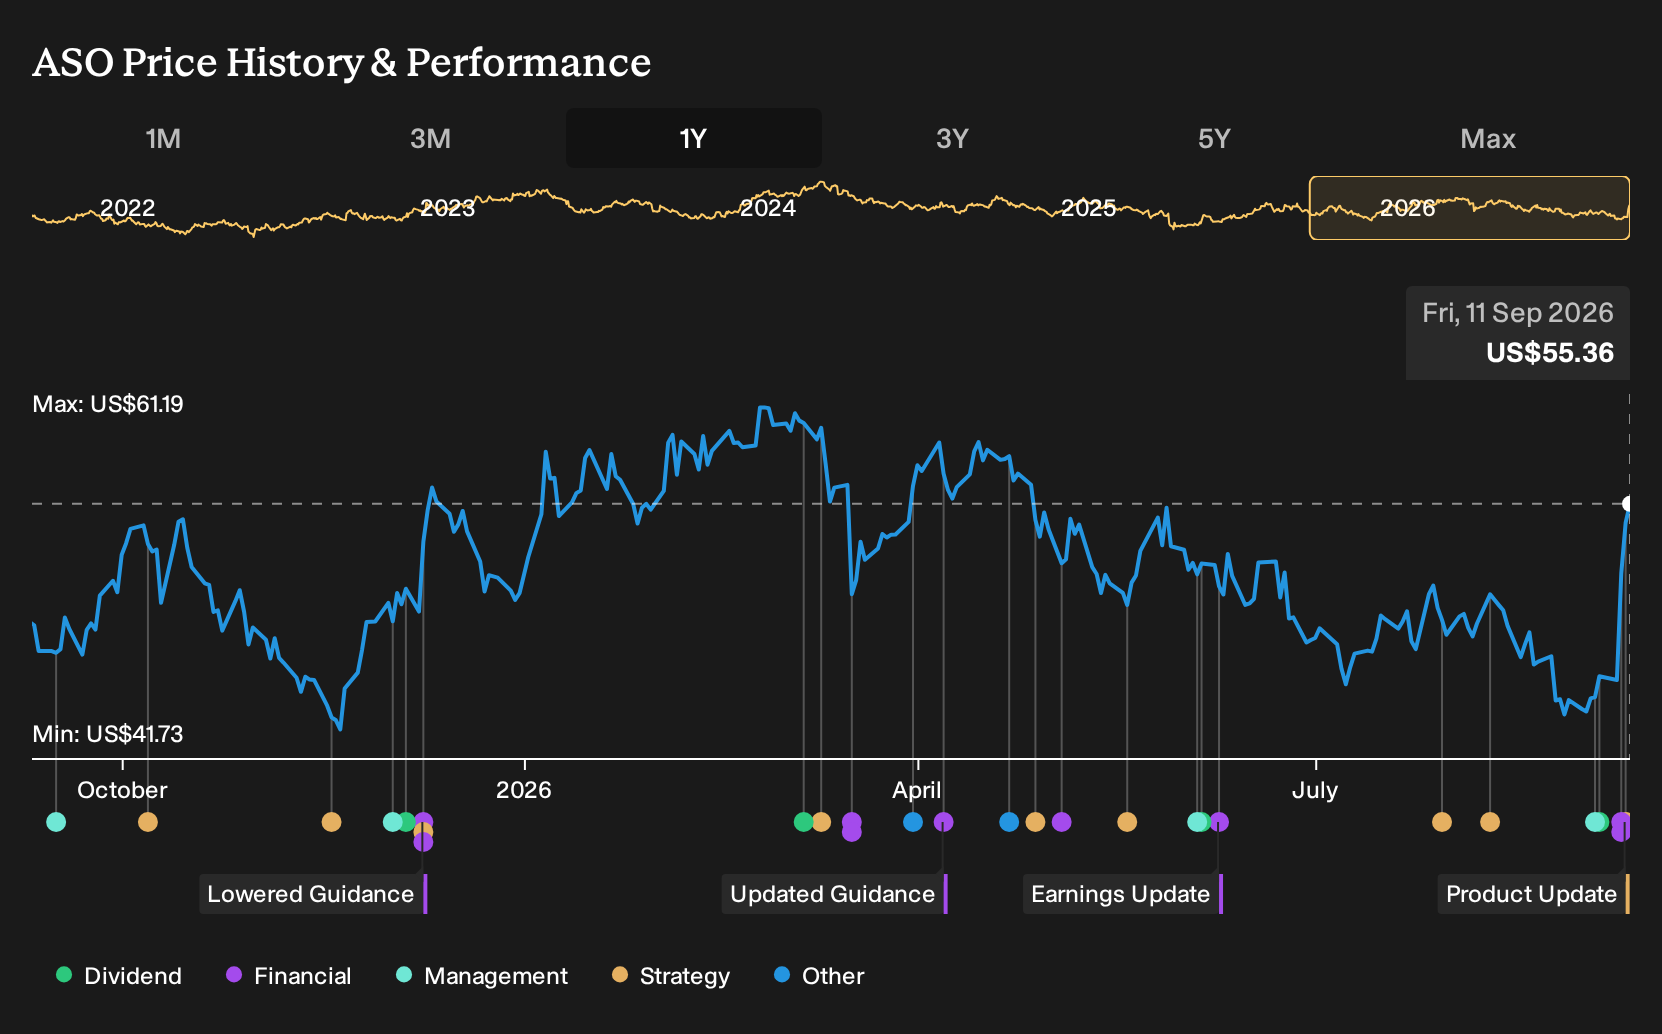
- Academy Sports and Outdoors reported second quarter sales of US$1,647.29 million and net income of US$137.9 million, with full year diluted EPS guidance lifted to a range of US$6.05 to US$6.45.
- Alongside higher earnings, Academy Sports and Outdoors is returning capital through buybacks and dividends while broadening assortments with brands like Hoka across Southern markets and online.
- We will now examine how Academy Sports and Outdoors' raised earnings guidance might reshape the investment narrative already priced into the stock.
Scan how Academy Sports and Outdoors stacks up against other retailers returning cash to shareholders by reviewing our curated list of 6 dividend fortresses for potential income ideas related to stories like this.
Academy Sports and Outdoors Investment Narrative Recap
To own Academy Sports and Outdoors, you need to believe the retailer can keep drawing traffic across income levels while holding margins in a more promotional backdrop. The recent quarter showed higher sales and earnings alongside raised diluted EPS guidance, which supports that operating thesis but does not radically change it. The near term swing factor still sits in how well Academy balances promotions with pricing power as cost pressures in freight, labor, and tariffs continue to bite.
The biggest risk remains dependence on higher income shoppers and brand partners in a regionally concentrated footprint. Any cooling in discretionary spending or disruption in vendor relationships could pressure both comps and profitability. Recent guidance, capital returns, and assortment moves, including Hoka, support credibility on execution but do not remove those structural pressures.
The Hoka rollout across 15 stores in Arkansas, Georgia, Louisiana, and Texas, plus online, is the announcement that most closely ties into Academy Sports and Outdoors' catalyst story. It directly connects to the push for stronger e commerce, more compelling assortments, and better traffic from higher spending households who are willing to pay for premium performance footwear.
This move also leans into a key operational risk. Heavy reliance on external brands, from Nike and adidas to Hoka, increases exposure to vendor strategies and distribution shifts. For you as an investor, the question is whether Academy can use launches like this to deepen loyalty, offset promotional pressure, and support margins, without becoming too dependent on any single vendor relationship.
Academy Sports and Outdoors' narrative projects US$7.0b revenue and US$481.1 million earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings increase of about US$104.3 million from US$376.8 million at present.
Uncover why Academy Sports and Outdoors' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view focuses squarely on digital execution. The most pessimistic analysts worry that Academy Sports and Outdoors is too slow online, which could matter a lot when launches like Hoka move to omnichannel. Before this news, they were penciling in revenue of about US$6.9b and earnings of roughly US$421.6 million by 2029. That is a much cooler story than consensus. Use those lower assumptions as a reference point, and then decide which version of the future feels closer to how you see the business evolving after these announcements.
Explore 2 other Academy Sports and Outdoors fair value estimates, including one that suggests as much as 10% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Academy Sports and Outdoors research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Academy Sports and Outdoors. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easier to evaluate Academy Sports and Outdoors' overall financial health at a glance.
Looking for more investment ideas beyond Academy Sports and Outdoors?
Once you have a view on Academy Sports and Outdoors, it can help to widen the lens and compare it with other businesses that match your income, quality, or risk preferences using the Simply Wall St Screener.
- If capital preservation is your priority, start with sturdier businesses by reviewing our 11 resilient stocks with low risk scores to screen for resilience and lower overall risk.
- For investors hunting for value opportunities, compare Academy Sports and Outdoors with our 32 high quality undervalued stocks which combines solid balance sheets with attractive pricing.
- If you prefer to back quieter stories before they are widely followed, broaden your watchlist using our 15 high quality undiscovered gems featuring strong fundamentals that are still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com