


BWX Technologies (BWXT) Lands DOE Contract On A Pullback But Is The Value Case Priced In
BWX Technologies (BWXT) attracted fresh attention after securing a four month, US$4 million phase one contract from the U.S. Department of Energy’s National Nuclear Security Administration for a lithium processing facility design.
For investors tracking the bigger picture, BWX Technologies has seen the share price fall 22.6% over the past 90 days and 17.5% year to date. However, the 3 year total shareholder return of about 106% and 5 year total shareholder return of about 187% point to strong longer run momentum that recent weakness has cooled.
Scan other nuclear energy infrastructure opportunities alongside BWX Technologies with our curated list of 91 nuclear energy infrastructure stocks for investors watching this contract win closely.
Bulls see BWX Technologies as a high quality nuclear contractor on sale after the pullback. Bears point to the recent share price slide and question the valuation. Which side does the current pricing support?
Most Popular Narrative: 35.4% Undervalued
Compared with the last close of $150.12, the most followed narrative pegs BWX Technologies at a fair value of $232.31, which puts a spotlight on what assumptions are driving that gap.
Record $6 billion backlog (+70% YoY) and 23% quarter-over-quarter growth, driven by multi-year defense contracts, rapidly expanding opportunity pipeline, and accelerating nuclear energy/medical demand are cited as indicators of visibility into future revenue growth and earnings stability.
Want to see what sits behind that backlog driven story? The narrative leans on compounded revenue, expanding margins, and a rich future earnings multiple that rivals high growth sectors.
BWX Technologies is modeled on a path that combines moderate top line expansion, rising profitability, and a premium P/E several years out. The narrative hinges on those three ingredients working together to support that higher fair value target.
Result: Fair Value of $232.31 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, BWX Technologies relies heavily on long-term U.S. government contracts, and any shift in defense budgets or setbacks in commercial nuclear demand could quickly challenge this optimism.
Find out about the key risks to this BWX Technologies narrative.
Another View on BWX Technologies Valuation
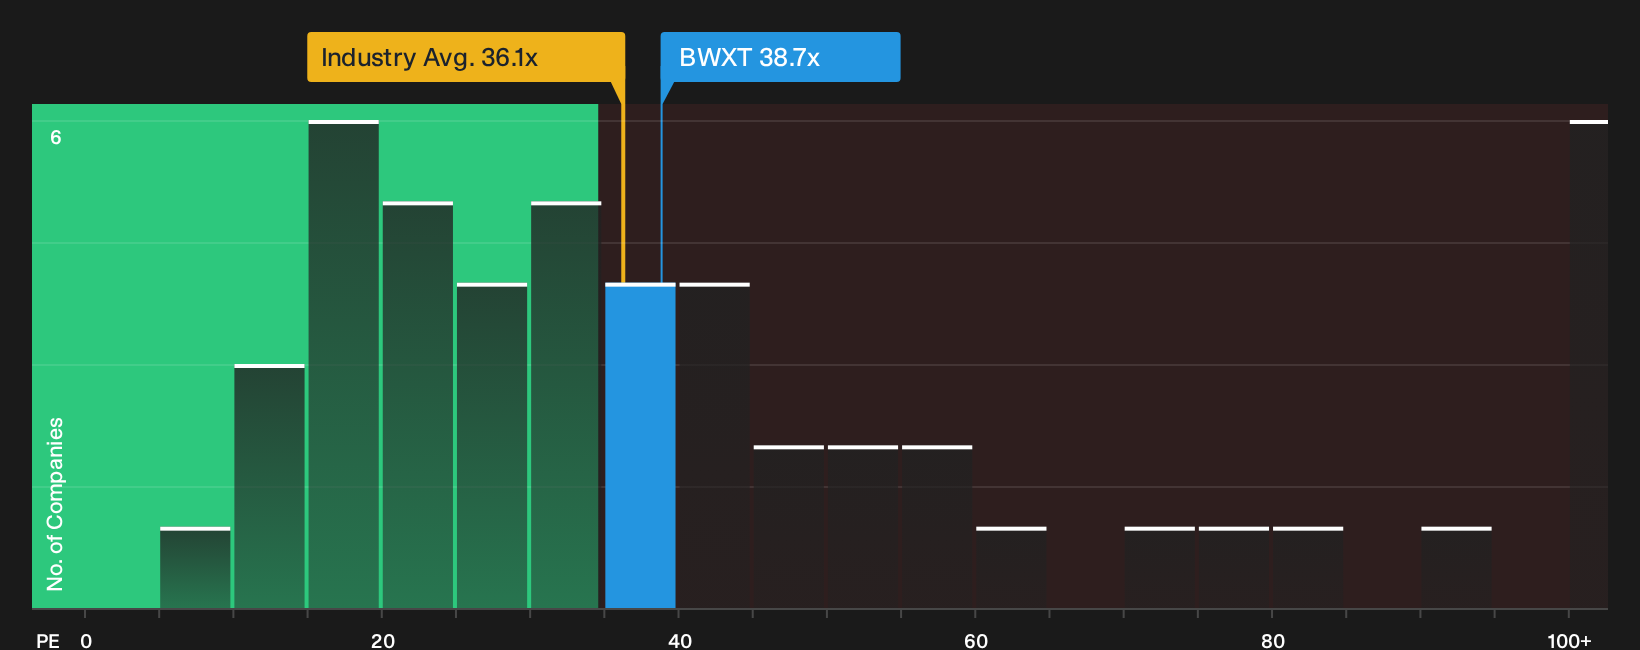
Analyst narratives lean on a fair value of $232.31, yet the current P/E of 38.7x tells a different story. That multiple sits above both the US Aerospace & Defense average of 36.1x and the 26.3x fair ratio the market could move toward, which raises the question of whether investors are already paying up for a lot of the upside.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on BWX Technologies so far. If you want a sharper view and to move with more conviction, start with the 3 key rewards and 1 important warning sign.
Looking for more BWX Technologies style investment ideas?
Do not stop with BWX Technologies. Use the Simply Wall St screener to uncover fresh angles before other investors catch on and crowd the best opportunities.
- Target value opportunities early by scanning the 32 high quality undervalued stocks that combine quality fundamentals with pricing that has not fully reflected them yet.
- Prioritise resilience and sleep easier at night by focusing on a 11 resilient stocks with low risk scores that filters for businesses with stronger overall risk profiles.
- Hunt for future leaders before they are widely followed by tracking a 15 high quality undiscovered gems built around strong financials and relatively low visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com