


How Rising Inflation Fears At Darling Ingredients Stock Have Changed Its Investment Story
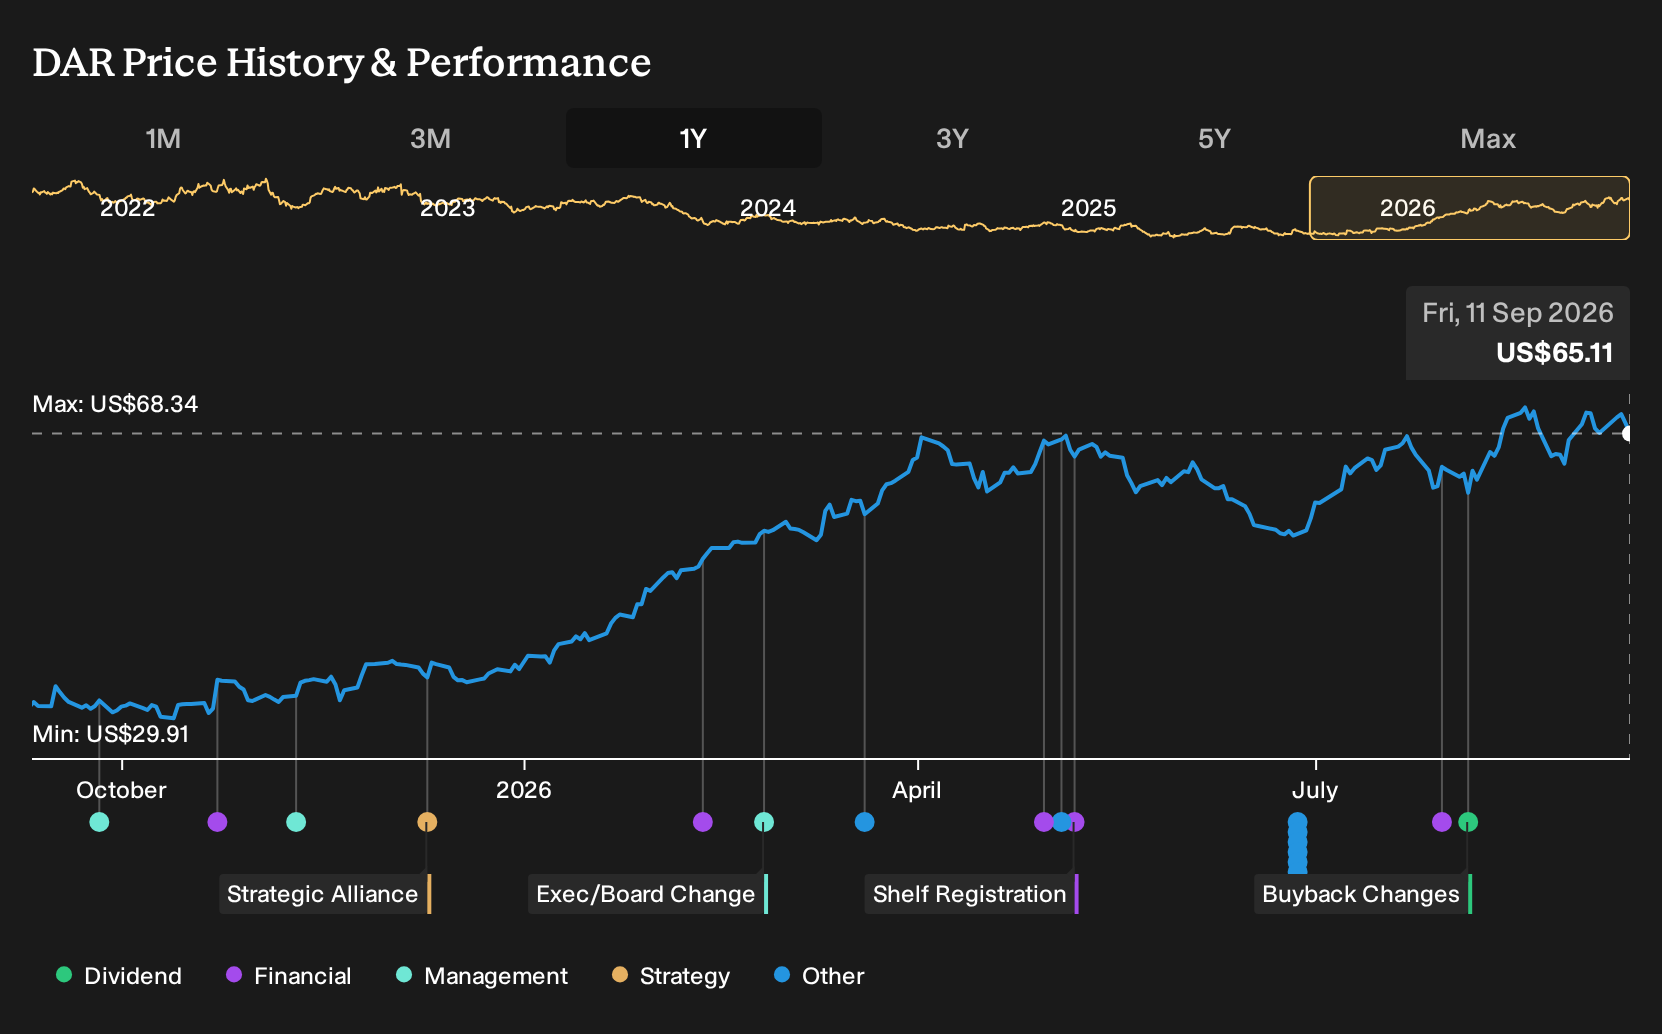
- Wholesale inflation in the U.S. increased in August 2026 as oil prices rose and Middle East risks escalated, with Darling Ingredients highlighted as a defensive consumer staples business in this higher cost backdrop.
- The focus on Darling Ingredients reflects investor interest in companies whose feed and fuel ingredients may be less sensitive to discretionary spending when inflation pressures build.
- We will examine how Darling Ingredients' investment narrative is shaped by its defensive positioning as inflation pressures pick up.
Scan beyond Darling Ingredients and line up other inflation resilient consumer businesses using our hand picked 11 resilient stocks with low risk scores while wholesale prices and oil stay in focus.
Darling Ingredients Investment Narrative Recap
For you to back Darling Ingredients, you have to believe its position in feed, food, and fuel ingredients can support relatively steady demand even when inflation and oil prices run hot. The near term swing factor remains renewable fuel profitability, where prior weakness at DGD and policy uncertainty around RINs and RVOs still cloud visibility.
The biggest risk right now is margin pressure from more volatile feedstock costs just as interest expenses feel heavier with higher rates. The latest wholesale inflation and oil move may increase input cost volatility but does not fundamentally change the key question: Can Darling Ingredients restore stronger utilization and margins in its Fuel segment?
With no fresh company specific announcements tied directly to the inflation print, the most relevant context is management’s existing focus on deleveraging. Interest payments are not well covered by earnings, so a backdrop of potential rate hikes keeps the cost of debt front and center for you.
That makes cash generation from Feed and Food ingredients critical to funding debt paydown while the renewable diesel business works through policy and utilization headwinds. For investors, the practical angle is execution. Watching leverage trends, interest coverage, and any update on DGD performance becomes even more important as wholesale prices and oil stay elevated.
Darling Ingredients' narrative projects US$7.3b revenue and US$878.1m earnings by 2029. This assumes 3.6% yearly revenue growth and an earnings increase of about US$280m from US$597.9m today.
Discover how Darling Ingredients' fair value indicates a 21% potential upside to its current price that could close sooner than many expect.
Exploring Other Perspectives
You can see how different the bullish view on Darling Ingredients looks when set against today’s inflation and oil shock. The most optimistic analysts were penciling in about US$7.2b revenue and US$734.2m earnings by 2029, on a richer 23.7x P/E. Those projections came before this inflation print, so assumptions on margins and policy support may now face a rethink.
Explore 5 other Darling Ingredients fair value estimates, including one that suggests as much as 157% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent research.
- A great starting point for your Darling Ingredients research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Darling Ingredients. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Darling Ingredients' overall financial health at a glance.
Looking For More Ideas Beyond Darling Ingredients?
If you want to stress test your view on Darling Ingredients, it helps to compare it against other businesses with different balance sheets, cash flow profiles, and income streams. The Simply Wall St Screener lets you line up those alternatives quickly so you can see where Darling fits in your wider watchlist.
- For investors who care most about quality at a reasonable entry point, filter for sturdier opportunities using the 32 high quality undervalued stocks.
- If dependable income matters to you, narrow in on companies with stronger payout potential by screening through the 6 dividend fortresses.
- When balance sheet strength is your priority, build a shortlist anchored on financial resilience by starting with the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com