


NRG Energy (NRG) Could Be 40% Undervalued As Earnings Estimates Rise
NRG Energy stock move sets up an earnings test
NRG Energy (NRG) recently outpaced the broader market with a 1.62% gain ahead of its next earnings release. The move came as analysts raised earnings per share projections and focused attention on profitability expectations.
The recent 1.62% one day share price gain for NRG Energy comes against a tougher backdrop, with the 30 day share price return down 10.12% and the year to date share price return down 31.72%. Even though the three year total shareholder return is up more than 200%, current moves look more like a pause in a longer rerating than fresh momentum.
Short term weakness, including a 12.99% decline in the 90 day share price return and a 30.32% drop in the one year total shareholder return, suggests investors are reassessing risk around earnings. At the same time, the strong three and five year total shareholder returns hint that the market has already priced in a significant part of NRG Energy's longer run story.
Seize this earnings reset moment in NRG Energy to compare it with a hand picked group of utilities and infrastructure players screened as 39 power grid technology and infrastructure stocks.NRG Energy now combines a long run record of value creation with a sharp pullback in the share price. Is this a bargain supported by strong fundamentals, or does it represent a fair valuation given rising earnings risk?
Most Popular Narrative: 39.9% Undervalued
The most followed valuation storyline for NRG Energy places fair value at $188.75 against a last close of $113.46, framing the current pullback as a sizeable gap that hinges on how future earnings and cash generation play out.
The accelerated adoption of data centers, electrification, and the signing of long-term, premium-margin agreements for large, multi-year power delivery significantly increases NRG's exposure to growing electricity demand, pointing to higher recurring revenue and margin expansion through 2030 and beyond.
Read the complete narrative. Read the complete narrative.
Want to see what sits behind that optimism for NRG Energy? The narrative leans on steadily rising earnings, richer margins and a future valuation multiple more typical of higher growth sectors. Curious which specific long dated power contracts, capital plans and cash flow assumptions need to hold true for that fair value to make sense? The full breakdown connects those moving parts into one detailed earnings roadmap.
Result: Fair Value of $188.75 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the NRG Energy story can break if data center power demand arrives more slowly than expected or if heavier natural gas exposure draws tougher regulation.
Find out about the key risks to this NRG Energy narrative.
Another View on NRG Energy's valuation
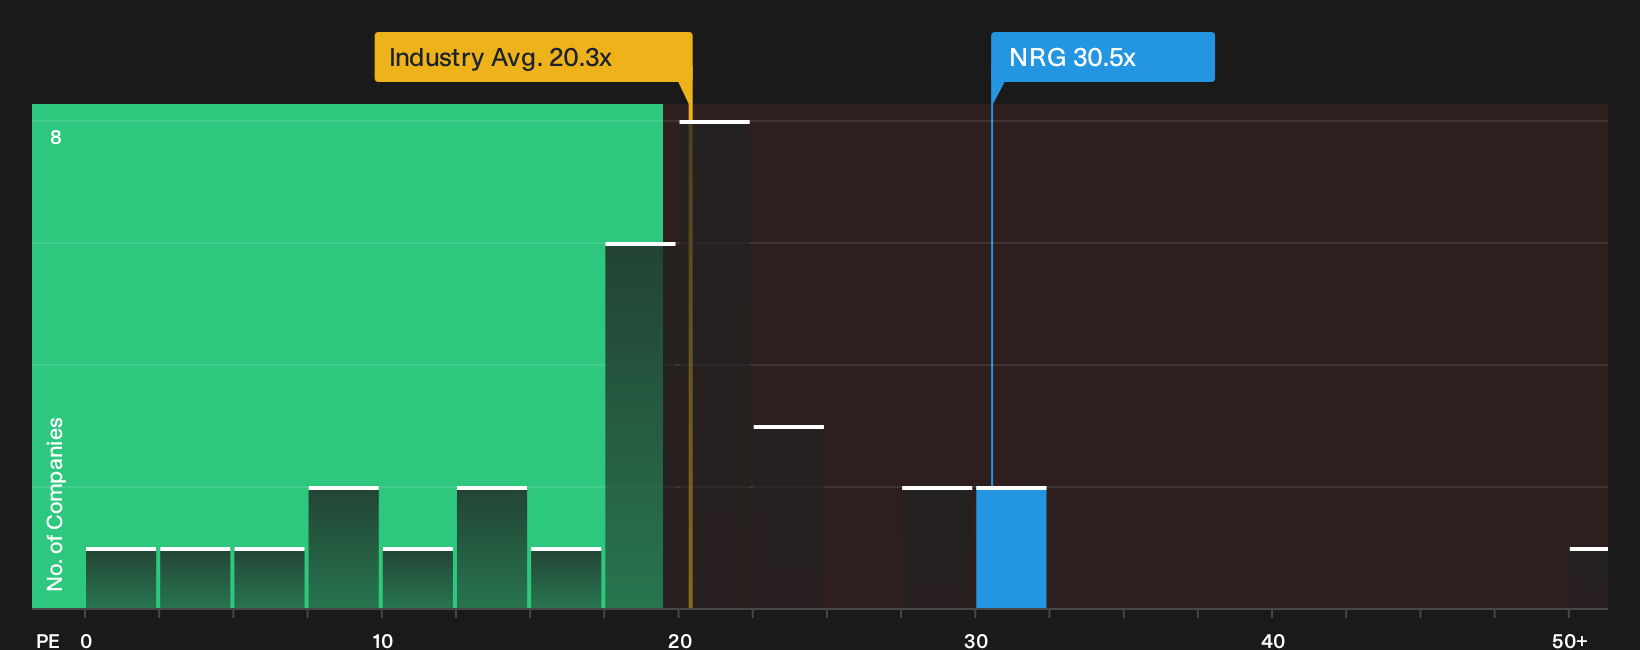
Analysts frame NRG Energy as 39.9% undervalued using a fair value of $188.75, yet the current P/E of 30.5x tells a different story. That ratio sits well above the US Electric Utilities industry average of 20.3x and only slightly below a fair ratio of 30.9x, which points to limited room for multiple expansion if earnings disappoint. For an investor weighing that gap, the key question is whether to focus more on the discount to fair value or on the risk that the P/E simply drifts back toward the sector.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around NRG Energy's valuation and earnings risk make this a moment to move fast, review the data yourself and decide where you stand. To size up both the downside and the upside in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond NRG Energy?
If NRG Energy has your attention, do not stop there. Broaden your watchlist with a few focused stock pools built around clear, data driven filters.
- Target potential value opportunities by scanning companies that screen as 32 high quality undervalued stocks and see which businesses line up with the metrics you care about.
- Prioritise resilience by reviewing 11 resilient stocks with low risk scores so you can compare NRG Energy with other companies that score well on balance sheet strength and volatility.
- Hunt for earlier stage potential by checking 21 elite penny stocks with strong financials before the crowd starts paying attention to them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com