


Tencent Holdings (SEHK:700) Following Enflame IPO Surge Has Valuation Back In Focus
Tencent Holdings (SEHK:700) is back in focus after Enflame Technology, an AI chip developer it backs and supplies, surged in its Shanghai IPO and sharply lifted the value of Tencent’s stake.
Recent trading tells a mixed story for Tencent Holdings. The share price is around HK$428.4, with the 1-day share price return up 0.66%, yet the year to date share price return down 31.24% as interest in AI assets like Enflame contrasts with fading broader momentum.
Scan how Tencent Holdings fits into the broader AI chip story by comparing it with hand-picked 89 AI infrastructure stocks that are shaping the next wave of compute demand.
Bulls see Tencent Holdings as an AI infrastructure beneficiary whose Enflame stake is mispriced, while bears point to a share price that is still down sharply this year. Which case does the current valuation lean toward?
Most Popular Narrative: 16% Overvalued
The most followed valuation narrative pegs Tencent Holdings at a fair value of HK$370, below the last close of HK$428.4, which frames the debate around how much investors are already paying for its AI push.
Tencent is currently in a “AI = capex + opex expansion phase,” not in “AI = cost reduction phase.” 🔑 Critical insight: This is not “AI reduces costs → margins expand.” This is “AI increases costs → hoping revenue grows enough to compensate.” 🔥 This completely changes the DCF profile: • FCF ↓ (short term) • capex ↑ • margins ↓ • optionality ↑
Read the complete narrative. Read the complete narrative.
The fair value hinges on how much Tencent Holdings spends on AI, how those projects affect profitability, and what kind of future earnings multiple that cash flow profile could justify. The narrative blends assumptions about top line expansion, profitability pressure, and where returns on reinvested capital might settle.
Result: Fair Value of HK$370 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, two pressure points could upend this Tencent Holdings narrative: ongoing US scrutiny after the Chinese military blacklist move and shifting AI regulations inside China.
Find out about the key risks to this Tencent Holdings narrative.
Another View On Tencent Holdings’ Valuation
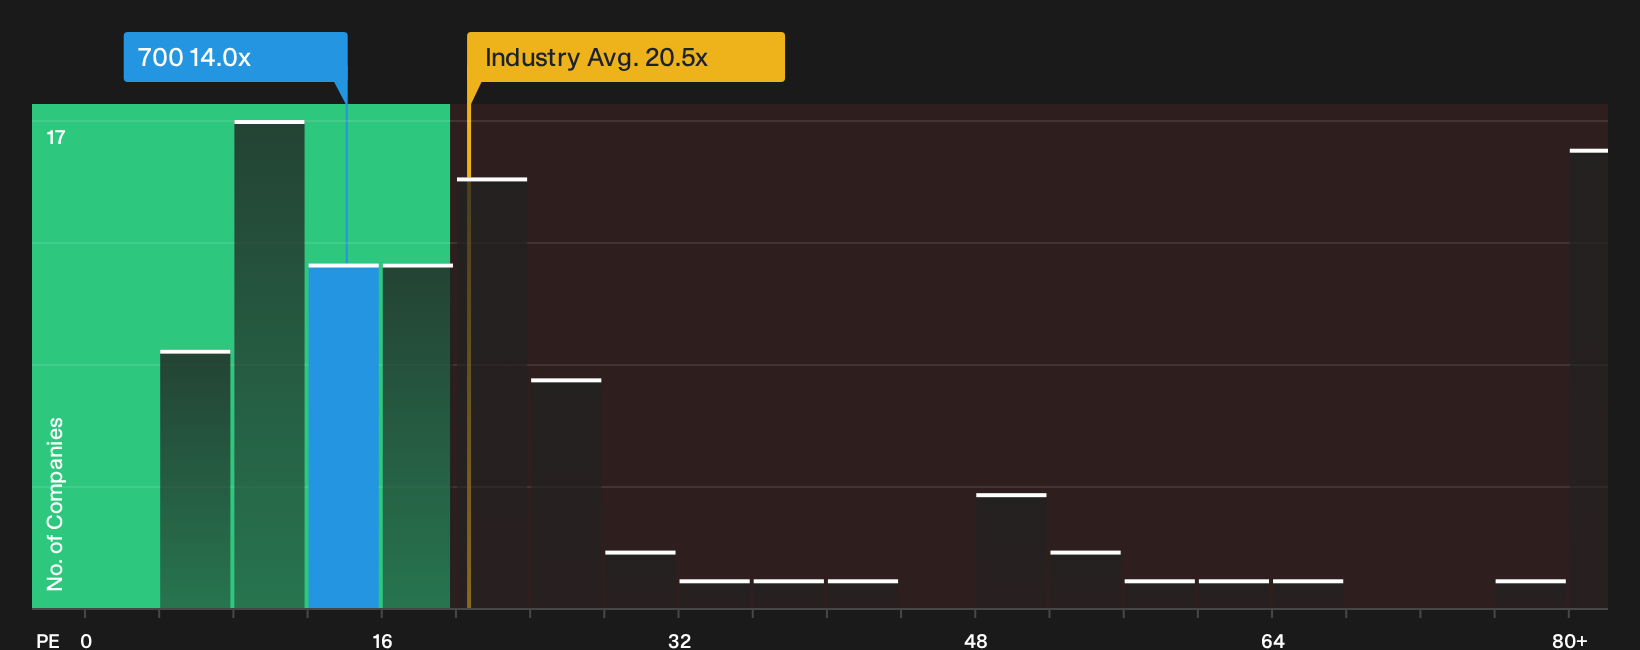
A very different picture comes from the earnings multiple. Tencent Holdings trades on a P/E of 14x, while the Asian interactive media peer group sits nearer 20.5x and the fair ratio sits at 16.3x. That gap hints at both a discount and income risk if sentiment turns. Which story do you trust more?
See what the numbers say about this price, find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The AI excitement around Tencent Holdings is only half the story, and the rest is in the numbers you review yourself. Move quickly, pressure test the bullish case, and see why our work highlights 4 key rewards.
Looking for more Tencent Holdings style investment ideas?
If Tencent Holdings has sharpened your focus on valuation and risk, do not stop here. Use fresh screens to surface other candidates before the crowd moves.
- Target mispriced quality by scanning a curated 183 high quality undervalued stocks that blend strong fundamentals with what may be appealing entry points.
- Build a steadier income stream by reviewing a focused 161 dividend fortresses that concentrates on higher yield payouts with supporting financials.
- Dial down portfolio stress by filtering for 99 resilient stocks with low risk scores that pair resilience scores with balance sheets built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com