


Did Five Yacht Premieres Just Shift Ferretti Stock Investment Narrative?
- Ferretti Group recently opened the autumn yachting season at the Yacht Club de Monaco, showcasing five world premieres across Itama, Riva, Pershing and Custom Line, alongside 41 yachts available for private visits and sea trials.
- The focus on multiple new models in one setting highlights Ferretti’s push to refresh its luxury portfolio in line with bespoke, higher value yacht demand.
- We will now look at how Ferretti’s Monaco showcase of five new yacht premieres fits into the existing investment narrative.
Scan beyond Ferretti and its Monaco premieres by reviewing a hand picked 619 high quality undiscovered gems with similarly strong fundamentals and differentiated positioning in their niches.
Ferretti Investment Narrative Recap
To own Ferretti, you need to be comfortable with a luxury yacht builder that leans heavily on made to measure and super yachts, where a handful of large contracts can swing reported results. The near term opportunity is continued demand for larger, customized boats and the support of a rising backlog, while the main risk is order lumpiness turning into softer reported revenue or earnings if a few big deals slip.
Competitive discounting in composite yachts and a fully booked high end production line out to 2028 and 2029 frame the short term picture. The Monaco Private Preview showcases fresh product but does not meaningfully change the key near term catalyst: execution on the order book. It also does not change the biggest risk: potential underutilization if ultra high end buyers slow or defer.
The Monaco event itself is the headline announcement that matters most here. Management used the Private Preview to put five premieres on the water across Itama, Riva, Pershing and Custom Line in front of an audience that can afford them, while also organizing private visits and sea trials that directly connect product to potential orders.
For you as a Ferretti watcher, that matters because catalysts for this business are operational. Order intake, pricing discipline against aggressive discounts elsewhere, and utilization of super yacht capacity are where sentiment can shift. Monaco is best read as a live test of brand strength and pricing power in a segment where even a small wobble in ultra high net worth appetite is the core risk.
Ferretti's analyst narrative points to €1.4b in revenue and €102.8 million in earnings by 2029, based on an assumed 1.2% yearly revenue growth rate and an earnings increase of about €18.4 million from current earnings of €84.4 million.
Uncover why Ferretti's fair value points to a 21% potential upside to its current price that could narrow quickly as sentiment catches up.
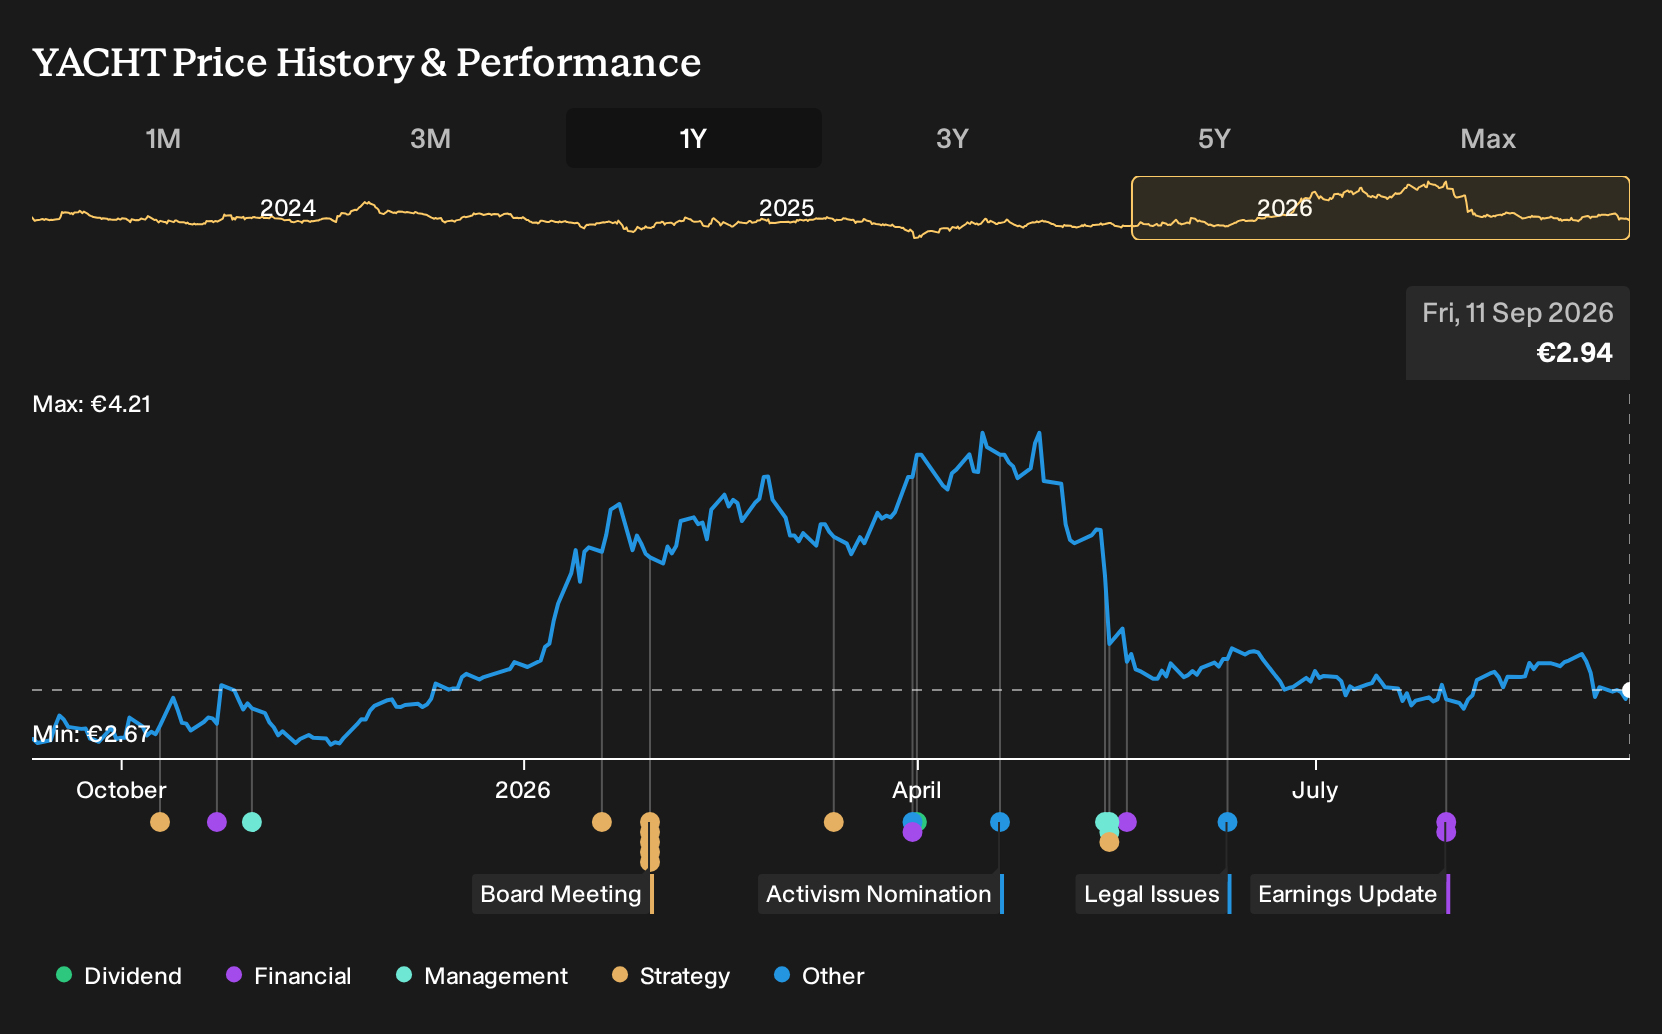
Exploring Other Perspectives
For Ferretti, the bullish analysts focus on constrained super yacht supply as a possible upside catalyst. They were already pencilling in about €1.5b of revenue and €122.2 million of earnings by 2029, compared with consensus at €1.4b and €102.8 million. This Monaco showcase could shift those narratives, so compare both views before deciding what feels reasonable to you.
Explore 2 other Ferretti fair value estimates, including one that suggests as much as 139% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ferretti research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Ferretti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ferretti's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ferretti?
If the Ferretti story has sharpened your thinking about quality, pricing power and contract concentration, use that same lens to scan a wider opportunity set with the Simply Wall St Screener. Pick the angle that best matches your style and let the filters do the heavy lifting for you.
- For investors who want quality at a discount, start with a curated set of 183 high quality undervalued stocks that pair fundamentals with more appealing pricing.
- If capital preservation ranks high for you, concentrate on a 99 resilient stocks with low risk scores that screens for resilient businesses with stronger risk profiles.
- For balance sheet strength and staying power, focus on a list of solid balance sheet and fundamentals (194 results) that highlights companies with healthier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com