


EPAM Systems (EPAM) Stock Climbed, What Is Behind The Fresh Attention?
Activist pressure puts EPAM Systems in the spotlight
EPAM Systems (EPAM) is back under the microscope after Engine Capital LP publicly urged the business to consider a US$750 million buyback, a possible sale, and wide governance changes.
EPAM Systems has seen its share price jump recently, with a 1-month share price return of 17.32% and a 3-month gain of 27.17%, even though the year-to-date share price return is still down 41.18% and the 1-year total shareholder return has declined 24.46%.
That rebound in the share price, including a 2.96% 1-day move around the latest close at US$117.91, suggests traders are reacting quickly to Engine Capital's activism and reassessing both potential upside and the risks if buybacks, governance shifts, or a sale process reshape the EPAM Systems investment case.
Scan how activists, buyback potential, and valuation line up by comparing EPAM Systems with a curated 32 high quality undervalued stocks that also pairs balance sheet strength with recent share price pressure.
EPAM Systems has sprinted off the lows, yet the share price still sits well below many valuation estimates. Is the recent activism fueled pop enough to close that gap, or is it only the first step?
Most Popular Narrative: 4% Overvalued
EPAM Systems closed at $117.91 while the most followed narrative on the stock pegs fair value at $113.38, which puts the current quote slightly ahead of that assessment and raises questions about how durable the recent activist driven bounce might be.
EPAM Systems has long been a darling of the IT services world, but a convergence of structural dangers suggests the stock may be worth half its current value. Three unaddressed red flags point to a brutal de-rating ahead.
Read the complete narrative. Read the complete narrative.
The narrative focuses on how modest revenue expansion, pressured profitability and a specific assumed earnings multiple interact to pull EPAM Systems closer to that fair value line.
Result: Fair Value of $113.38 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, if EPAM Systems continues its recent annual revenue and net income growth, or if activist efforts lead to clearer capital allocation plans, that bearish narrative could weaken quickly.
Find out about the key risks to this EPAM Systems narrative.
Another View on EPAM Systems Valuation
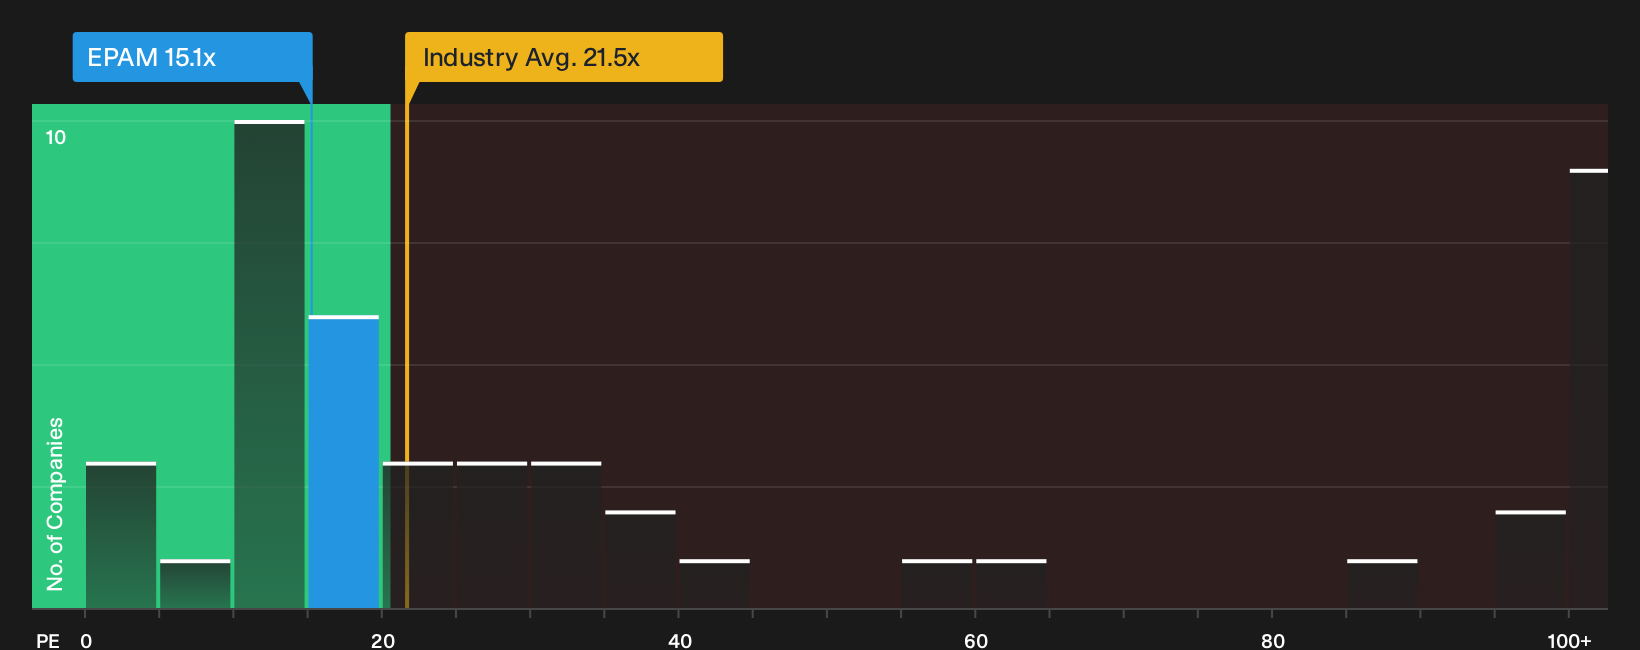
The first narrative argues EPAM Systems looks slightly over its $113.38 fair value, yet the market multiples paint a very different picture. At a P/E of 15.1x, the stock trades well below both the US IT industry on 21.5x and direct peers on 19x.
Our fair ratio sits even higher at 27.6x. This implies the market could move toward a meaningfully richer multiple over time, or the fair ratio itself could be too generous. For an investor weighing activist headlines against these gaps, the key question is whether this is a value trap or a valuation reset in progress.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are unsure whether the mixed sentiment around EPAM Systems points to a brief bounce or a deeper re-rating, and want to check the evidence yourself before the next move sets the tone, start with the structured breakdown of 3 key rewards.
Looking for more investment ideas beyond EPAM Systems?
If EPAM Systems has your attention, do not stop here. Fresh ideas now can shape the opportunities you actually see over the next few years.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that highlights businesses with quality fundamentals trading at compressed valuations.
- Prioritise resilience by reviewing a 11 resilient stocks with low risk scores that focuses on companies with steadier risk profiles and fewer red flags.
- Hunt for future leaders early by checking a 15 high quality undiscovered gems built around strong balance sheets and underfollowed fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com