


Adidas (XTRA:ADS) Stock Looks Overvalued Given Its Richer Earnings Rating
Adidas has had a tough run over the past few years, yet the current market pricing still leans on the expensive side when set against broad valuation checks. For anyone looking at the stock today, the puzzle is how to reconcile a weak share price record with a market-multiple profile that does not obviously flag a bargain.
- Over the last 5 years, adidas shareholders have seen the price decline about 47%, which raises questions about how much long term weakness is already reflected in the valuation.
- Future progress on margins and cash generation can support the current valuation, while any stumble in restoring profitability or cash flow quality may put pressure on the share price.
- The broader valuation score for adidas is mixed, a mid range read that points to neither a clear bargain nor a clear overpricing on the standard checks used, as summarised in this 4 out of 6 score.
The stock's next move may depend on whether adidas can justify this mixed valuation profile after such a steep multi year share price decline.
Broaden your watchlist beyond adidas by reviewing 183 high quality undervalued stocks, which our filters flag as combining quality fundamentals with more conservative valuation profiles.
Does adidas Look Pricey on Earnings?
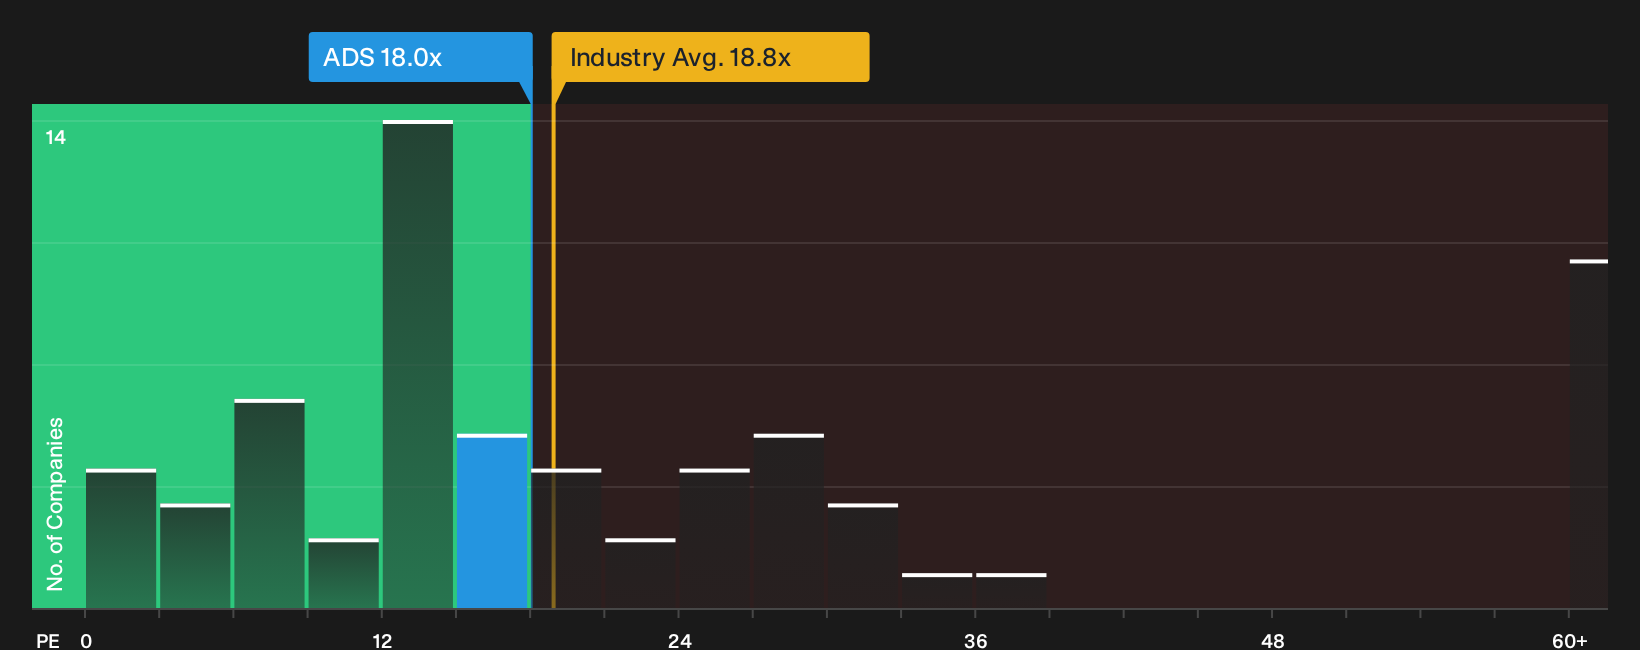
The P/E multiple gives a clean read on how much investors are paying for adidas earnings today. On this yardstick, adidas trades at about 18.0x current earnings. That sits above both the Luxury industry average of roughly 15.4x and the peer group near 13.3x, so the market is attaching a richer price tag to each euro of profit than it does for many comparable brands.
A tailored fair P/E for adidas of about 13.8x reflects what might be expected given its size, business mix and risk profile. The current 18.0x level comes in clearly higher than that benchmark, which indicates that the stock carries a premium relative to what this framework suggests is reasonable. For anyone tracking entry points, the numbers suggest that the share price already embeds a relatively full expectation for earnings.
On the P/E multiple alone, adidas stock currently appears overvalued.
See what the numbers say about this price — find out in our valuation breakdown.
The adidas Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where adidas' valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the shares to be worth materially more or less than today’s level. They sit on adidas' Community page so you can see how each scenario links its fair value view to a clear set of assumptions that can be compared with actual results over time.
One of the top community narratives on adidas: 16% undervalued
"Direct to consumer, e commerce and own stores are comping double digit and support structurally higher gross margins, while intensifying online discounting and promotional pressure from over inventoried peers may limit further mix driven margin gains."
Read one of the top narratives on adidas
Do you think there's more to the story for adidas? Head over to our Community to see what others are saying!
The Bottom Line
Adidas trades on a richer P/E than many peers, so the market is already paying up for the earnings that are on show today. The mixed valuation score reinforces that view and suggests only limited room for disappointment if profitability or cash generation slip. For new capital, the key question is whether adidas can rebuild margins and cash flow strongly enough to make that premium feel justified rather than stretched.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com