


Will Brewing Unit Shutdown Change Middleby's (MIDD) Narrative
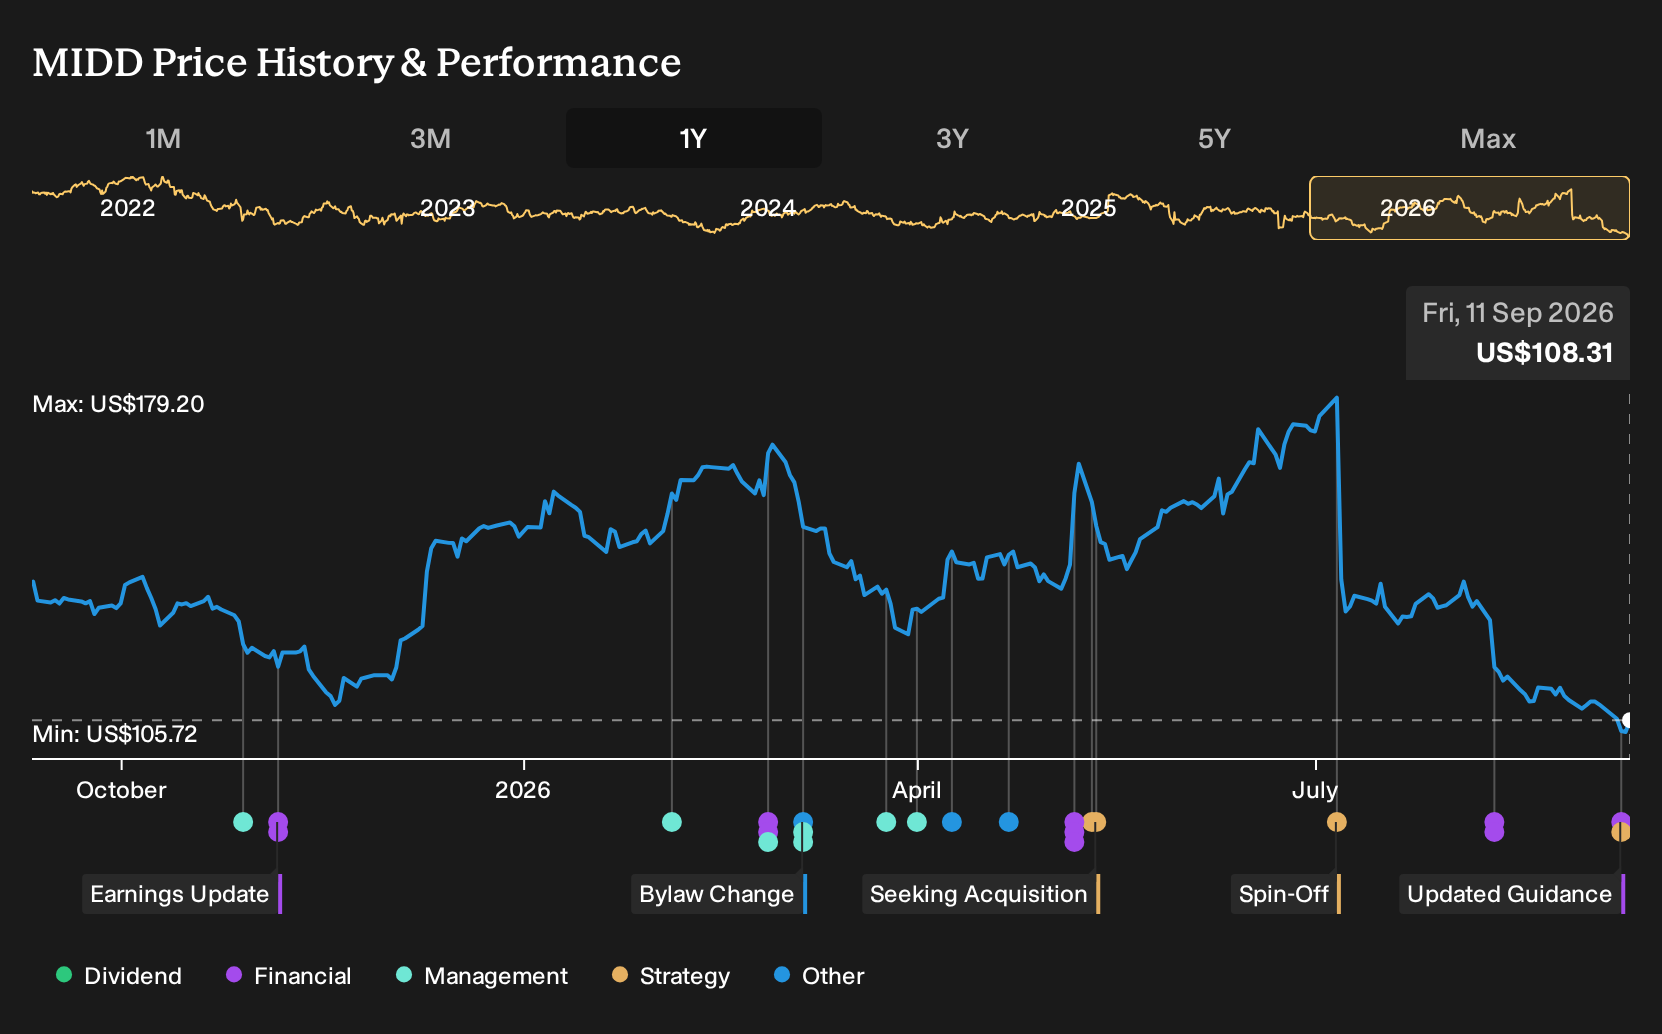
- Middleby recently confirmed it will wind down its Brewing & Distilling Solutions Group, including Deutsche Beverage + Process, Ss Brewtech and Wild Goose Filling. The company aims to substantially complete the exit by year end while keeping third quarter and full year 2026 net sales guidance unchanged.
- The exit from brewing and distilling equipment highlights management’s push to simplify operations and concentrate capital on businesses it views as having stronger long term growth and margin potential.
- We will look at how Middleby’s investment narrative is affected by exiting the Brewing Group while reiterating full year 2026 revenue guidance.
Compare Middleby's portfolio reshuffle with other industrials that score well on balance sheet strength and fundamentals by scanning our curated list of solid balance sheet and fundamentals (23 results) today.
Middleby Investment Narrative Recap
To own Middleby, you need to be comfortable with a kitchen equipment specialist that is reshaping its portfolio around higher margin, tech oriented systems while working through softer demand in key end markets. The exit from the Brewing Group looks operational rather than thesis breaking, since management kept short term net sales guidance in place.
The near term swing factor remains how quickly commercial and food processing customers step up replacement and upgrade spending, particularly as tariffs, input costs and supply chain issues keep pressure on margins. The biggest risk stays the same. Prolonged delays in equipment refresh, combined with high debt levels, would make any earnings setback harder to manage.
The most relevant update for this story is Middleby reaffirming third quarter and full year 2026 net sales guidance alongside the decision to discontinue the Brewing Group. That combination points you toward execution in the core commercial foodservice and food processing lines as the key thing to watch, rather than treating the exit as a demand shock.
For catalysts, the focus now sits on whether Middleby can convert its investment in automation, connected kitchen technology and energy efficient gear into steadier orders as customers refresh aging fleets. The Jefferies Global Industrials Conference appearance on 10 September gives management a stage to explain how the slimmer portfolio supports that plan and how they are balancing growth projects with a leveraged balance sheet.
Middleby's current analyst narrative points to forecast revenue of US$2.8b and earnings of US$355.7m by 2029, off a base of US$367.5m in earnings today and using an assumed yearly revenue decline of 5.7%. That path implies an earnings decrease of about US$11.8m from current levels.
Uncover why Middleby's fair value points to a 55% potential upside to its current price, which could narrow quickly if sentiment improves.
Exploring Other Perspectives
One alternate read on Middleby leans hard on end market risk. The most cautious analysts were already modeling revenue at about US$2.7b and earnings of US$350.1m by 2029, with faster annual top line declines than consensus. Those views pre date the Brewing Group exit and conference update, so future revisions could shift sharply.
Explore another Middleby fair value estimate, including one that suggests it could be worth just $105.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your Middleby research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Middleby. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Middleby's overall financial health at a glance.
Looking For More Ideas Beyond Middleby?
If the Middleby story has sharpened your thinking about quality, capital allocation and risk, it can be useful to scan a wider field of potential opportunities using the Simply Wall St Screener before making any decisions.
- For investors hunting for resilient businesses with lower risk profiles, start with a selection of 11 resilient stocks with low risk scores that score well on stability and fundamentals.
- If income is your priority, you can zero in on companies offering stronger yields by reviewing our lineup of 6 dividend fortresses that clear a 5% yield hurdle while still focusing on durability.
- Those looking for early stage opportunities with robust financial footing can cast a wider net by scanning a curated set of 21 elite penny stocks with strong financials that pair smaller size with stronger balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com