


Is Amgen (AMGN) Fully Valued As New IMDELLTRA Data Reshapes The Story?
Amgen (AMGN) is back in focus after reporting Phase 3 DeLLphi-305 results for IMDELLTRA combined with AstraZeneca’s Imfinzi in extensive stage small cell lung cancer, showing improved overall and progression-free survival versus Imfinzi alone.
Amgen’s recent IMDELLTRA data lands after a rough patch for the stock, with the 7-day share price return down 13.70% and the 30-day share price return down 9.12%. However, the 90-day share price return is up 7.65% and the year-to-date share price return is up 15.17%, feeding into a 1-year total shareholder return of 40.32% that points to strong longer-term momentum despite the latest pullback.
Compare Amgen’s move with other large, profitable drug makers by scanning our hand picked list of solid balance sheet and fundamentals (23 results) that have been holding up through recent volatility.
Amgen now looks like a powerful pharmaceuticals franchise whose shares have just been knocked back. The key tension is simple: Are you being asked to pay up for quality or offered a rare discount on it?
Most Popular Narrative: 4.8% Overvalued
The latest fair value narrative for Amgen pegs the stock at $359.98, a touch below the recent $377.35 close, which sets up a mild valuation gap that matters if you care about what is already priced in.
The "Amgen 2027 Bull Case" relies on a classic top-line fallacy: assuming that macro obesity market growth and FDA's CNPV (Commissioner’s National Priority Voucher) tailwinds will automatically trigger a re-rating.
Here is the cold, data-driven reality:
1. CNPV solves regulatory speed, not the manufacturing bottleneck. Amgen lacks the massive, domestic GLP-1 supply chain infrastructure that Lilly and Novo command. Fast-tracked approval without scale-up capacity only accelerates market-share caps.
2. The consensus ignores the regulatory friction. The CNPV pilot program is facing severe legal durability and structural transparency questions in mid-2026. Betting a 2027 thesis on an unstable, non-statutory policy is a high-risk gamble.
3. Competitors are already using the exact same playbook. Novo Nordisk already secured its Wegovy HD approval via CNPV in March 2026. Amgen is a latecomer trying to enter a crowded arena where the incumbents already hold the fast-track tokens.
4. The timeline mismatch is real. MariTide's commercial ramp-up will take years post-launch. Amgen’s high-margin legacy moats (Prolia and Enbrel) are already eroding at a brutal -30%+ YoY clip right now.
Amgen is priced for flawless execution, leaving zero margin of safety for the structural vacuum underneath its valuation. AMGN is a speculative premium hiding a legacy erosion.
According to AnimalDoctorKwon, the fair value call rests on a specific mix of moderate revenue expansion, firm profit margins and a future earnings multiple that bakes in obesity upside without treating Amgen like a hyper-growth tech stock. Curious which assumptions about long term profitability and de-risking of new launches actually carry the valuation math.
Result: Fair Value of $359.98 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Amgen could see this bearish script challenged if obesity trial readouts surprise on durability or if erosion in key legacy products slows meaningfully.
Find out about the key risks to this Amgen narrative.
Another View on Amgen’s Value
A very different picture comes from our DCF model, which values Amgen at $669.81 per share, well above the recent $377.35 price. This implies the stock is trading 43.7% below that estimate and frames the earlier $359.98 fair value as far more conservative.
For readers who want to see how that gap is built line by line, Look into how the SWS DCF model arrives at its fair value.
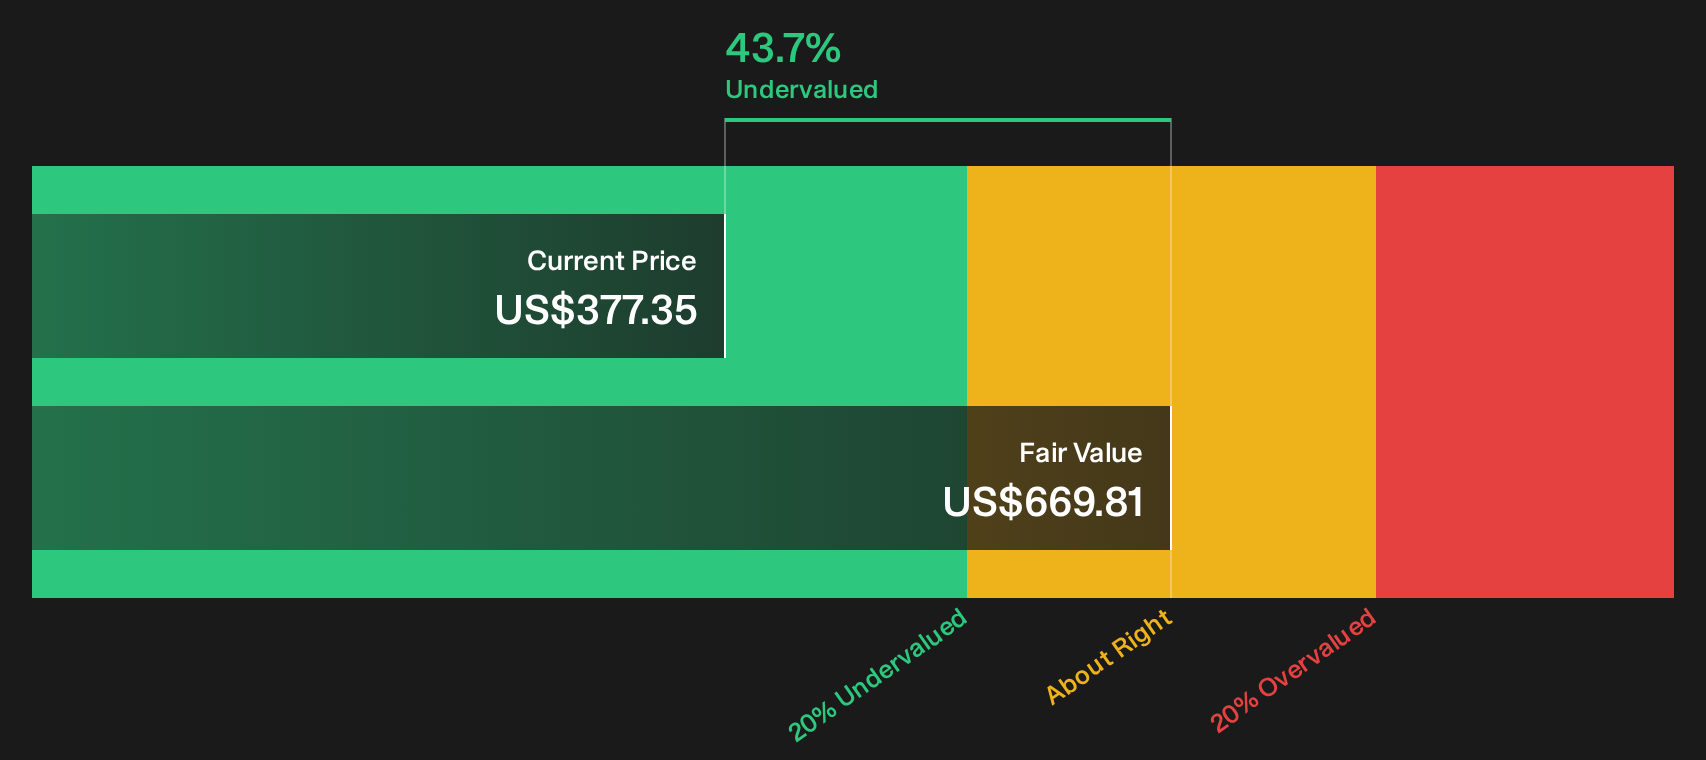
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amgen for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages across Amgen’s valuation and clinical updates make this a judgment call, so move quickly to review the evidence and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Amgen?
Do not stop with Amgen. Use the tools at hand to quickly spot other opportunities that fit your goals before the market prices them in.
- Target potential bargains that combine quality and attractive pricing by scanning our 31 high quality undervalued stocks.
- Build dependable income streams by focusing on companies in our 6 dividend fortresses.
- Prioritize resilience and lower downside risk by filtering for companies in our 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com