


YETI (YETI) Stock Could Be Fully Priced On Earnings But A Bargain Elsewhere
YETI Holdings stock has delivered a steep 59.3% decline over the past five years, yet on current market multiples it still screens as overvalued and the broader valuation checks point to a mixed picture rather than a clear bargain.
- Over five years, shareholders have seen the price fall 59.3%, which puts extra scrutiny on whether today's valuation leaves enough room for a durable recovery.
- Future demand for premium coolers and drinkware can support revenue, while any pressure on consumer spending or pricing power may weigh on margins and the share rating.
- The broader toolkit shows a mixed read on YETI Holdings, with a value score of 4, suggesting neither a clear discount nor an obviously stretched profile across the different valuation checks.
The issue now is whether YETI Holdings' current share price adequately reflects its track record, its business quality, and the risks that still hang over the valuation.
Broaden your watchlist beyond YETI Holdings by scanning our handpicked 31 high quality undervalued stocks that pair solid fundamentals with more balanced valuations.
Does YETI Holdings Look Pricey on Earnings?
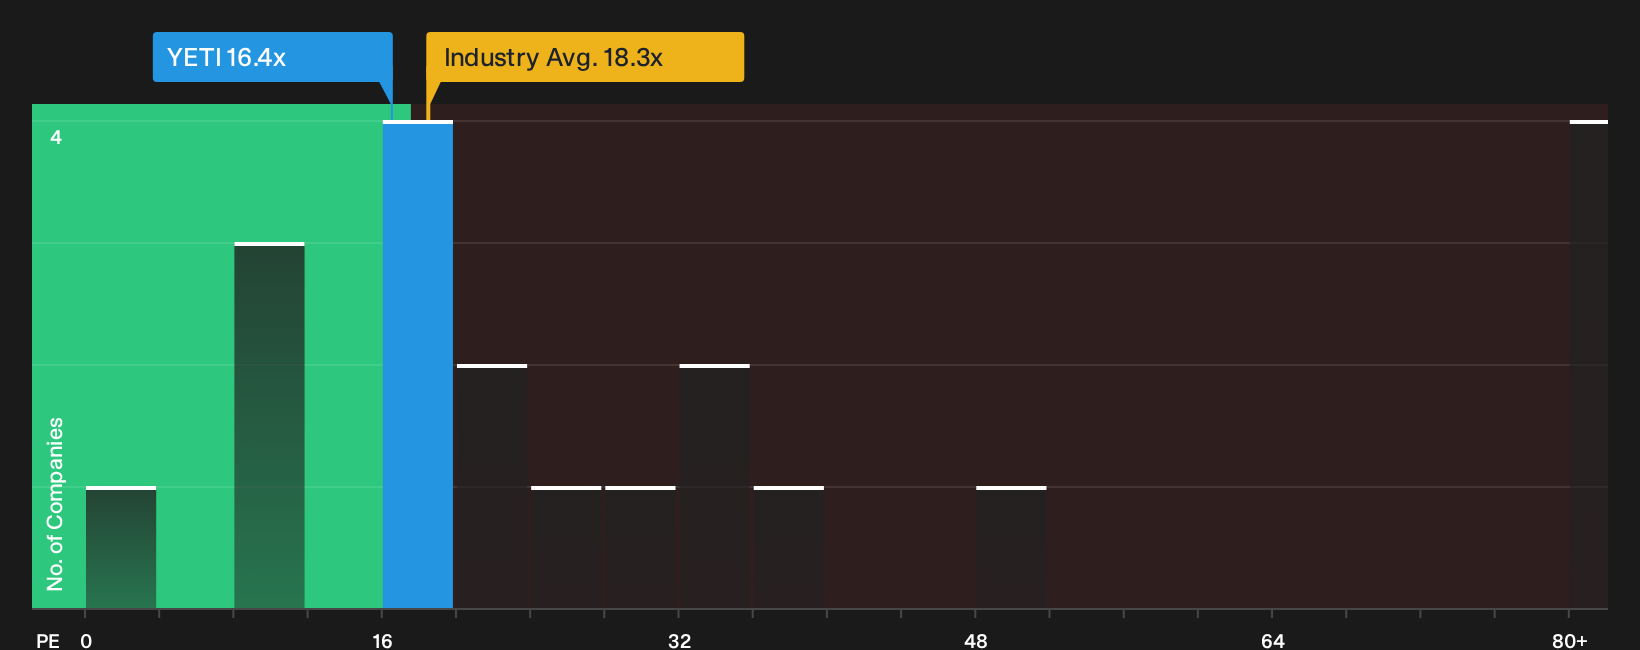
The P/E ratio suits YETI Holdings because it is a branded consumer business where earnings power matters at least as much as asset value. On this measure, YETI trades on a P/E of roughly 16.4x. That sits below the Leisure industry average of about 18.3x and also trails the broader peer group on roughly 25.2x, which might initially look like a discount for the stock.
The fair P/E multiple for YETI Holdings, based on its profile and risk characteristics, is estimated at about 14.8x. The current 16.4x level is slightly higher than that mark, so the shares screen as overvalued on this model even though the headline P/E is lower than many peers. That gap is not extreme, yet it suggests the market is still paying a premium to what the tailored fair ratio implies.
On the P/E test alone, YETI Holdings looks overvalued relative to the earnings multiple implied by its own fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
The YETI Holdings Narrative: What Would Justify Today's Price?
Narratives on YETI Holdings pick up where this valuation puzzle leaves off, by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each scenario links its numbers to a specific view on future margins, expansion and risks that you can revisit on Simply Wall St’s Community page as fresh information comes through.
One of the top community narratives on YETI Holdings: 6% undervalued
"The proliferation of private label and direct-to-consumer outdoor brands, enabled by aggressive e-commerce competitors, threatens to erode YETI's pricing power and long-term brand loyalty."
Read one of the top narratives on YETI Holdings
Do you think there's more to the story for YETI Holdings? Head over to our Community to see what others are saying!
The Bottom Line
YETI Holdings still screens as overvalued on its tailored P/E work, so the current tag already bakes in a fair amount of optimism about the brand’s earnings power. Broader valuation checks look mixed rather than outright cheap, which means you are not being clearly paid for the execution and competitive risks flagged earlier. The core question for both bulls and bears is whether YETI can sustain strong enough profitability to justify that premium, or whether the multiple needs to drift lower if growth, pricing, or consumer appetite for premium gear soften from here.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com