


Walmart (WMT) Stock Stays Reasonable On Restaurant Delivery Expansion
Walmart stock has more than doubled over the past five years, yet current valuation checks suggest it now looks roughly in line with the market rather than like a clear bargain. Recent product moves in fast delivery and restaurant partnerships keep the growth story in focus, while the latest value score leans cautious on how much is already reflected in the share price.
- Walmart has delivered a 136.4% return over the past five years, which puts long term holders in a strong position and raises the bar for new buyers looking for further upside.
- Expansion into restaurant delivery and ultra fast fulfillment can support revenue and customer loyalty, while rising cost pressures and regulatory scrutiny on areas like pharmacies and pricing remain a drag on how much investors may be willing to pay.
- On the broader checks, Walmart screens as not especially cheap, with none of the six valuation cross checks flagging it as clearly undervalued.
The issue now is whether the current price already captures the last five years of strong gains or still leaves room for further value creation for Walmart shareholders.
Spot opportunities beyond Walmart by scanning hand picked retailers and consumer stocks that currently screen as 31 high quality undervalued stocks for cash flow strength and balance sheet quality.Where Does Walmart Sit on Earnings?
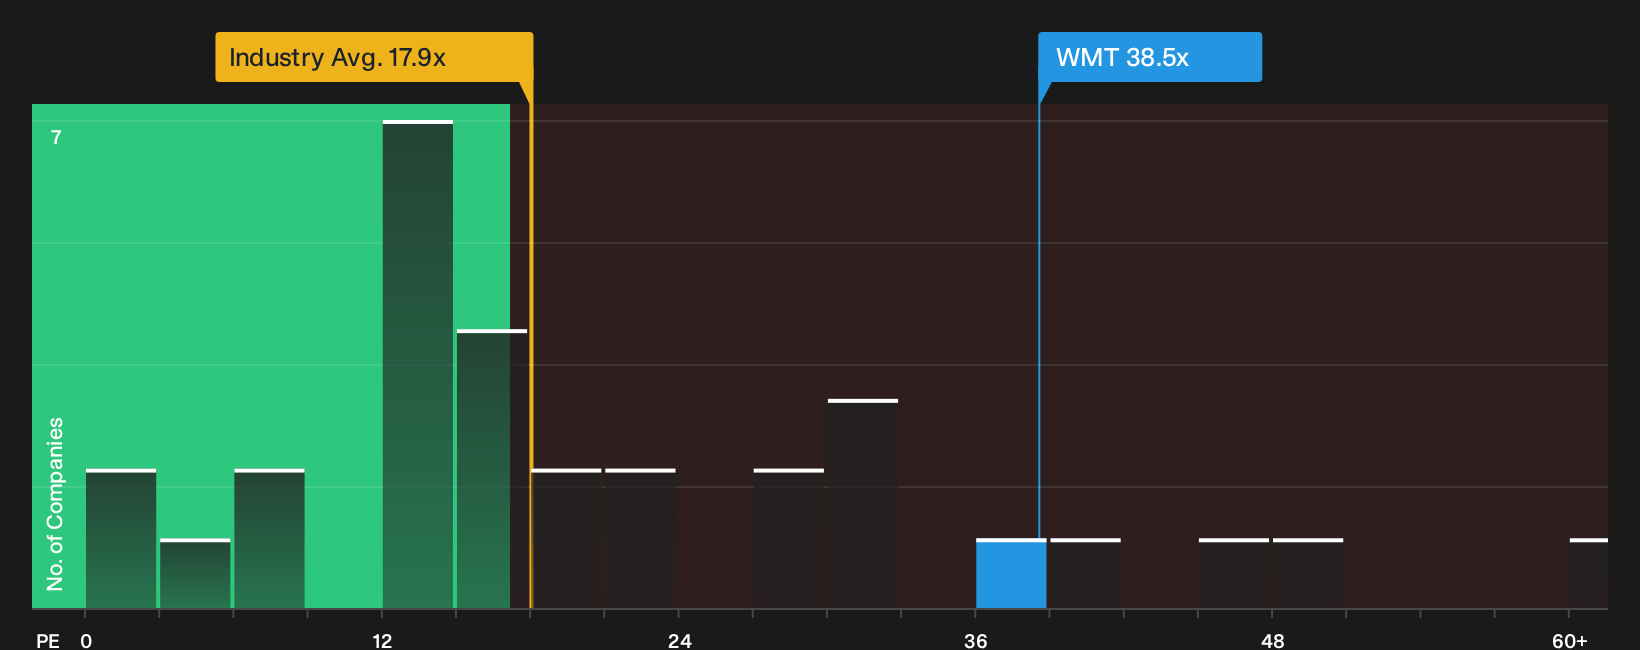
The P/E ratio fits Walmart because earnings quality and consistency tend to be central to how investors judge large retailers. On this lens, the stock trades at about 38.5x earnings, well above the consumer retailing sector average of 17.9x and ahead of the peer group average near 22.8x. That kind of premium suggests investors are currently willing to pay a higher price for each dollar of Walmart profit compared with many other retailers.
The internal “fair” P/E for Walmart, which blends its size, margins, growth profile and risk factors, sits at roughly 37.1x. The current 38.5x level is only slightly higher than this reference point, so the share price does not screen as sharply expensive or obviously cheap on earnings alone. Despite recent attention on Walmart’s push into ultra fast delivery and restaurant partnerships, the P/E still lines up close to what this framework flags as appropriate for the business.
On the P/E multiple, Walmart stock looks priced roughly in line with what its earnings profile would suggest.
See what the numbers say about this price — find out in our valuation breakdown.
The Walmart Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Walmart pick up where the valuation work leaves off and spell out what kind of future the market is currently pricing in for revenue, margins and earnings. Rather than a single output from a ratio or model, these narratives describe the underlying path those numbers assume so you can watch how Walmart's actual progress lines up with that story over time. They sit on Simply Wall St's Community page as a reference point for what would need to change for the stock to look materially richer or cheaper than it does today.
One of the top community narratives on Walmart: 17% undervalued
"Expansion of high margin business streams Walmart Connect, marketplace, and Walmart+ memberships is diversifying Walmart's income base beyond retail..."
Read one of the top narratives on Walmart
Do you think there's more to the story for Walmart? Head over to our Community to see what others are saying!
The Bottom Line
Walmart now trades on a P/E that lines up closely with its own fair multiple, so the market is already assigning it a full quality premium rather than a discount. Broad valuation checks lean cautious, which suggests the easier money was made earlier and fresh upside depends less on a rerating and more on how well the business delivers on its newer profit streams.
What really separates bulls and bears from here is whether Walmart converts those higher margin areas and delivery pushes into durable earnings power that justifies keeping, or even extending, that premium multiple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com