


Cybersecurity Partnership Could Matter For Sopra Steria Stock (ENXTPA:SOP)
- In September 2026, Sopra Steria announced a partnership with German software vendor VMRay, integrating its advanced malware and phishing analysis into security operations centres in France and Norway, where it already processes close to 1,000 suspicious files each month for major clients.
- The link to VMRay, supported by Sopra Steria’s indirect shareholding via Tikehau Capital, deepens its European cyber ecosystem and gives the group greater influence over product roadmaps, integration and end to end delivery, rather than acting as a simple reseller.
- We will now explore how this deeper integration of VMRay’s malware analysis capability could influence Sopra Steria’s broader investment narrative.
Scan beyond Sopra Steria Group and this VMRay deal by reviewing our hand picked 98 resilient stocks with low risk scores built for investors who care about resilience as much as upside potential.
Sopra Steria Group Investment Narrative Recap
Belief in Sopra Steria Group as an investment story rests on confidence that its mix of consulting, software and cybersecurity can offset structural pressure in traditional IT services. The VMRay integration leans into that. It supports the push toward higher value security work, which sits close to current demand for European digital sovereignty and mission critical systems.
The most immediate swing factor still looks like operational execution. Management needs to keep margins under control despite employee cost pressure and high attrition, while turning negative free cash flow and working capital strain into something more stable. The VMRay deal helps the offering, but does not directly solve those cash and cost issues.
Among recent themes, the ramp up of AI powered services and sovereign cloud projects is most relevant to this cybersecurity story. VMRay’s malware analysis feeds into that broader push toward higher margin, expertise driven work that can differentiate Sopra Steria Group against commoditised integration and infrastructure contracts.
For catalysts, the key question is whether these security and AI contracts scale quickly enough to offset sluggish organic revenue in core European markets and dependence on public sector and financial services. Successful cross sell of VMRay alongside existing cyber partners such as Sekoia and HarfangLab would reinforce that higher value mix, while weak take up would leave the business more exposed to pricing pressure in legacy services.
Sopra Steria Group's current earnings of €301.1 million are projected by analysts to move to €398.9 million by 2029. This implies a revenue path that reaches €6.5 billion and rests on 4.0% yearly top line growth, which together would mean an earnings increase of about €97.8 million over that period.
Uncover why Sopra Steria Group's fair value points to a 37% potential upside to its current price, which could narrow quickly if expectation catches up.
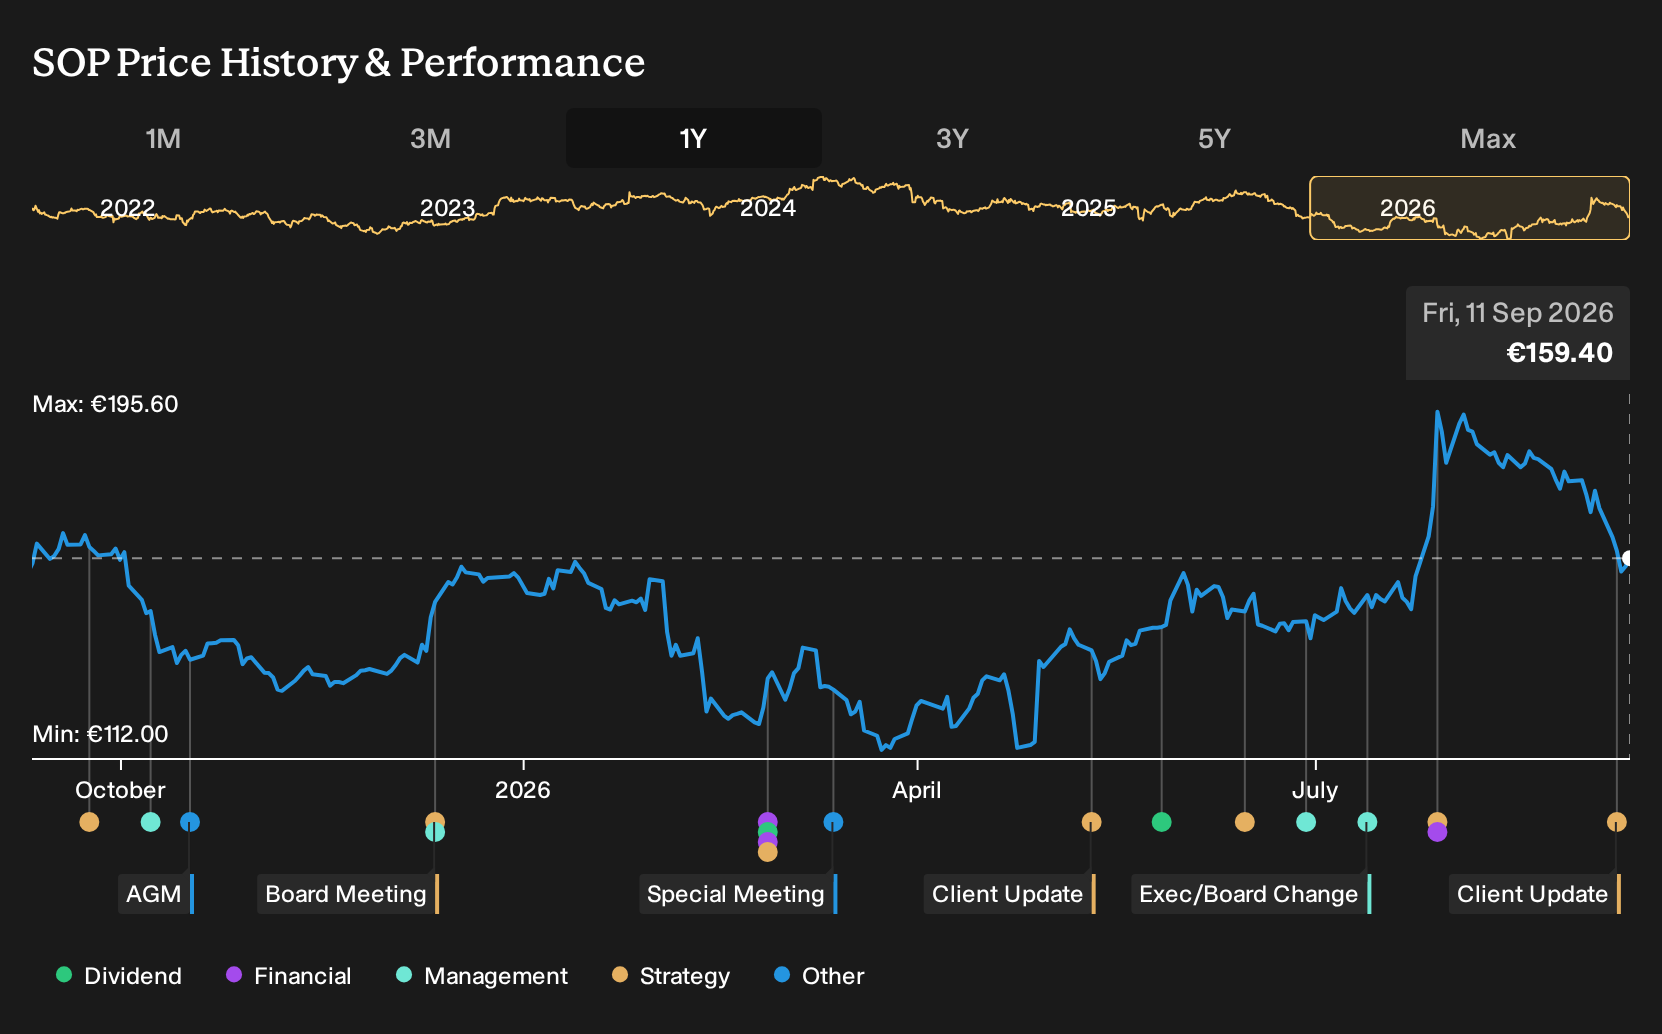
Exploring Other Perspectives
One alternative view puts Sopra Steria in a slower lane. The most cautious analysts were pencilling in only 2.7% annual revenue growth to about €6.2b and earnings of roughly €332.7 million by 2029. You can treat the new VMRay partnership as a fresh test of that cautious script and compare both narratives for yourself.
Explore 3 other Sopra Steria Group fair value estimates, including one that suggests it could be worth just €161.75.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sopra Steria Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sopra Steria Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sopra Steria Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sopra Steria Group?
If the Sopra Steria Group story has sharpened your thinking, use that momentum to widen your watchlist. The Simply Wall St Screener lets you apply the same kind of disciplined filters across a broader universe so you can compare quality, resilience and income potential side by side.
- For investors who care most about capital protection, start with a 98 resilient stocks with low risk scores that aims to keep volatility in check while you focus on long term compounding.
- If income is the priority, assess potential payout candidates through a curated 162 dividend fortresses that already clear a 5% yield hurdle.
- When you want growth without giving up on balance sheet discipline, review a 618 high quality undiscovered gems that pair strong fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com