


Biohaven (BHVN) Could Be 82% Undervalued Following FDA Hold On Opakalim Trials
Biohaven (BHVN) is back in focus after the FDA placed a partial clinical hold on pivotal trials for its epilepsy candidate opakalim, prompting a near 15% share decline and a fresh securities investigation.
The FDA action has hit a stock that had been gaining ground, with Biohaven’s 7 day share price return down 18.99% and 30 day share price return down 13.18%. However, its 90 day share price return is still up 4.70% and the year to date share price return is 17.25%, while total shareholder return is down 8.76% over 1 year and 33.46% over 3 years. This suggests recent momentum had been building before the opakalim setback reset risk perceptions.
Contrast Biohaven’s setback with other healthcare names by scanning 39 healthcare AI stocks that could be better positioned around regulatory risk and clinical execution.
Biohaven now looks like a research platform with a bruised share price. The real tension is simple: Does the recent drop leave a strong pipeline on sale or still expensive risk?
Biohaven’s valuation hinges on cash flow, not earnings multiples
For Biohaven, the clearest anchor right now is our DCF model, which points to an estimated future cash flow value of $70.05 compared with a last close of $12.71. That is a wide gap on paper and it matters more here than traditional earnings ratios because Biohaven is loss making and focused on developing a broad pipeline rather than generating current profit.
The SWS DCF model projects future cash flows from the business, then discounts those back to today using a required rate of return. It is essentially a way of asking what those potential future cash streams are worth in present dollar terms, based on a defined set of assumptions about scale, timing, and risk.
A pipeline-heavy biotech such as Biohaven tends to have little or no revenue today, a reported net loss, and heavy spending on trials. In that situation, earnings based multiples give very little signal. As a result, a cash flow driven view can become the main tool for thinking about what investors are paying for the development portfolio versus what those projects might generate if they reach the market.
Investors who want to understand how this valuation is built, including the cash flow trajectory and discounting choices that sit behind the $70.05 figure, can look through the SWS DCF model in detail by using Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $70.05 (UNDERVALUED)
Still, Biohaven’s story can be knocked off course if further FDA actions affect the wider pipeline or if ongoing net losses of US$586.841m limit funding options.
Find out about the key risks to this Biohaven narrative.
Biohaven’s sky high P/B ratio sends a very different signal
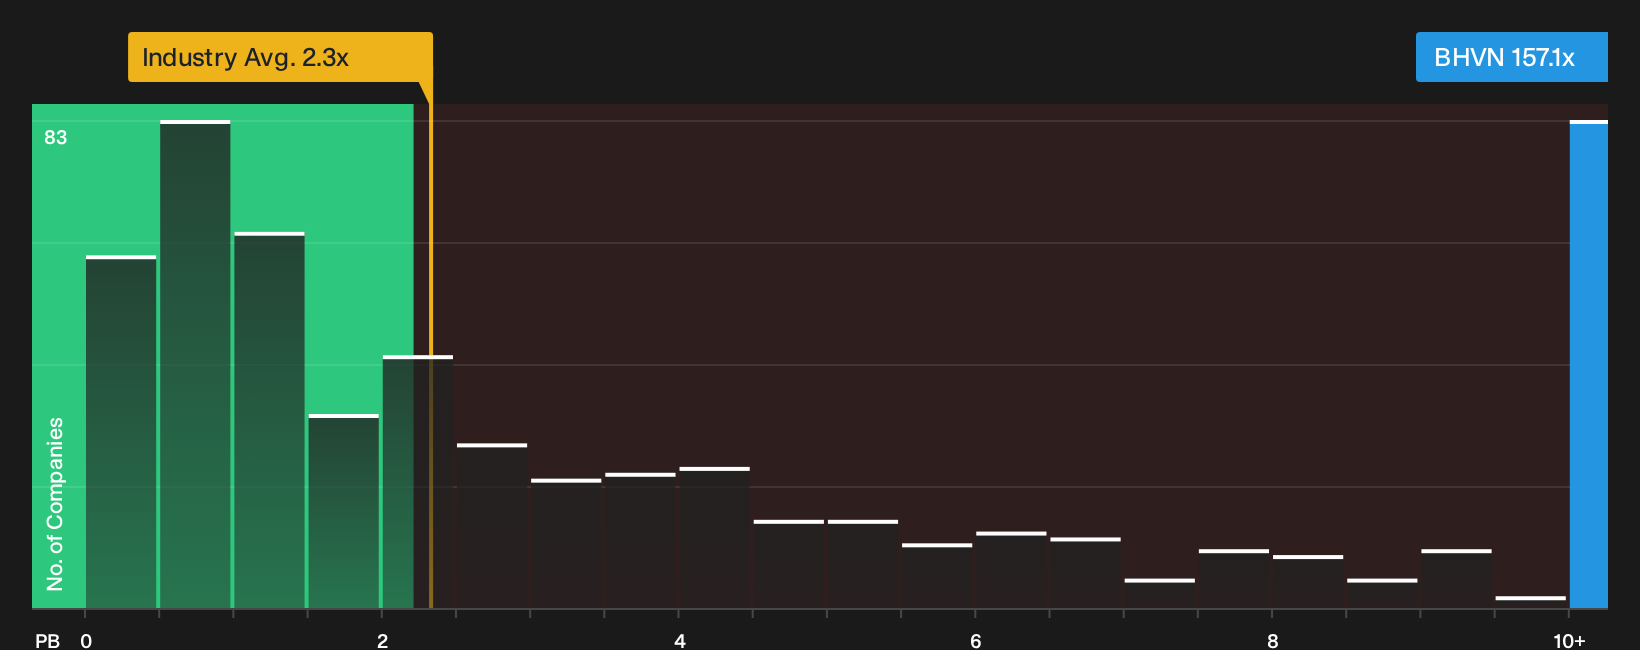
Shift the lens from the SWS DCF model to a simple market yardstick and Biohaven screens very differently. The stock trades on a P/B of 157.1x compared with 2.3x for the wider US Biotechs group and 11.5x for closer peers, which implies investors are already paying a steep premium for a business with no meaningful revenue today.
That kind of gap can flag real valuation risk if expectations on the pipeline or funding runway slip further, so the question for you is whether this premium reflects conviction or just hope.
For a closer look at how this premium compares with where the market could gravitate over time based on fundamentals, you can review the valuation detail via See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Biohaven for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seeing mixed signals around Biohaven’s valuation and risk profile is normal. Move quickly, review the full picture, and weigh the 2 key rewards and 5 important warning signs.
Looking for more Biohaven sized opportunities?
Do not stop with Biohaven. Use the Simply Wall Street Screener to quickly surface fresh ideas that fit your risk appetite and return goals before the crowd does.
- Target potential mispricings in quality businesses by scanning the 32 high quality undervalued stocks that already clear key fundamentals checks.
- Build a steadier income stream by focusing on companies in the 6 dividend fortresses that combine higher yields with underlying business strength.
- Sleep easier during market swings by concentrating on the 11 resilient stocks with low risk scores that score well on resilience and financial robustness.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com