


Victoria's Secret (VSCO) Stock Looks Fairly Valued Following Its 309% Run
Victoria's Secret has delivered a very large 3 year share price gain while current valuation checks suggest the stock now trades close to what a Discounted Cash Flow, or intrinsic value, estimate would imply rather than at an obvious discount. After such a move, the current price level raises a fair question about how much of the recent improvement in the business is already reflected in the market value.
- The stock is up about 309% over three years, which puts extra focus on whether recent momentum has already priced in much of the recovery story.
- Recent progress attracting younger shoppers and refreshing the store footprint can support cash flow expectations. However, any disappointment in profitability or slower demand from these newer customers may put pressure on what investors are willing to pay.
- With a value score of 4 out of 6, Victoria's Secret screens as a mixed picture rather than a clear bargain or clear overvaluation on the broader checks.
The issue now is whether Victoria's Secret at around US$75.65 offers enough potential return to justify the risks after such a strong three year run and a market price that sits close to intrinsic value estimates.
Capitalize on Victoria's Secret's sharp three year move by comparing it with hand picked retailers that still screen as quality at a reasonable price using 32 high quality undervalued stocks.Does Victoria's Secret Look Fairly Valued on Cash Flow?
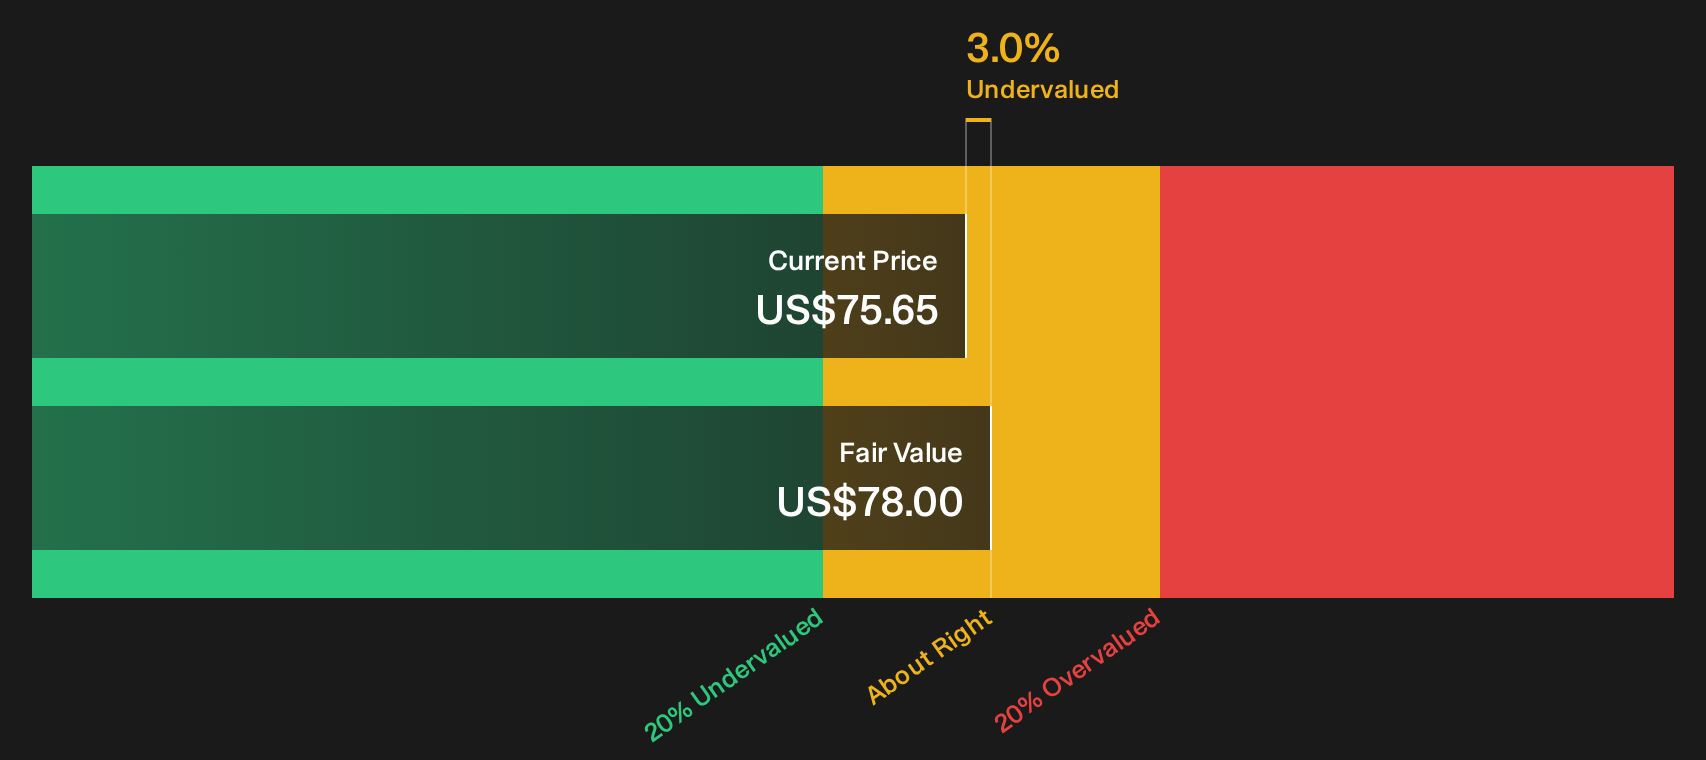
The Discounted Cash Flow model values Victoria's Secret by projecting future free cash flows and discounting them back to today. On this scorecard, the retailer produced latest twelve month free cash flow of about $541.2 million, which the model treats as a base for a recovering but not explosive cash generation profile.
Those cash flow projections translate to an estimated intrinsic value of about $78 per share, only slightly above the recent share price near $75.65, implying roughly a 3.0% gap. The recent drop after guidance for softer Q3 profits helps explain why the market price has not moved much above that modeled value despite stronger recent sales.
On this DCF view, Victoria's Secret shares appear to be roughly fairly valued given the current cash flow outlook and price level.
Victoria's Secret is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Does Victoria's Secret Look Fairly Valued on Earnings?
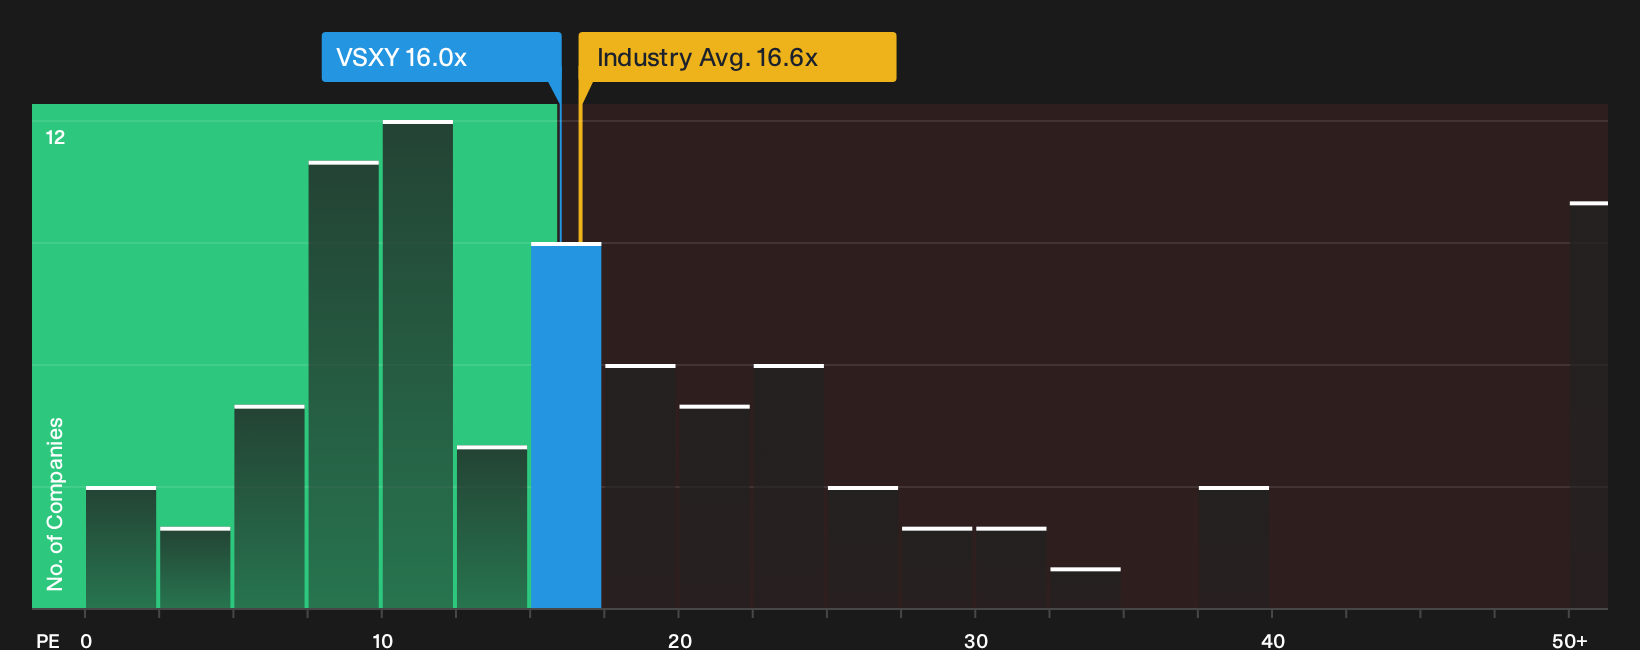
P/E fits Victoria's Secret well because earnings are a key driver of how investors judge established retailers. The stock trades on a P/E of about 16.0x, which is slightly below the Specialty Retail average of roughly 16.6x and above the peer group around 11.9x. That mix points to a modest premium to close peers but without a large gap to the wider sector.
The fair P/E ratio for Victoria's Secret, based on its profile, sits near 17.3x. That is only a little higher than the current 16.0x level, so there is not a big disconnect between what the market is paying and what this framework suggests might be reasonable.
On the P/E yardstick, Victoria's Secret looks priced at roughly fair value rather than clearly cheap or expensive.
See what the numbers say about this price — find out in our valuation breakdown.
The Victoria's Secret Narrative: What Would Justify Today's Price?
Simply Wall St Narratives build on the valuation work on Victoria's Secret by explaining which potential paths for growth, margins and earnings would need to occur for the share price to appear meaningfully higher or lower than it is today. Each Narrative treats fair value as a thesis about the business that you can follow over time, rather than a one-off number on a screen. These Narratives are available on Victoria's Secret's Community page for investors who want that extra layer of context.
Community views on Victoria's Secret split sharply between a turnaround gaining real traction and a brand that still faces stubborn structural hurdles.
Bull case: 18% undervalued
"Strategic pricing power observable in core categories, combined with disciplined promotional strategies and expanded gifting/events, indicates an enhanced ability to offset external pressures..."
Read the full Bull Case to see why Victoria's Secret could be undervalued
Bear case: roughly fairly valued
"Heavy reliance on a physical store footprint, especially in declining malls, combined with incremental investments in store remodels and slow progress in digital transformation is likely to result in structurally higher SG&A and occupancy costs..."
Read the full Bear Case to see why Victoria's Secret could be overvalued
Do you think there's more to the story for Victoria's Secret? Head over to our Community to see what others are saying!
The Bottom Line
Victoria's Secret now screens as roughly in line with intrinsic value on a Discounted Cash Flow (DCF) view and as about right on earnings multiples, so the easy valuation case has faded. The mixed broader checks suggest investors are no longer being paid simply for spotting a mispricing and instead are taking a more balanced risk reward. What matters from here is whether the brand can keep newer shoppers engaged and translate that into steady cash generation, without profit softness or weaker demand forcing the P/E or intrinsic value expectations lower.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com