


Xcel Energy (XEL) Stock Looks Fairly Valued On Dividends But Cheap On Earnings
Xcel Energy has delivered a 42.9% gain over the past three years, yet the valuation signals today are mixed. The Dividend Discount Model suggests the stock is roughly in line with its estimated intrinsic value, while market multiples screen it as cheaper than peers. However, the broader value score leans toward expensive.
- A 42.9% three year return sets a high bar for any further upside because a lot of optimism can already be reflected in the share price.
- For a regulated utility like Xcel Energy, steady capital spending and regulated returns can support valuation, while any pressure on allowed returns or project costs may weigh on what investors are willing to pay.
- The broader checks, including the low value score of 2 out of 6, point to a stock that leans expensive rather than a clear bargain even if some multiples look supportive.
The issue now is whether Xcel Energy's recent share gains have already used up most of the upside that the current intrinsic value estimate and market multiples can justify.
Broaden your watchlist beyond Xcel Energy by reviewing hand-picked utilities and infrastructure stocks in the 39 power grid technology and infrastructure stocks. These may offer a different balance of valuations and return profiles.
Where Does Xcel Energy Sit on Dividends?
The Dividend Discount Model for Xcel Energy projects the future stream of shareholder payouts rather than focusing on free cash flow. With an estimated dividend per share of about $2.54, a return on equity of roughly 10.3% and a payout ratio near 61%, the framework assumes a mature utility that can keep funding dividends from regulated earnings rather than aggressive balance sheet moves.
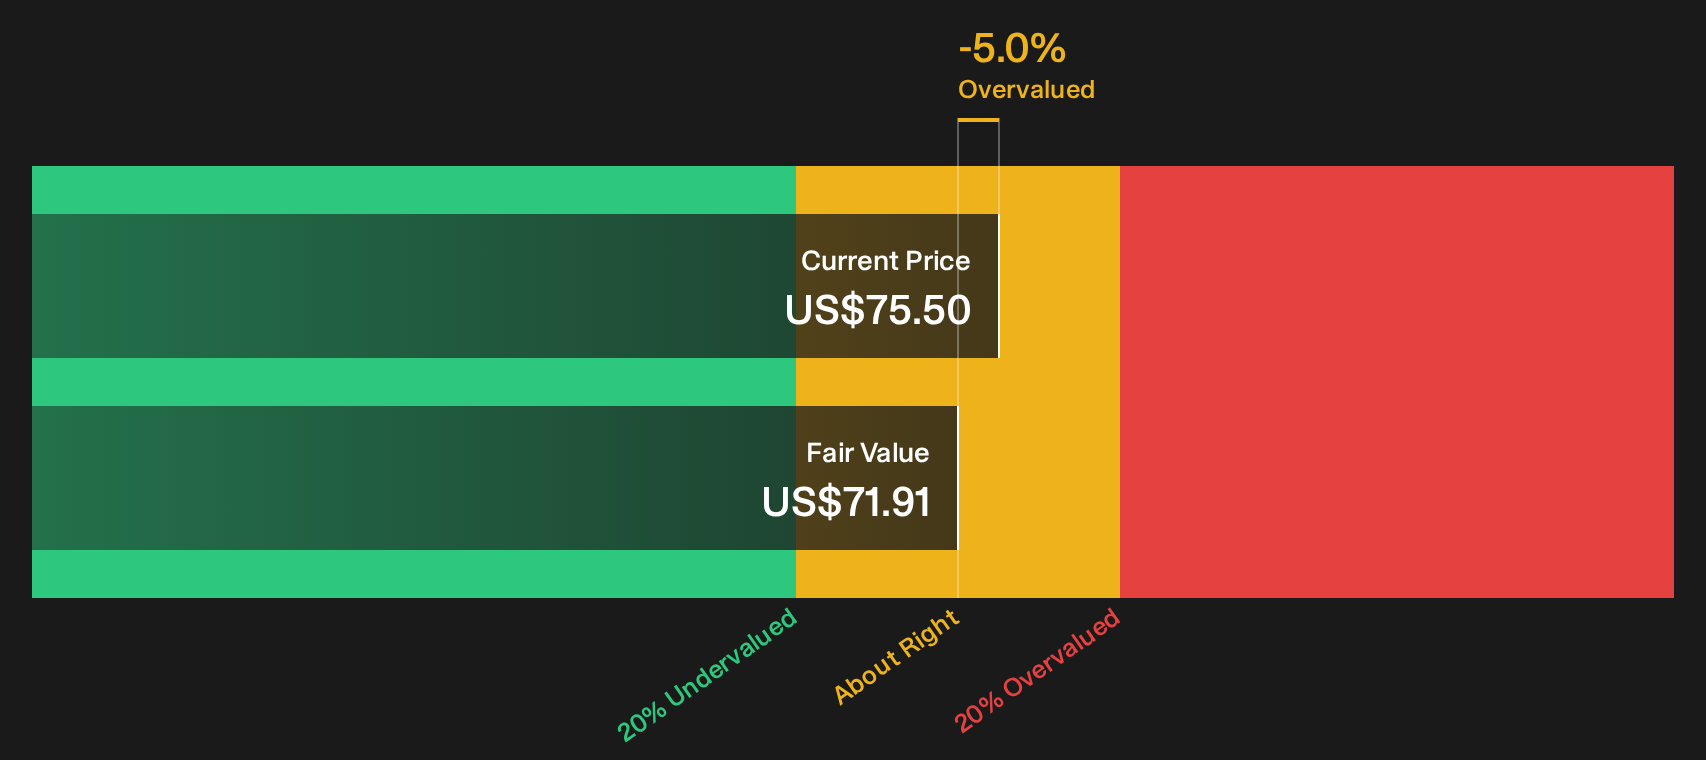
The model caps long term dividend growth at 3.7%, slightly below the 4.0% growth signal implied by recent data. That conservative cap feeds into an intrinsic value estimate of about $71.91 per share. Compared with the current market price, the DDM outcome indicates that Xcel Energy is trading around 5% above that intrinsic mark, so the shares screen as slightly overvalued rather than a clear bargain based purely on dividend power.
On this dividend-based view, Xcel Energy appears roughly fairly valued with only a small tilt toward overvalued territory.
Xcel Energy is fairly valued according to our Dividend Discount Model (DDM), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Is Xcel Energy Still Cheap on Earnings?
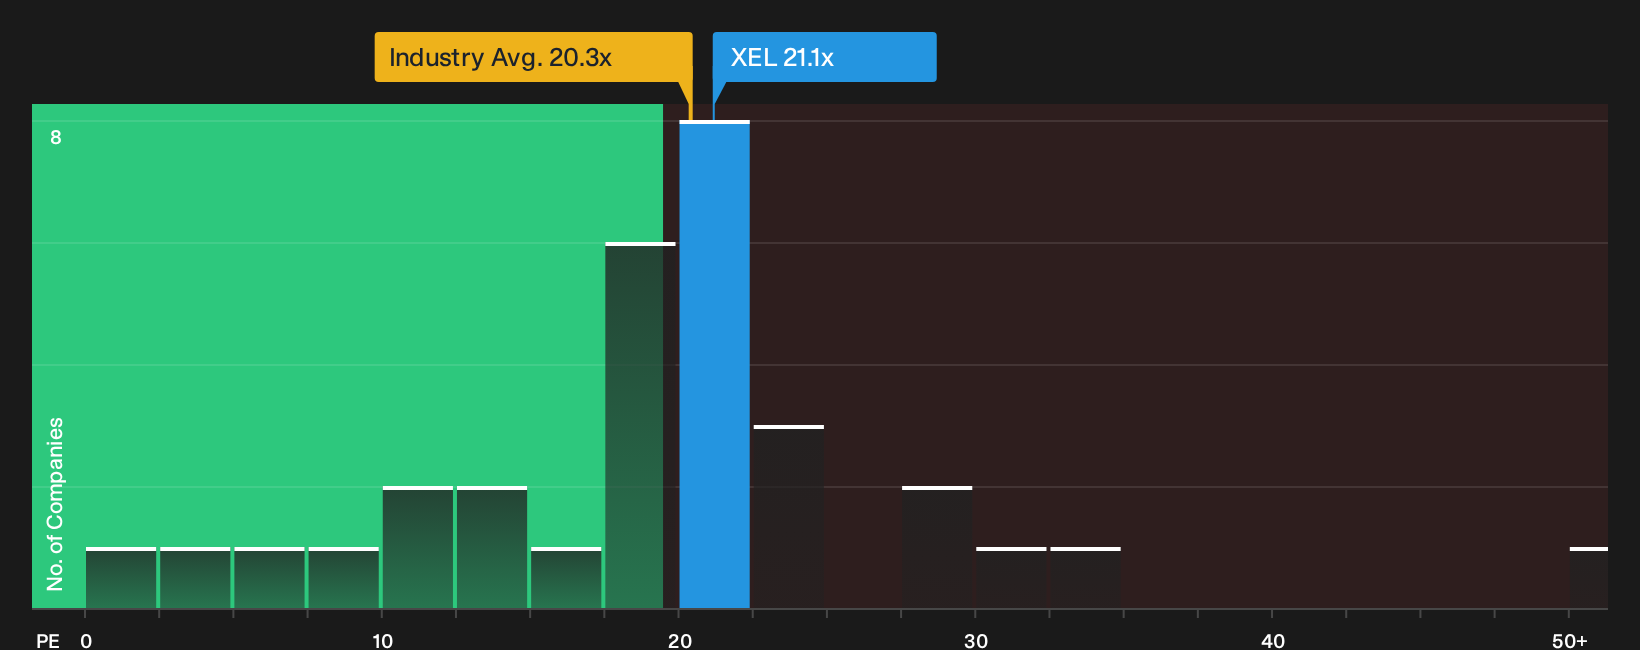
The P/E ratio fits Xcel Energy well because earnings for a regulated utility tend to be steadier than free cash flow. On this measure, the stock trades at about 21.1x earnings, a small premium to both Electric Utilities peers at roughly 18.8x and the broader industry average of about 20.3x. That kind of mark up is not huge, but it does indicate that investors are paying a little extra for each dollar of Xcel Energy profit compared with similar businesses.
The model based fair P/E for Xcel Energy is about 23.9x, which is higher than the current multiple. That benchmark incorporates factors such as the company’s size, sector, profitability and risk profile, and suggests the present share price implies a modest discount to what those fundamentals might justify. For an investor who focuses on earnings based valuation, this gap is the key number to monitor.
On the P/E multiple alone, Xcel Energy appears undervalued relative to the level indicated by the fair value model.
See what the numbers say about this price — find out in our valuation breakdown.
The Xcel Energy Narrative: What Would Justify Today's Price?
Xcel Energy's Simply Wall St Narratives pick up where this valuation puzzle leaves off. Narratives spell out what kind of future growth, margins and earnings path would need to unfold for the share price to be worth materially more or materially less than it is today. Each one ties a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which broad storyline appears to be unfolding on the Community page.
Develop your own narrative on Xcel Energy and provide a data-driven perspective on its future growth, margins, and operational execution. Outline a clear thesis, track it against upcoming results, and compare your view with the rest of the Simply Wall St community.
Do you think there's more to the story for Xcel Energy? Head over to our Community to see what others are saying!
The Bottom Line
Xcel Energy now screens as roughly in line with the intrinsic value indication from the Dividend Discount Model (DDM), while the P/E work still hints at an undervalued earnings stream. That split comes from the dividend model being more sensitive to capital intensity and payout assumptions, whereas the multiple view leans on how investors currently price similar utilities and their growth prospects. Broader valuation checks remain weak, so the key question is whether the modest P/E discount reflects a genuine opportunity or simply the market pricing in the risk that returns on future projects do not fully support a richer tag.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com