


NovoCure (NVCR) Stock Looks Cheap On Sales But Weak On Adoption Risk
NovoCure stock has staged a sharp long term decline but now screens as cheap on several value checks, which puts recent share price volatility against a surprisingly constructive read from the broader valuation tools.
- The share price has fallen about 88.2% over the past 5 years, which signals that expectations on the business have reset dramatically.
- Future treatment adoption can support higher revenue and cash generation, while clinical or commercial setbacks remain a key risk that could keep pressure on the valuation.
- The broader checks lean cheap, with NovoCure earning a value score of 5, which points to an undervalued profile across most metrics.
The issue now is whether the current share price already reflects the long slide in NovoCure or if the stock still embeds more downside risk than upside potential based on today’s fundamentals.
Compare NovoCure's significant drawdown and current value score of 5 with a curated set of other potential mispriced opportunities by scanning 31 high quality undervalued stocks as part of your research.
Does NovoCure Look Undervalued on Sales?
P/S is usually the cleaner yardstick for NovoCure because the business is still loss making on a P/E basis but does report revenue.
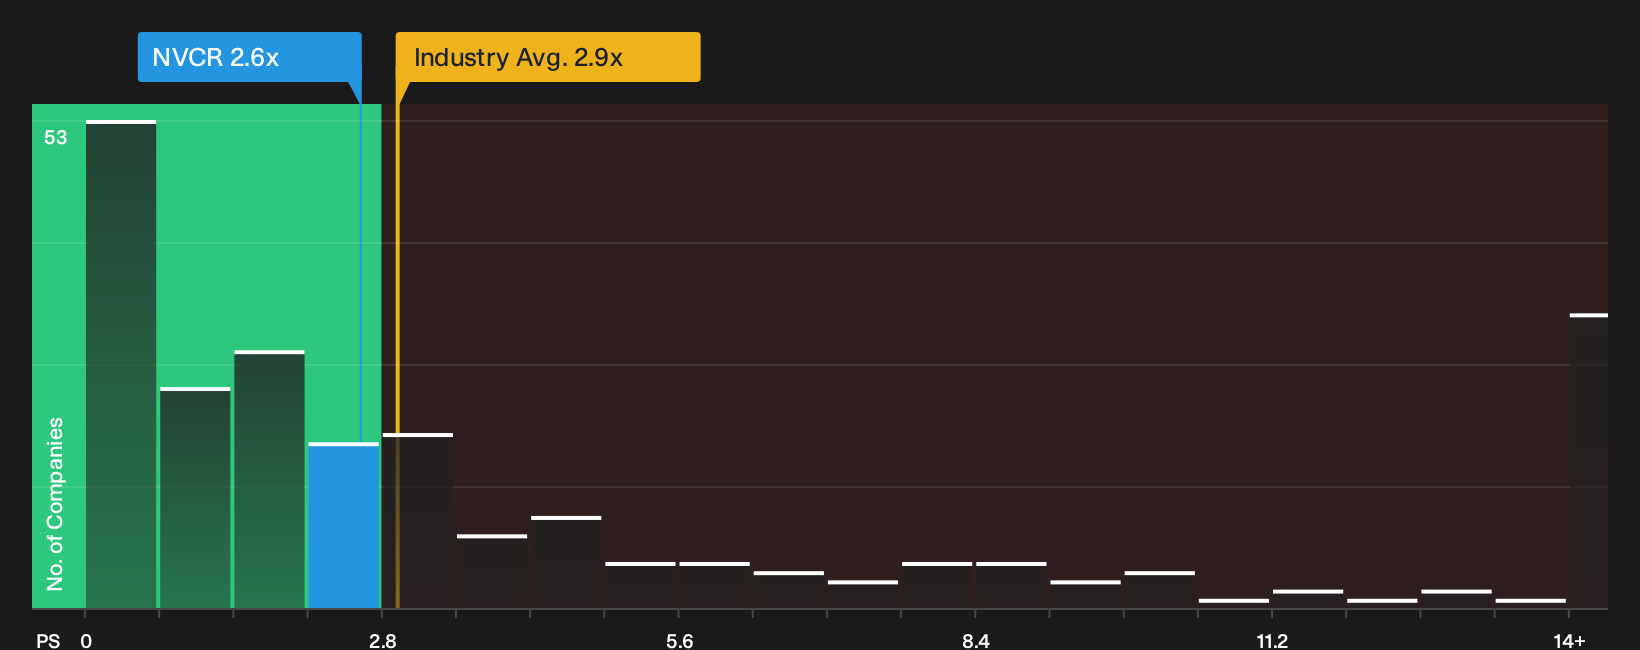
The stock trades on a P/S ratio of 2.6x, which sits below both the Medical Equipment industry average of 2.9x and a much higher peer group average of 7.9x. On a simple comparison, investors are paying less revenue per dollar for NovoCure than for many similar companies in the same space.
The tailored fair P/S multiple is 4.9x, which reflects what might be expected given NovoCure’s sector, size and risk profile. The current 2.6x level is well under that mark, so the share price does not fully reflect the revenue line implied by this framework.
On the preferred P/S yardstick, NovoCure stock appears undervalued relative to both sector norms and its own fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The NovoCure Narrative: What Would Justify Today's Price?
NovoCure’s Simply Wall St Narratives pick up where the valuation puzzle leaves off. They spell out which specific paths for revenue growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price, and they sit on the Community page. Each one turns its fair value view into a clear, testable idea about NovoCure's business that you can track over time as new information arrives.
One of the top community narratives on NovoCure: 68% undervalued
"NovoCure's pioneering position in device-based, non-invasive therapy uniquely aligns with the increasing global demand for alternatives to chemotherapy and radiation..."
Read one of the top narratives on NovoCure
Do you think there's more to the story for NovoCure? Head over to our Community to see what others are saying!
The Bottom Line
NovoCure now screens as undervalued on market multiples, with the current P/S ratio sitting below both sector norms and its tailored fair level. That discount only closes if future treatment adoption and commercial execution support the revenue base implied by those relative checks. The key question is whether the lower multiple reflects mispricing or a justified warning on clinical and regulatory risk. For investors, everything hinges on whether NovoCure can convert its technology into durable sales growth without major setbacks that keep the valuation under pressure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com