


Omnicell (OMCL) Stock Looks Rich After Its 80% Five Year Slump
Omnicell comes into focus with a sharp disconnect. The intrinsic value estimate from a Discounted Cash Flow (DCF) framework points to the shares trading at a steep implied discount, while market multiples suggest the stock already screens as expensive.
- Over the past 5 years, Omnicell has fallen about 80%, which leaves long term holders with heavy losses and raises the bar for any valuation case today.
- The recent integration of TraceLink’s DSCSA compliance solution into Omnicell’s hospital pharmacy systems may support views of steadier demand, but execution risk on complex healthcare software deployments can weigh on how durable those cash flows look.
- With a value score of 3 out of 6, the broader checks give a mixed picture rather than a clear bargain or clear overvaluation.
The stock’s next move may depend on whether investors put more weight on the discounted cash flow upside case or on the richer read coming from market multiples.
Broaden your watchlist beyond Omnicell by scanning 32 high quality undervalued stocks, which also combine discounted valuations with balance sheets designed to better support long term cash flow stories.
Does Omnicell Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here uses projected free cash flows to estimate what Omnicell might be worth today.
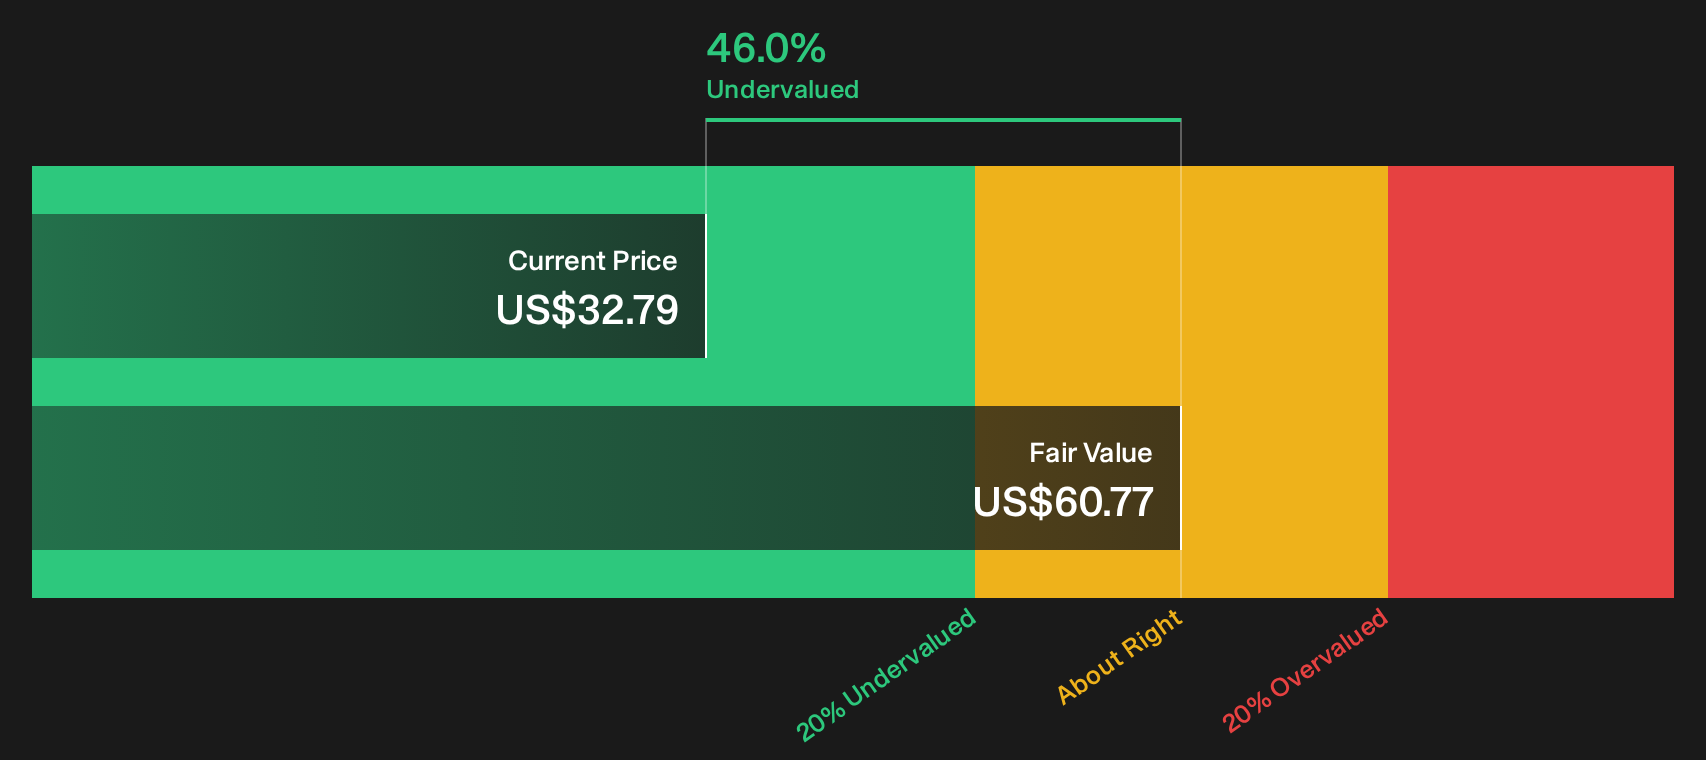
On this framework, Omnicell is modeled as a recovering cash generator, with latest twelve month free cash flow of about $121.2 million and projections that assume free cash flow remains positive rather than swinging back into heavy investment mode. Those projected cash flows feed into a 2 Stage Free Cash Flow to Equity setup, which produces an estimated intrinsic value of about $60.74 per share in dollar terms.
Against the current share price, that output implies the stock screens around 46.0% undervalued. The recent integration of TraceLink’s DSCSA compliance solution into Omnicell’s hospital pharmacy operations helps explain why some investors may see a more durable cash flow profile than the current price reflects.
On this DCF run, Omnicell appears undervalued relative to the cash flows currently built into the model.
Our Discounted Cash Flow (DCF) analysis suggests Omnicell is undervalued by 46.0%. Track this in your watchlist or portfolio, or discover 32 more high quality undervalued stocks.
Does Omnicell Look Pricey on Earnings?
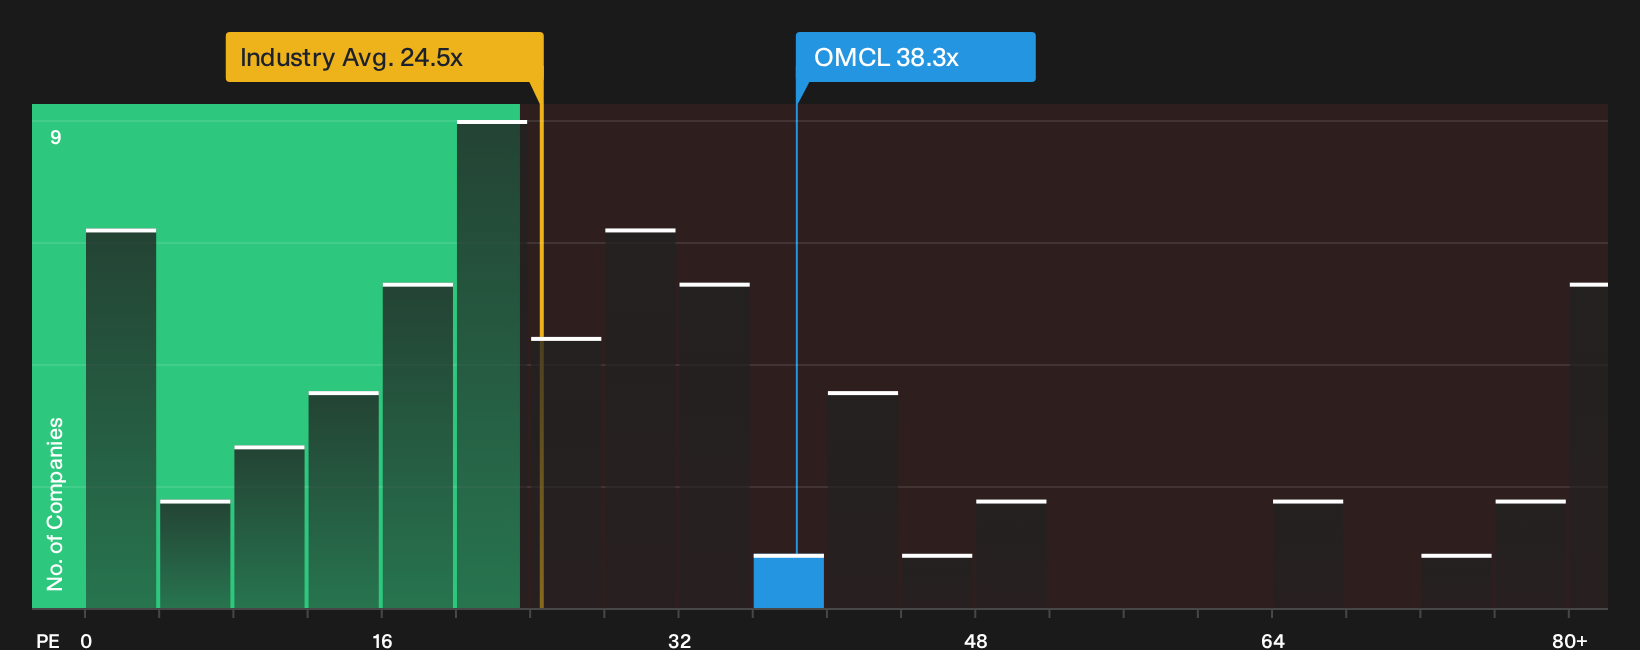
P/E makes sense for Omnicell because investors are paying today for an earnings stream tied to recurring software and services in hospital pharmacies. On this metric, the stock trades on about 38.3x earnings, compared with a medical equipment industry average near 24.5x and a peer group around 28.5x. That is a clear premium to both sector and closer comparables.
The valuation framework here suggests a fair P/E multiple of about 28.3x for Omnicell, based on factors such as margin profile, size and risk. The current 38.3x is therefore well above that reference point, which indicates investors are already attaching a richer price tag than this model supports.
On the P/E yardstick alone, Omnicell screens as overvalued relative to what the fair multiple model and industry benchmarks imply.
See what the numbers say about this price — find out in our valuation breakdown.
The Omnicell Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Omnicell aim to close the gap between the cash flow upside story and the richer P/E reading by spelling out the future that would need to unfold on growth, margins and earnings for Omnicell's current valuation to move meaningfully higher or lower. Where a single ratio or DCF line gives you one output, Narratives unpack the set of operating assumptions behind that figure so you can monitor over time whether the real business lines up with the scenario, all housed on Simply Wall St's Community page.
One of the top community narratives on Omnicell: 27% undervalued
"Analysts have trimmed their Omnicell price targets to a range centered around $45, citing a shift to a $45 fair value estimate from $50…"
Read one of the top narratives on Omnicell
Do you think there's more to the story for Omnicell? Head over to our Community to see what others are saying!
The Bottom Line
Omnicell sits between two stories. The Discounted Cash Flow (DCF) view points to meaningful upside on an intrinsic value basis, while the P/E work suggests the stock already trades on a richer multiple than its peer set and tailored fair ratio imply. With broader checks landing in mixed territory, the split comes down to whether cash flows grow into the current earnings valuation or the multiple settles closer to sector norms. The key question from here is whether Omnicell can execute on its hospital pharmacy software deployments strongly enough for today’s price to reflect a genuine discount rather than a value trap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com