


Magnite (MGNI) Is Getting Attention, So What Is Behind The Latest Update?
Magnite’s recent client moves reshape the TV buying workflow
Magnite (MGNI) is in focus after a run of client announcements, including an expanded ITN partnership that brings agentic tools to local linear TV and tighter links between programmatic buying and traditional workflows.
These announcements have landed as Magnite’s share price has climbed to US$23.77, with a 90-day share price return of 46.28% and a year-to-date share price gain of 48.01%, while the 3-year total shareholder return of 194.91% contrasts with a slightly negative 1-year total shareholder return and a 5-year total shareholder return that is also in decline, suggesting strong medium term momentum but a more mixed long run picture.
Scan the broader TV and CTV opportunity set by reviewing hand-picked 89 AI infrastructure stocks that, like Magnite, are helping automate media buying and power the next wave of digital ad workflows.
Magnite now carries a sharp 3-year return against a flatter 1-year record, which presents a practical fork in the road for you: lean into the recent surge, or wait for a cheaper setup as the valuation numbers line up next.
Most Popular Narrative: 14.1% Undervalued
At a last close of $23.77 versus a narrative fair value of $27.67, the current pricing for Magnite sits below what the most followed thesis implies.
The ongoing increase in global internet penetration and mobile device usage is expanding the digital advertising addressable market, with Magnite seeing growth across CTV, mobile, and new publisher partners (e.g., Spotify, T-Mobile, Redfin), supporting both top-line revenue and diversified inventory supply.
Read the complete narrative. Read the complete narrative.
Want to understand why that valuation gap exists? The narrative focuses on steady revenue expansion, shifting profit margins, and a future earnings multiple usually reserved for premium media platforms.
Result: Fair Value of $27.67 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Magnite narrative hinges on outcomes that can shift quickly if large CTV partners change course or if expected gains from the Google case disappoint.
Find out about the key risks to this Magnite narrative.
Another View: Magnite Through The Cash Flow Lens
The fair value from the most followed Magnite thesis points to a 14.1% undervaluation, yet the SWS DCF model tells a different story. On that measure, Magnite at $23.77 is trading above an estimated future cash flow value of $18.93, which leans closer to overvalued than cheap on cash fundamentals.
For investors who put more weight on cash generation than earnings multiples, that gap raises a blunt question. Is the narrative premium you are paying today one you are comfortable owning through the next ad cycle, or does the cash flow view deserve more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
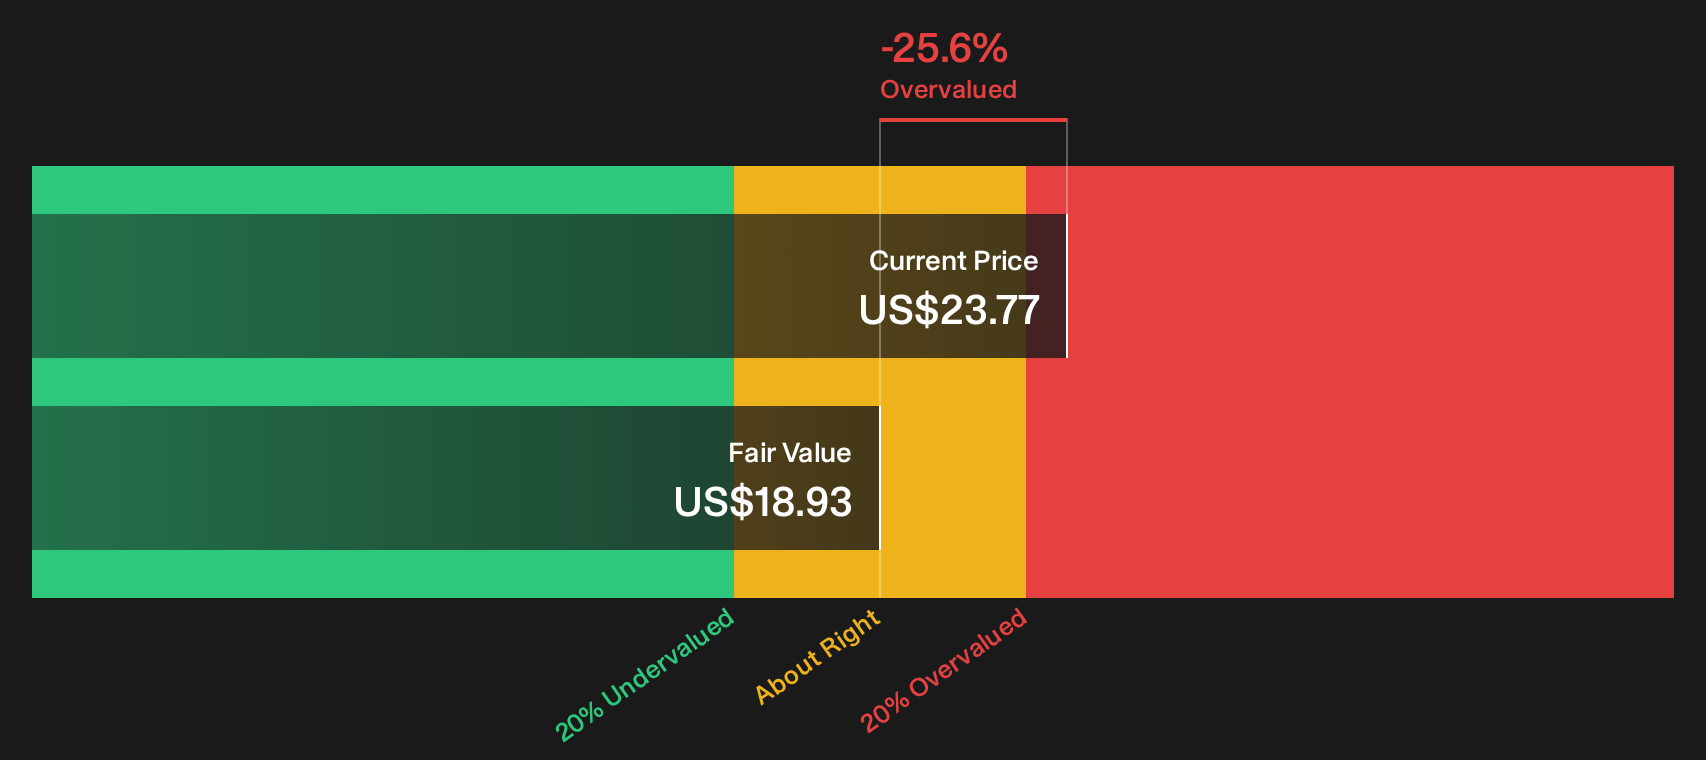
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Magnite for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Magnite’s value and risk profile can be useful if you move quickly and stress test the data yourself using the 2 key rewards and 2 important warning signs.
Looking for more Magnite sized opportunities?
If you stop with Magnite, you risk missing other setups where quality, income, or resilience might better match your goals and time horizon.
- Target potential mispricings by scanning a curated pool of higher quality opportunities through the 31 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle tough conditions.
- Put yield to work for you by assessing 6 dividend fortresses built to generate income while still focusing on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com