


Bank Of Communications (SEHK:3328) Could Be 49% Below Fair Value After Half Year Results
Bank of Communications (SEHK:3328) just wrapped a busy August, combining half year results with fresh dividend decisions that keep cash flowing to both ordinary and preference shareholders.
Investors have leaned into the recent news flow, with Bank of Communications’ share price delivering a 10.34% 1 month share price return and a 22.87% year to date share price return. Total shareholder return over five years has reached 150.08%, suggesting momentum has been building around the dividend and earnings story.
Compare Bank of Communications’ recent dividend moves and price strength with a curated set of income focused opportunities by scanning 165 dividend fortresses alongside this latest half year update.
Bank of Communications now trades at a clear discount to both intrinsic estimates and analyst targets after this strong run. Is the market rightly cautious about the quality of that value, or is it mispricing it?
Preferred P/E of 6.7x: Is it justified for Bank of Communications?
On simple earnings math, Bank of Communications looks inexpensive. The stock trades on a P/E of 6.7x, which sits below the estimated fair P/E of 7x and below the analyst intrinsic value estimate of HK$15.93 against the current share price of HK$8.06.
The P/E ratio compares what you pay today for each unit of earnings with what the market pays for peers. For a large bank with HK$217,952.0m in revenue and HK$90,778.0m in net income, a lower multiple can signal modest expectations around future profits, concern about return on equity, or simply investor preference for faster growing sectors.
Two valuation checks point in different directions. On the positive side, the SWS DCF model flags Bank of Communications as trading at a 49.4% discount to an estimated future cash flow value of HK$15.93. In addition, the current 6.7x P/E is below the modelled fair level of 7x. At the same time, that same 6.7x earnings multiple is above the Hong Kong Banks industry average of 5.3x. This implies the market is assigning a premium relative to local peers that could compress if sentiment shifts back toward the sector average.
Result: Price-to-Earnings of 6.7x (ABOUT RIGHT)
To see how the earnings multiple could adjust over time as conditions change, take a look at the Explore the SWS fair ratio for Bank of Communications
Still, the premium P/E relative to Hong Kong banks and the heavy reliance on Corporate Banking Business revenue mean that any sector rerating or loan quality shock could quickly challenge that value case.
Find out about the key risks to this Bank of Communications narrative.
Another View on Bank of Communications’ Value
The first lens on Bank of Communications focused on its 6.7x P/E. Our DCF model presents a different perspective. On that framework, the shares trade at HK$8.06 versus an estimated future cash flow value of HK$15.93, implying the stock is materially undervalued.
That raises a simple question for you as an investor. Is the earnings multiple missing something about the bank’s long term cash generation, or is the DCF leaning too hard on assumptions that may not play out?
Look into how the SWS DCF model arrives at its fair value.
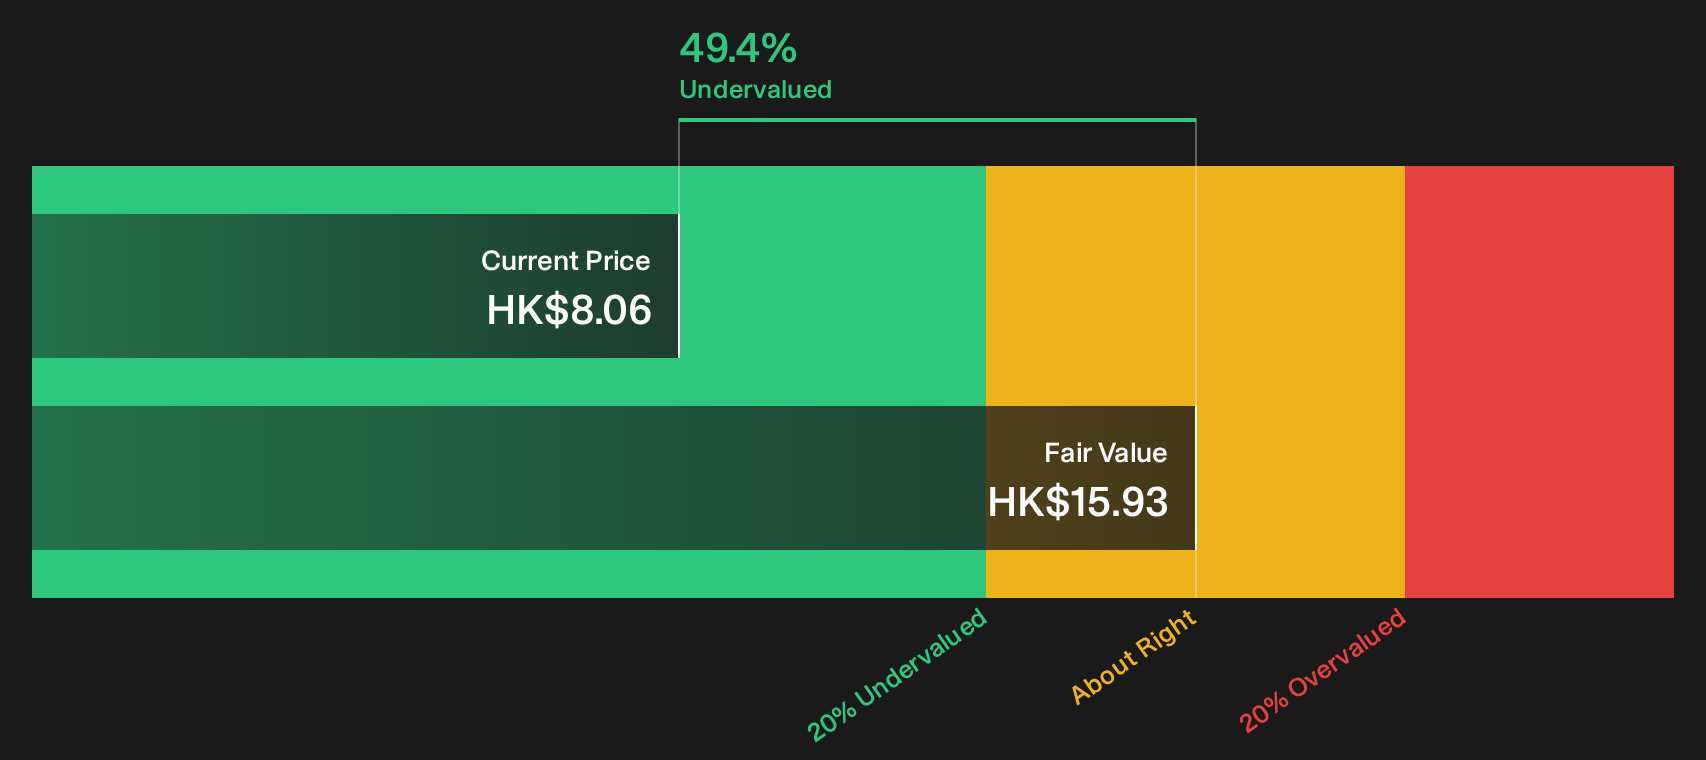
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of Communications for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in this Bank of Communications story. If you want a clear view before sentiment shifts again, consider the 3 key rewards and 1 important warning sign to weigh up the situation.
Looking for more investment ideas beyond Bank of Communications?
If you stop with Bank of Communications, you only see part of the opportunity set. Cast the net wider and let the data surface fresh ideas.
- Target resilient potential by reviewing companies in the 98 resilient stocks with low risk scores that aim to keep volatility in check while you focus on the bigger picture.
- Spot mispriced opportunities early by scanning the 181 high quality undervalued stocks and compare businesses trading below what their fundamentals suggest.
- Build a shortlist of quality income ideas by using the 165 dividend fortresses to focus on companies aiming to deliver durable cash payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com