


Revenue Guidance Raised Might Change The Case For Flotek Industries Stock
- Flotek Industries recently raised its 2026 revenue guidance to a range of $360 million to $370 million, citing a stronger outlook for international chemistry sales in the second half of the year compared with its prior forecast.
- The updated outlook indicates that Flotek Industries expects healthier demand for its chemistry offerings outside the United States, which could shift the mix toward higher value international contracts and potentially support more recurring, service-led revenue streams.
- The focus now is on how this stronger international chemistry outlook may reshape Flotek Industries' existing investment narrative and risk profile.
Flotek Industries Investment Narrative Recap
To own Flotek Industries, you need to believe the chemistry and data analytics mix can keep shifting toward more recurring, contract driven work while customer concentration and commodity exposure stay manageable. The raised 2026 revenue guidance built on international chemistry demand speaks directly to that belief. It supports the near term catalyst, which is proof that larger, longer term agreements can scale outside the US and narrow reliance on a few customers. The main operational risk does not change much. Heavy exposure to oilfield activity and key contracts can still swing margins and cash generation quickly.
The guidance update matters most when set against Flotek Industries' push into higher margin data analytics. Earnings grew 169.3% over the past year and net profit margins moved from 6.6% to 13%, while Data Analytics already contributes about US$48.5 million of US$293.0 million in revenue. Stronger international chemistry expectations could buy management time to execute on more PWRtek and real time monitoring contracts. It may also reduce pressure to lean on additional equity or higher risk funding, given 100% of liabilities currently come from external borrowing rather than customer deposits.
Even so, there is a less comfortable angle to this story that hinges on...
Read the full Flotek Industries narrative to see the case behind these numbers.
Flotek Industries' current analyst narrative points to revenues of US$362.3 million and earnings of US$29.1 million by 2029, based on an assumed 7.3% yearly revenue growth rate and an earnings decline of US$8.9 million from US$38.0 million today.
Flotek Industries' forecasts put fair value at $38.25 compared to $27.88, a 37% upside to its current price that could narrow quickly.
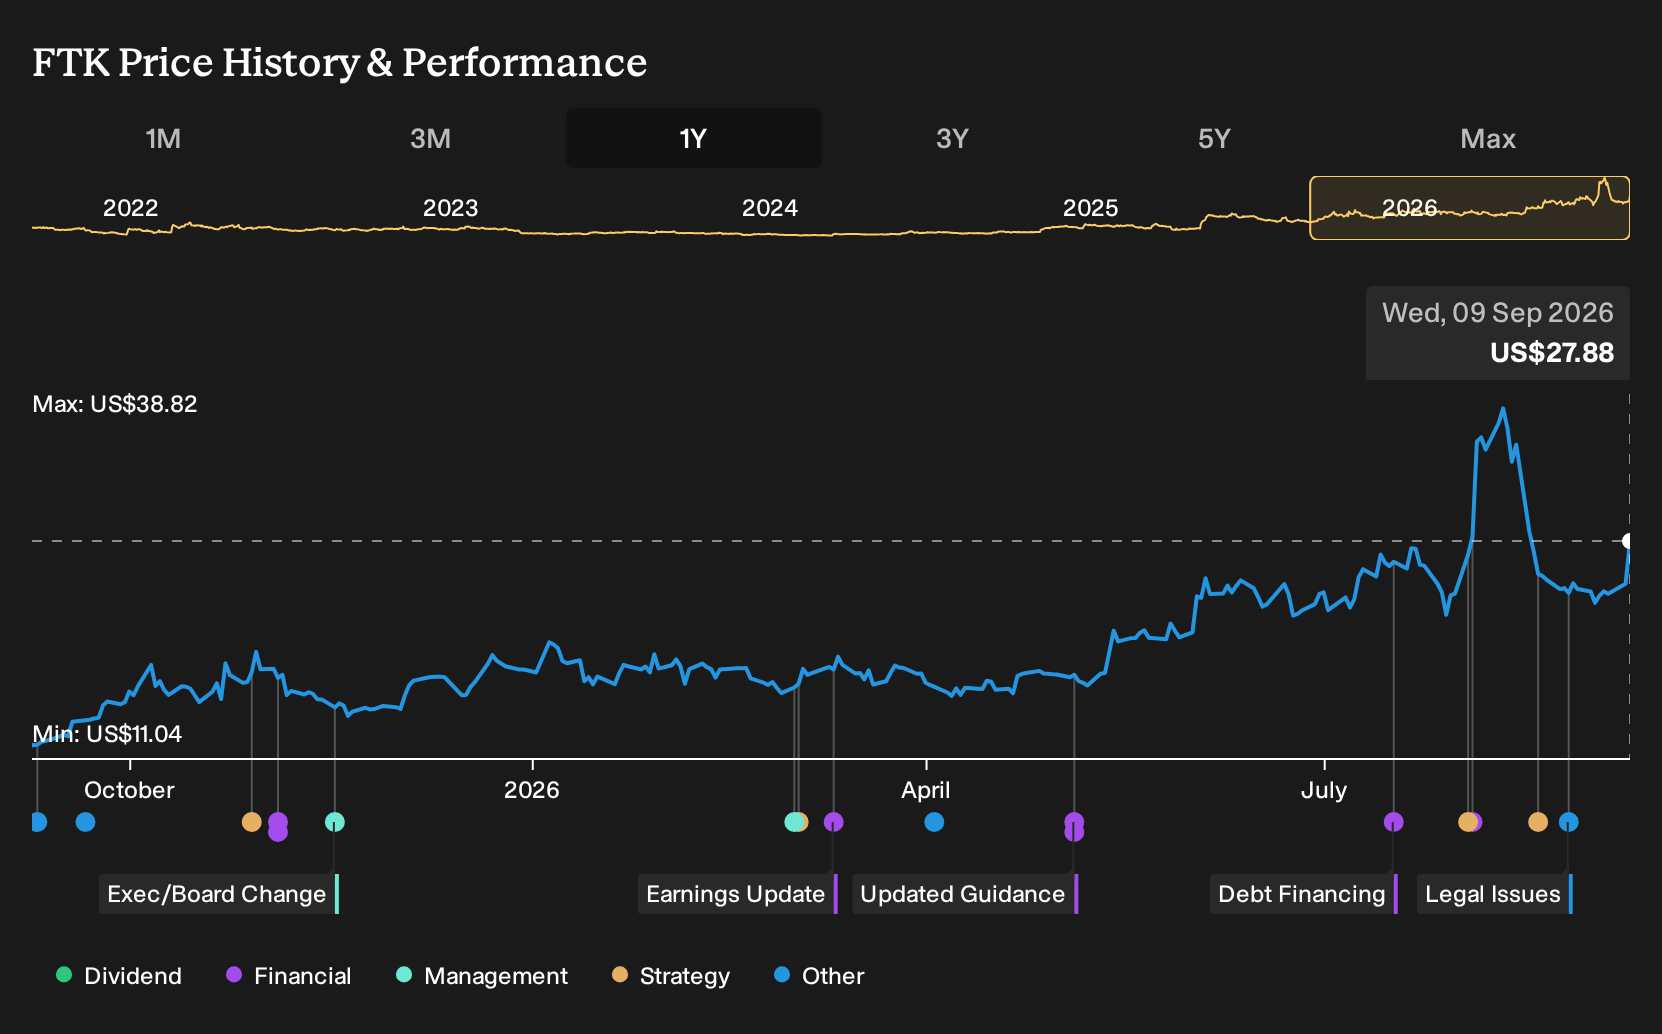
Exploring Other Perspectives
For Flotek Industries, the bullish analysts focus on international contracts as the big swing factor. Before this guidance, they were already modelling revenue of about US$395.3 million and earnings of US$37.5 million by 2029, far above consensus assumptions. Their view appears more optimistic and could change again as the new chemistry outlook is incorporated.
If you want a broader valuation cross-check around Flotek Industries, you can compare the consensus view with 3 other fair value estimates for Flotek Industries.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Flotek Industries research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Flotek Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flotek Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Flotek Industries?
If the Flotek Industries story has sharpened your thinking about recurring contracts, risk and balance sheet strength, it can be useful to compare it with other businesses that share similar qualities. The Simply Wall St Screener helps you do that quickly by filtering the market down to a smaller group that actually fits your criteria.
- If you want to focus on quality at a reasonable entry point, start with a short list of companies that look attractively priced on fundamentals by checking out the 31 high quality undervalued stocks.
- If durability matters more than excitement for you, consider a group of sturdier businesses with conservative financing and strong financial foundations using the 10 resilient stocks with low risk scores.
- If capital preservation and balance sheet resilience sit at the top of your checklist, compare Flotek Industries with a curated list of solid balance sheet and fundamentals (24 results) to see which ones match your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com