


Onto Innovation (ONTO) Tests Its Valuation On Buyback, Earnings And Confident Guidance
Onto Innovation (ONTO) just put a fresh US$400 million share repurchase program on the table, right after reporting third quarter results and issuing new fourth quarter guidance that together give investors a concentrated update on momentum.
Recent trading tells a mixed story for Onto Innovation. The share price is down 11.16% over the past 30 days and has fallen 32.73% over 90 days, yet the year to date share price return is 21.19% and the 1 year total shareholder return is 53.51%. This suggests longer term holders have still been rewarded even as expectations and perceived risk have been reset around the latest earnings, fresh fourth quarter guidance and the new US$400 million buyback authorization.
Scan how Onto Innovation stacks up against a hand picked group of other chip related opportunities that currently screen as 53 AI infrastructure stocks for potential momentum and capital return stories.
After a sharp pullback and a fresh US$400 million repurchase plan, Onto Innovation presents two clear options: add exposure now following the reset, or wait for the valuation to cool further as the numbers settle in.
Most Popular Narrative: 43% Undervalued
Onto Innovation closed at $201.02, while the analyst consensus Narrative on Simply Wall St assigns a fair value of $354.00. This frames the current buyback and recent guidance against a sizable implied valuation gap built on detailed revenue and earnings forecasts using a 12.05% discount rate.
The accelerating adoption of AI packaging and advanced 2.5D and 3D logic architectures is now supported by large multi year orders for Onto Innovation’s Dragonfly systems, including more than US$240 million tied to an HBM customer and over US$200 million from a single OSAT. This can translate into stronger revenue visibility and support for earnings as these tools ship through 2027.
See why 46 investors see Onto Innovation as 43% undervalued.
Result: Fair Value of $354.00 (UNDERVALUED)
Still, that bullish Onto Innovation narrative hinges on sensitive points, including investigations into potential fiduciary breaches and the sizeable US$720 million commitment to Rigaku delivering as planned.
Find out about the key risks to this Onto Innovation narrative.
Another View on Onto Innovation’s Valuation
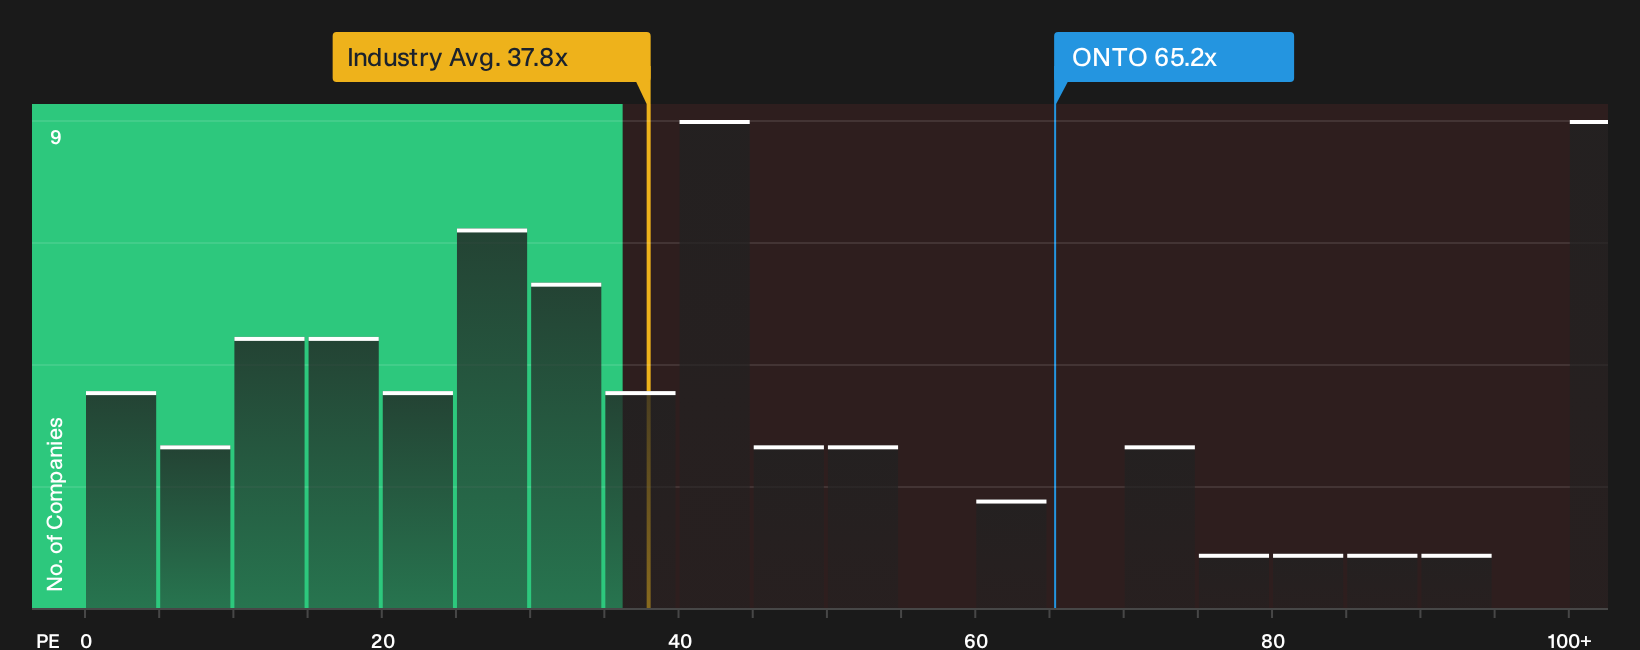
The earlier narrative leans on future earnings and fair value estimates that imply Onto Innovation is undervalued. The current P/E of 65.2x tells a very different story. It is well above both the US Semiconductor industry at 37.8x and peers at 27.1x, and it is also ahead of a 52.6x fair ratio that the market could move toward over time.
If earnings do not catch up as quickly as forecast, that kind of premium can turn into valuation risk rather than opportunity, especially for anyone focused on shorter holding periods. It leaves a simple question for you as a shareholder or prospective buyer: Which signal carries more weight right now, the optimistic fair value gap or the rich multiple already in the price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Onto Innovation’s valuation can cut both ways, so move quickly, review the full data set and weigh both the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Onto Innovation?
If Onto Innovation has sharpened your thinking, do not stop here. Put that momentum to work by scanning other opportunities that match your preferred risk and return profile.
- Target dependable cash generators by reviewing a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced quality with a 19 high quality undiscovered gems that highlights strong fundamentals the market may not be fully watching yet.
- Stack potential income streams by tapping into a 8 dividend fortresses that focuses on higher yield payouts with support from underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com