


Do Wall Street Analysts Like Entergy Stock?
Entergy Corporation (ETR), headquartered in New Orleans, Louisiana, produces and retails distribution of electricity. Valued at $51.4 billion by market cap, the company delivers electricity to utility customers in Arkansas, Louisiana, Mississippi, and Texas. Entergy also owns and operates nuclear plants in the northern U.S.
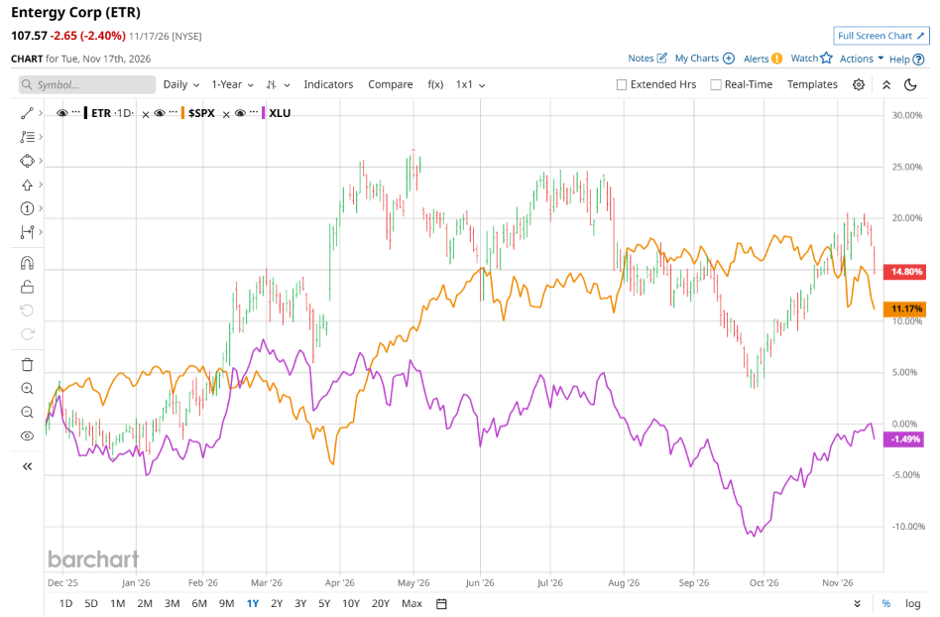
Shares of this leading integrated energy company have outperformed the broader market over the past year. ETR has gained 12.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10%. In 2026, ETR stock is up 16.4%, surpassing the SPX’s 7.2% rise on a YTD basis.
Zooming in further, ETR’s outperformance is also apparent compared to State Street Utilities Select Sector SPDR ETF (XLU). The exchange-traded fund has declined about 3% over the past year. Moreover, ETR’s double-digit returns on a YTD basis outshine the ETF’s 1.7% gains over the same time frame.
Entergy’s outperformance has been propelled by surging electricity demand from hyperscale AI data centers, highlighted by major infrastructure agreements like its expanding Alphabet Inc. (GOOG) buildout in Arkansas, alongside robust industrial load growth across the Gulf South. This secular demand tailwind has enabled the utility to expand its multi-year capital investment plan and secure constructive regulatory rate approvals, driving stronger-than-expected earnings growth, upward guidance revisions, and a 6% dividend increase. Additionally, broader market volatility and retreating Treasury yields have fueled defensive sector rotation into power utilities, further lifting investor sentiment and supporting share price gains.
On Nov. 2, ETR shares closed down marginally after reporting its Q3 results. Its adjusted EPS of $1.98 beat Wall Street expectations of $1.71. The company’s revenue was $4.4 billion, topping Wall Street forecasts of $4.2 billion. ETR expects full-year adjusted EPS in the range of $4.35 to $4.45.
For the current fiscal year, ending in December, analysts expect ETR’s EPS to grow 12.8% to $4.41 on a diluted basis. The company’s earnings surprise history is mixed. It beat or matched the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
Among the 22 analysts covering ETR stock, the consensus is a “Strong Buy.” That’s based on 15 “Strong Buy” ratings, one “Moderate Buy,” and six “Holds.”
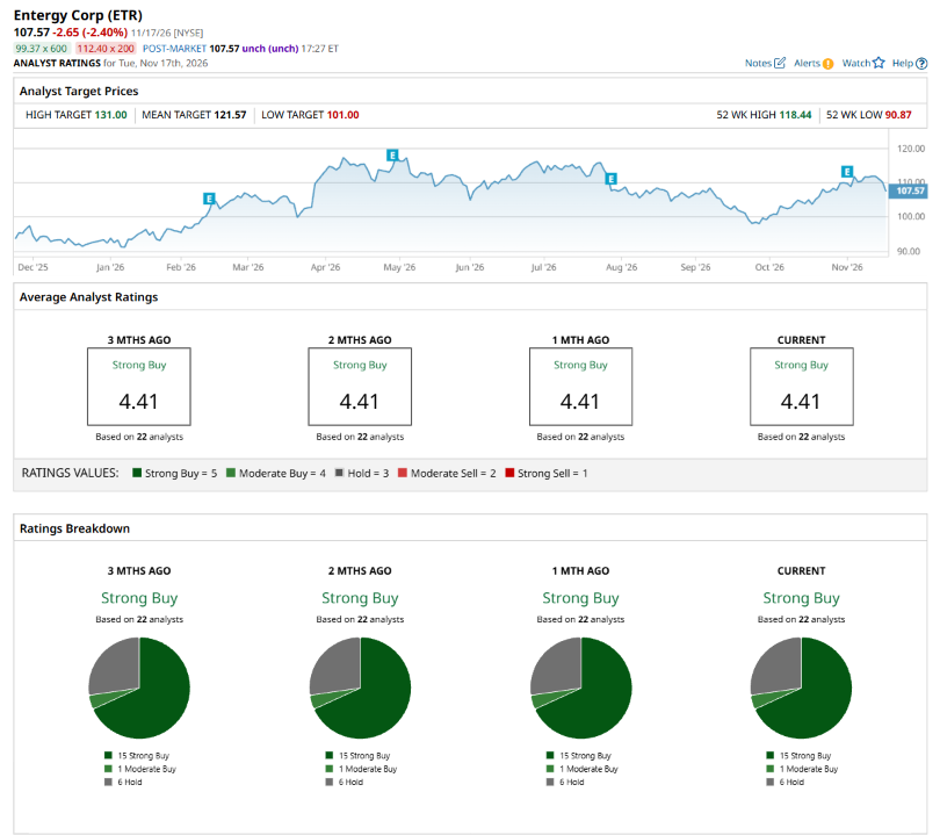
The configuration has been consistent over the past three months.
On Nov. 3, James Thalacker from BMO Capital reiterated a “Buy” rating on ETR, with a price target of $124, implying a potential upside of 15.3% from current levels.
The mean price target of $121.57 represents a 13% premium to ETR’s current price levels. The Street-high price target of $131 suggests an upside potential of 21.8%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.