


AI Product Push Might Change The Case For Investing In Apple (AAPL)
- Apple reported record full year revenue of US$478.834b and net income of US$132.175b, while also issuing multiple new fixed and floating rate notes across maturities from 2028 to 2036 and affirming a US$0.27 per share dividend payable on November 16, 2026.
- Alongside this funding activity and earnings strength, Apple is leaning into AI driven devices and services, from the foldable US$1,999 iPhone Duo and Siri AI upgrades to new Siri based home hardware and a higher priced Apple TV+ service backed by more premium content.
- This article examines how this AI heavy product cycle, including Siri AI and iPhone Duo, shapes Apple’s evolving long term investment narrative.
Scan how Apple’s AI push compares with peers by zeroing in on hand picked 53 AI infrastructure stocks powering the devices, apps, and services you use every day.
Apple Investment Narrative Recap
To own Apple here, you need to believe the ecosystem can keep turning record use into steady earnings, even as hardware cycles and costs shift. According to Bob_B, a Simply Wall St Community investor who wrote the Narrative, small quality of life features such as iPhone call screening show how tightly Apple can bind customers. The short term swing factor is whether AI features and higher price points, especially on iPhone Duo and Siri AI devices, offset rising memory costs that are pressuring gross margin guidance.
The biggest current risk is that premium pricing and supply constraints in Mac and iPad fail to match the demand Apple is priming through AI upgrades and services. ETF flows, recent leadership changes and the shutdown of the 28 year old Support Community all sit around the edges of that story. These do not alter the central question: Can Apple keep customers happily paying more for on device AI and content without letting costs or complexity eat into profitability?
The ROLR mobile app launch inside Apple’s App Store is a small headline next to iPhone Duo and Siri AI, yet it underlines a key catalyst. Third party developers continue to bring specialised, real money services onto iOS, which keeps the iPhone at the center of how users trade, watch sports and manage money. That reinforces why AI features and call tools, like the robocall screening Bob_B highlights, matter for retention.
For you as an investor, the interest is less about ROLR’s business and more about what it signals for Apple’s Services flywheel. Every new high engagement app increases time spent in Apple’s ecosystem, which can support App Store fees, payment volumes and the case for premium hardware. The risk is regulatory or compliance scrutiny around areas like real money markets and payments that could affect how aggressively Apple can lean into these use cases over time.
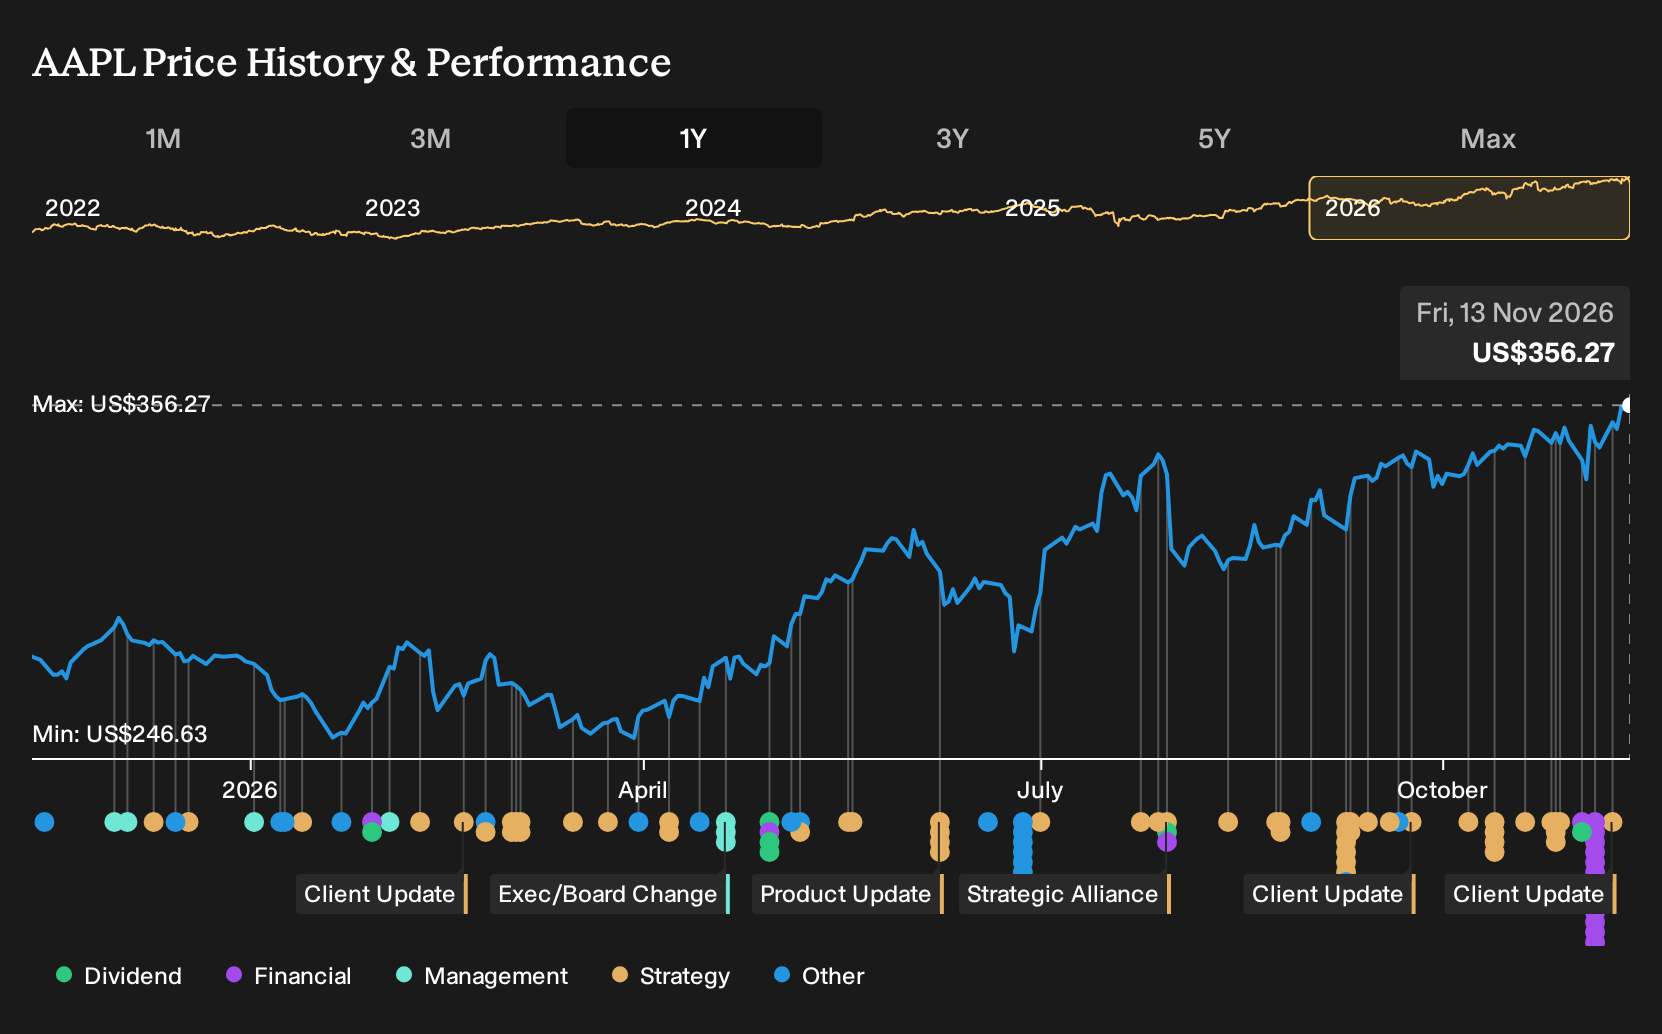
Using that experience-led view, Bob_B’s narrative reaches a fair value of US$253.43 per Apple share by assuming revenue expands at 6.5% a year with future profit margins at 27.0%, effectively tying valuation to steady top line growth and strong profitability supported by sticky, problem solving features like call screening.
Uncover why Apple's fair value indicates a 29% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the lowest Apple analysts lean hard into margin risk instead of AI upside. They see rising memory and compute costs, plus legal overhangs, limiting the payoff from apps like ROLR and other high engagement services. Before this news, their models had 2029 revenue at about US$572.8b and earnings near US$142.1b, a far more cautious story than the bullish targets. You can treat this launch as a prompt to compare those pre news assumptions with your own and to explore how differently others frame Apple’s future.
Explore 45 other Apple fair value estimates, including one that suggests as much as 49% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Apple research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Apple. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Apple's overall financial health at a glance.
Looking for more investment ideas beyond Apple?
Once you have formed a view on Apple, it helps to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you do that quickly by surfacing stocks that match the type of balance sheet strength, yield or upside you are looking for.
- If capital preservation sits high on your list, start with companies that screen for resilience and low risk scores using the 29 resilient stocks with low risk scores.
- Income focused investors can scan for stronger yield opportunities by reviewing a curated set of 6 dividend fortresses that might complement a position in Apple.
- If you are hunting for stocks that the market may be underestimating, widen your search to a 34 high quality undervalued stocks that pair quality fundamentals with a discounted price tag.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com