


Marqeta (MQ) Turns Profitable In Q3, Is It A Bargain Or Fully Priced?
Marqeta (MQ) is back in focus after third quarter results showed sales of US$176.18 million and net income of US$115.44 million, alongside fresh guidance pointing to single digit quarterly and low double digit full year revenue growth.
Marqeta’s latest earnings and guidance came as the share price has climbed roughly 17% over the past 90 days, even though the year-to-date share price return is slightly lower and the 1-year total shareholder return remains down 6.6%.
Spot opportunities beyond Marqeta by reviewing a curated set of payment and fintech peers with stronger balance sheets and cash generation in our list of solid balance sheet and fundamentals (24 results).Marqeta’s sharp swing back to profit and the recent 90 day share price climb tell very different stories. Is this move about fundamentals catching up, or sentiment running ahead of the valuation work.
Most Popular Narrative: 12% Undervalued
On the analyst consensus Narrative on Simply Wall St, Marqeta’s fair value sits at $20.65 compared with the last close at $18.23. This frames the recent profitability swing as only part of a bigger thesis around larger programs and new payment flows.
The build out of a unified money movement and digital asset stack that includes ACH, real time payments, wires, push to card, and stablecoin backed card payments positions Marqeta to participate in new payment flows beyond traditional cards and to generate incremental fee and value added services income that can support gross profit growth and operating margin expansion.
See why 14 investors see Marqeta as 12% undervalued.
Result: Fair Value of $20.65 (UNDERVALUED)
Still, the story can break if customer concentration around large partners unwinds faster than expected or if lower margin contracts continue to pressure Marqeta’s gross profit take rate.
Find out about the key risks to this Marqeta narrative.
Another View: Marqeta Looks Rich On P/E
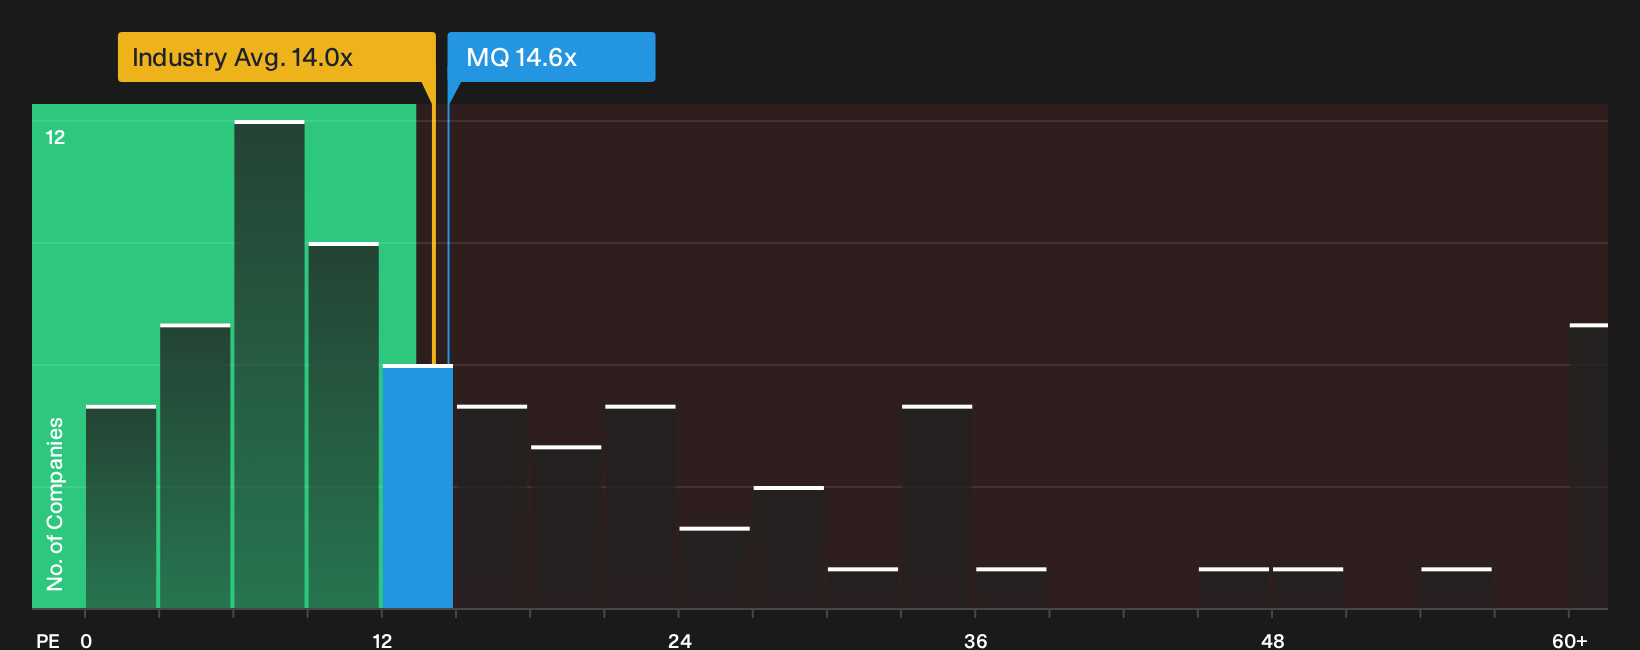
On a simple earnings multiple, Marqeta trades on a P/E of 14.6x, which is level with the wider US diversified financials sector at 14.6x but well above peer companies at 8.9x and the fair ratio of 6.1x. That gap points to clear valuation risk if sentiment cools.
For a second opinion that builds up from future cash flows rather than earnings multiples, it is worth looking at how the SWS DCF model treats Marqeta’s current price and assumptions.See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marqeta for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Marqeta is clearly split. This is exactly when it helps to move fast, review the numbers yourself and pressure test the story from both sides. To see how the upside case stacks against the concerns flagged by other investors, start with the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Marqeta?
If you stop with Marqeta, you risk missing other opportunities that better fit your goals, risk tolerance and income needs across the wider market.
- Target steady compounding by checking companies that pair strong cash generation with appealing valuations through our 34 high quality undervalued stocks.
- Boost your income potential by focusing on reliable payers with higher yields using the 6 dividend fortresses.
- Dial down portfolio risk by filtering for financially resilient businesses with robust balance sheets in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com