


What Bio Techne Holders Bought Into
If you only skimmed the headlines on Bio-Techne about funding pressure, sluggish organic sales, and activist agitation, a double digit payoff might not have been the outcome you expected. For Bio-Techne shareholders, the return over the past year was 23.4%, including dividends. If you were weighing a position back in November 2025, what did the mix of growth hopes, funding worries, and acquisition risk really signal about that eventual payoff?
The move put Bio-Techne in the middle of this trade. Scan 36 healthcare AI stocks for other companies exposed to it.
The Two Stories Investors Had To Choose Between On Bio-Techne
Bio-Techne shares cost US$60.75 at the start of the period, and anyone buying then had to choose between two very different stories about where the business might be headed.
The bullish script pointed to a Fair Value of US$80, a rough guide to what that camp thought the stock could be worth if its thesis played out. This view was built on faster take up of instruments like Simple Western Leo and Maurice, and high margin consumables tied into regulated bioprocessing lines.
The bearish view anchored on a Fair Value of US$54.08, again a price implied by its own assumptions. It focused on the risk that tight NIH budgets and weaker biotech funding would hold back demand from academic and smaller biotech customers.
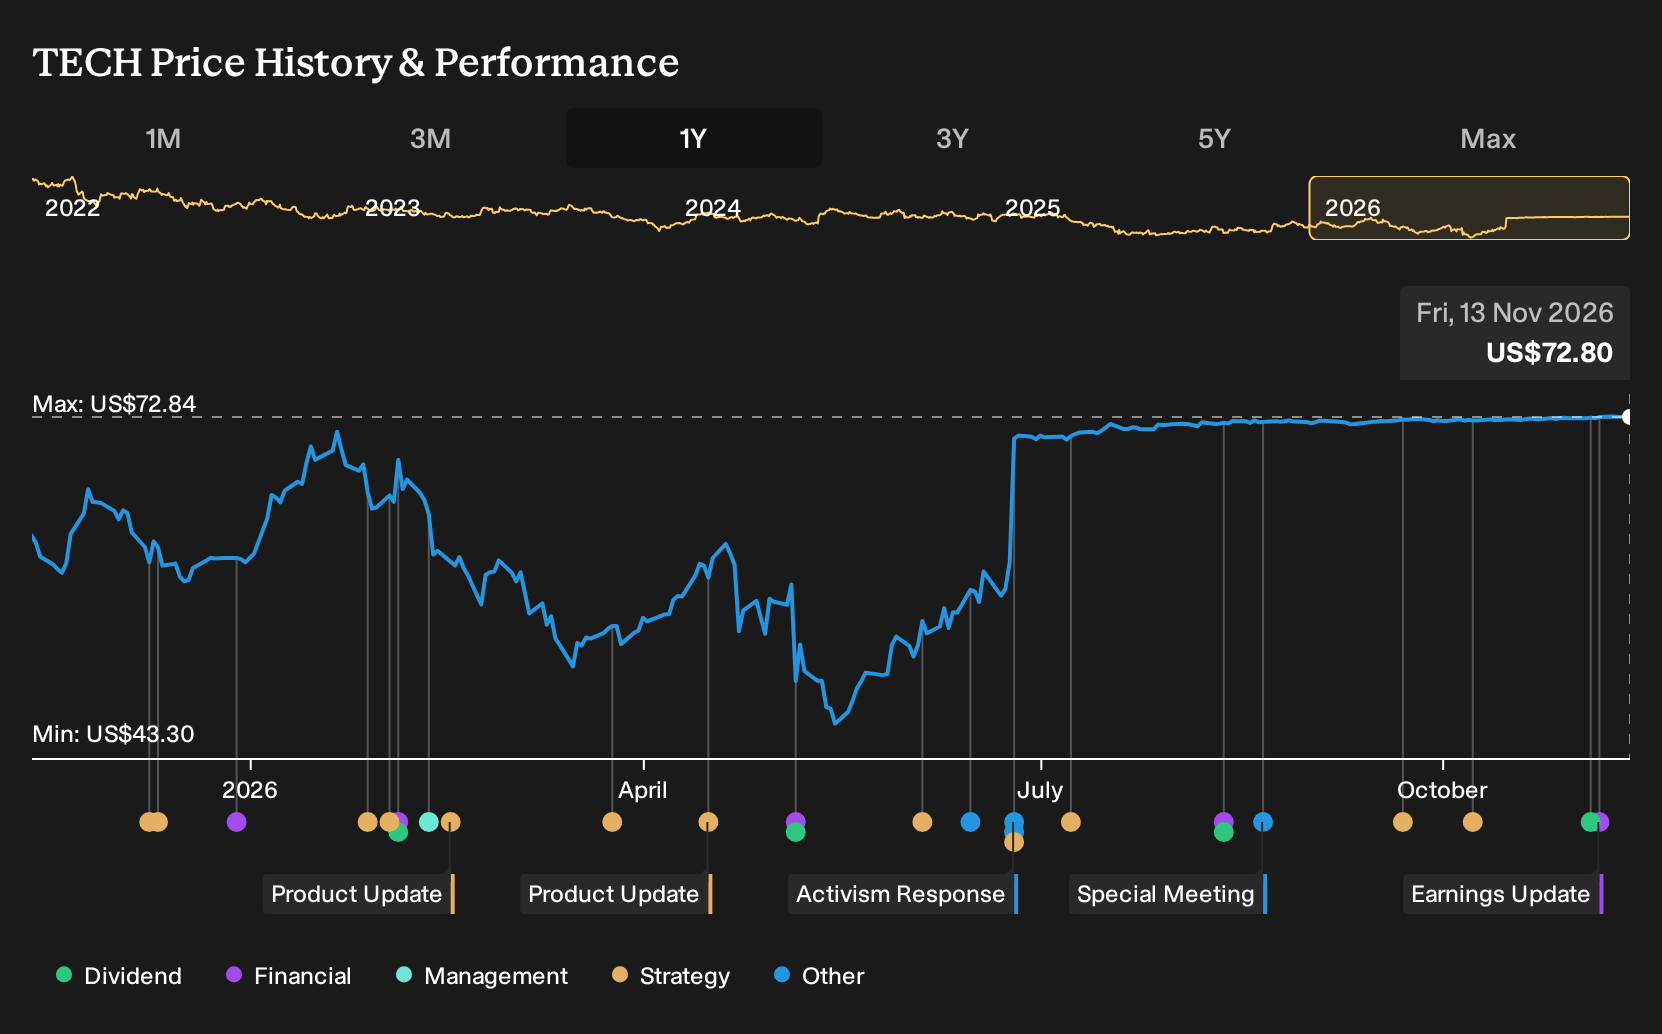
What The Results Changed For The Bio-Techne Debate
Merck KGaA’s agreement to acquire Bio-Techne in an all cash deal valued at about US$11.3b to US$11.5b, with a premium of roughly 36%, clearly leaned toward the bullish camp that argued a larger buyer might pay up for its platforms. The later Q1 2027 report told a cooler story. Revenue reached US$299.7m, but net income slipped to US$28.3m and net margin fell from 13.3% to 9.4%, so profitability traction stayed unproven. Overall, the evidence cut both ways.
The episode revolved around one assumption investors made in 2025. Bulls were effectively betting a buyer would value Bio-Techne’s tools portfolio more than near term margins. When you look at another stock with a similar debate, track two things separately: check whether operating margin is actually moving toward the story, and whether any takeover chatter is backed by a confirmed bid with a stated premium.
What Bio-Techne’s Price Now Asks You To Believe
Bio-Techne now trades at US$72.8, so anyone buying today is paying above where the bearish analyst Narrative on Simply Wall St places its Fair Value. That Narrative argues the current quote already builds in a full takeover premium and a clean rebound in the business.
The question is what must keep going right for that to hold. A buyer at today’s price has to judge whether Merck can capture promised synergies without crimping margins as mix shifts between instruments and higher margin reagents.
"The main thing that has to go right is for Bio-Techne to convert stronger engagement in proteomic analysis, spatial biology and cell therapy tools into sustained higher organic revenue growth without eroding its sector-leading margins."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond Bio-Techne’s Tools
Bio-Techne draws your eye to research gear and reagents. Yet the same labs and clinics often wrestle with chronic disease itself.
Those patients need drugs that manage obesity, diabetes and related complications. A different large healthcare group is trying to build that therapy backbone.
It develops treatments that target weight, blood sugar and certain cancers. The aim is broader access and capacity that can support more consistent medicine use.
For a Bio-Techne holder, that is a parallel thread. Tool spending and long term treatment demand might still move along the same chronic curves.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 18% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com